

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide PDMAT Market Hits $385M in 2025, Poised for 7.5% CAGR Through 2032

Navigating the Global PDMAT Market: Strategic Intelligence for Semiconductor Decision-Makers in 2026 and Beyond
The semiconductor industry stands at a critical juncture where material science, process engineering, and supply chain resilience intersect with unprecedented intensity. Among the specialized precursors enabling next-generation device architectures, Pentakis(dimethylamino)tantalum — commonly known as PDMAT — has emerged as a linchpin chemical for tantalum nitride barrier layer deposition in copper interconnects. The Worldwide PDMAT Market research report, published by PW Consulting, delivers a comprehensive, data-rich examination of this niche but strategically vital segment. For executives, procurement leaders, and R&D directors operating in 2026, the report offers more than retrospective data; it provides a forward-looking decision framework calibrated to the forecast horizon of 2026 through 2032.
This article serves as a strategic preview of the full study. It outlines the analytical architecture of the report, contextualizes the macroeconomic and competitive dynamics shaping the PDMAT landscape, and demonstrates how the intelligence contained within can be operationalized for capital allocation, vendor qualification, and technology roadmapping. As with any high-stakes market intelligence exercise, the goal is to equip leadership with the analytical scaffolding needed to ask the right questions — while the complete dataset, proprietary segmentation breakdowns, and granular regional forecasts remain accessible through the full report.
The PDMAT Value Chain in Context: From Precursor Chemistry to Wafer Fabrication
PDMAT functions as a solid tantalum precursor deployed in atomic layer deposition (ALD) and chemical vapor deposition (CVD) processes to form thin-film TaN diffusion barriers within semiconductor copper interconnects. As device geometries scale below critical thresholds, the integrity of these barrier layers directly influences reliability, signal integrity, and yield. The chemical's sensitivity to air and moisture necessitates rigorous handling protocols, specialized packaging formats including glass ampules, sealed bottles, and metal bubblers, and controlled inert-atmosphere logistics. These operational requirements elevate the importance of supplier capability, purity consistency, and regional availability in procurement decision-making.
The synthesis pathway itself carries strategic implications. PDMAT is typically produced through a metathesis reaction between tantalum pentachloride and lithium dimethylamide, followed by multi-stage purification designed to achieve ultra-high purity thresholds exceeding 99.99995 percent, with chloride content suppressed below 10 parts per million and oxygen levels driven to minimal extremes. Reaching these specifications is non-trivial and creates a technical barrier that differentiates established producers from newer entrants. For procurement teams evaluating supplier qualification pipelines, understanding the purification pedigree and quality assurance infrastructure of each candidate becomes a decisive factor — not merely a box-checking exercise.
PVDC Market
Beyond chemistry, the commercial structure of the market reflects a concentrated ecosystem. The industry's competitive dynamics are characterized by a handful of dominant players controlling a substantial share of global revenue, with a broader tier of specialized manufacturers and regional suppliers contributing to supply diversification. This concentration pattern carries implications for pricing stability, supply continuity, and negotiation leverage. The full report dissects these structural features through quantitative concentration metrics and qualitative assessments of each major participant's capabilities, geographic footprint, and technological positioning.
Market Trajectory and the 2026–2032 Forecast Horizon
The historical trajectory of the global PDMAT market from 2020 through 2025 reveals a sector that has expanded steadily against a backdrop of accelerating semiconductor complexity. In 2023, the overall market commanded a revenue base of approximately 333.64 million USD. That figure progressed to 358.67 million USD in 2024, and further to 385.0 million USD in 2025. The base year of the analysis, 2025, therefore anchors a growth narrative that continues into the forward-looking period.
Looking ahead, the forecast model projects sustained expansion across the 2026–2032 window. Revenue is anticipated to reach roughly 413.88 million USD in 2026, climbing to 444.92 million USD in 2027, then 478.29 million USD in 2028. The trajectory extends further to 514.16 million USD in 2029, 552.72 million USD in 2030, 594.17 million USD in 2031, and 638.73 million USD by 2032. This progression translates to a compound annual growth rate of 7.5 percent over the forecast horizon — a rate that signals robust demand elasticity tied to continued semiconductor node scaling, advanced packaging adoption, and broadening application requirements across logic, memory, and specialty device categories.
The 7.5 percent CAGR should be interpreted not as a blunt growth figure but as an indicator of underlying structural demand drivers. PDMAT's role in enabling sub-22 nanometer device generations, particularly for copper diffusion barriers, positions it at the heart of performance and reliability engineering. As wafer fabricators push toward finer feature sizes and more demanding interconnect architectures, the requirement for consistent, ultra-high purity precursors intensifies. The report's forecast methodology incorporates these demand-side fundamentals alongside supply-side capacity considerations, giving decision-makers a balanced view of where the market is heading and what variables could alter the path.
Competitive Architecture: Who Shapes the PDMAT Supply Landscape
The PDMAT market is defined by a competitive field that spans global specialty chemical conglomerates, dedicated precursor manufacturers, and regional specialists positioned to serve proximate semiconductor clusters. The full report provides detailed company profiles, capability assessments, and strategic positioning analysis for each key participant. Below is a curated overview of the prominent entities shaping supply dynamics.
Merck KGaA, operating through its EMD Group division and headquartered in Darmstadt, Germany, offers high-purity PDMAT as a solid tantalum precursor for ALD and CVD deposition of TaN barrier layers in semiconductor copper interconnects. The company maintains availability across major semiconductor geographies, including the United States, Korea, China, Taiwan, Japan, and Europe, giving it a broad logistical footprint that aligns with the geographic distribution of leading wafer fabrication sites.
Ereztech, based in the United States, manufactures and supplies PDMAT for ALD processes targeting semiconductor tantalum nitride thin film deposition. The company supports both small and bulk volume requirements and offers custom packaging configurations including glass ampules and metal bubblers, reflecting an operational emphasis on flexibility and application-specific delivery formats.
Strem Chemicals, now operating under Ascensus Specialties in Newburyport, Massachusetts, supplies research-grade PDMAT with a minimum purity of 98 percent for use as a CVD and ALD precursor. The research-grade orientation positions the company as a resource for pilot-scale evaluation, academic collaboration, and early-stage process development.
Within Taiwan's semiconductor ecosystem, Nanmat Technology stands as the island's largest CVD and ALD precursor manufacturer. Beyond PDMAT, the company produces and supplies a range of high-k and low-k materials for semiconductor customers, making it a multifaceted supplier for forward-looking fab operations. TOPCO Scientific Co., Ltd., also headquartered in Taiwan, supplies PDMAT within its high-performance materials division, reinforcing the region's concentration of precursor capability. PentaPro Materials Inc., another Taiwan-based entity, develops and produces organometallic products including PDMAT precursors for the semiconductor industry, contributing to the diverse supply base serving Asian fabrication hubs.
On the China side, Argosun provides high-purity five-nines PDMAT as a solid tantalum precursor for TaN barrier layers in semiconductor ALD and CVD processes. Sinocompound similarly supplies PDMAT as an electronic chemical for semiconductor thin film applications. Together, these China-based suppliers reflect the broader regional expansion of precursor manufacturing capacity and the strategic push toward supply chain localization.
Rounding out the competitive field, DOCK Chemicals, headquartered in Germany, manufactures ultra-high purity pentakis(dimethylamido)tantalum for semiconductor precursor applications. The emphasis on ultra-high purity aligns with the exacting specifications required for high-volume manufacturing in advanced device nodes.
These participants operate within a market structure where the top three firms collectively account for approximately 65.5 percent of revenue, while the top five extend their combined share to roughly 82.2 percent. Such concentration creates a landscape in which a limited number of suppliers exert significant influence over pricing norms, supply availability, and technical support standards. At the same time, the presence of specialized regional manufacturers and research-grade suppliers introduces alternative sourcing pathways for organizations seeking to diversify procurement strategies or access niche packaging formats.
Strategic Dynamics That Will Shape Procurement and Investment Decisions
Several structural dynamics merit close attention from executives evaluating PDMAT sourcing, capacity planning, and technology roadmaps. First, the handling and storage requirements of PDMAT impose real operational costs and logistical constraints. Because the material is highly sensitive to air and moisture, it must be managed under inert atmosphere conditions throughout the supply chain. It is classified for research and development use and is explicitly not intended for medicinal or household applications. These characteristics mean that packaging integrity, transportation controls, and receiving protocols become integral components of total cost of ownership assessments, extending beyond the listed price per unit.
Second, the market's growth is underpinned by volume and pricing signals that reflect the specialized nature of the product. Industry data places the global volume for penta(dimethylamino)tantalum at roughly 1,869 kilograms in 2024, with an average selling price near 2,978 USD per kilogram. While the full report avoids disclosing segment-level pricing decompositions in public summaries, these aggregate indicators signal a market where relatively modest physical volumes correspond to meaningful revenue pools — a pattern typical of high-value electronic chemicals. Procurement strategies must therefore weigh not only volume commitments but also consistency of specification, purity guarantees, and supplier reliability.
Third, the technical frontier continues to reward suppliers capable of delivering ultra-high purity at scale. The demand for TaN barrier layers in sub-22 nanometer device generations requires precursor materials that can sustain low oxygen and chloride contamination while maintaining batch-to-batch reproducibility. Novel purification methods and advanced quality control infrastructure have become differentiating capabilities. Organizations evaluating long-term supply agreements should assess whether potential partners possess the process engineering depth and analytical rigor to meet evolving device specifications without compromising yield or reliability.
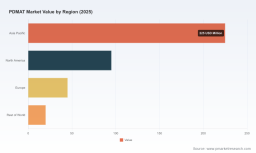
Fourth, regional demand distribution reflects the geography of semiconductor manufacturing. The Asia Pacific region remains the dominant revenue center, followed by North America and Europe, with the rest of world contributing a smaller but strategically relevant share. This geographic pattern aligns with the clustering of leading logic and memory fabrication sites. For multinational organizations operating across multiple regions, understanding variations in supplier availability, importation logistics, and local specification requirements is essential for building resilient procurement architectures.
What the Full Report Delivers: An Operational Toolkit for 2026 Decision-Making
While this preview highlights the macro structure and competitive contours of the PDMAT market, the complete Worldwide PDMAT Market research report goes substantially further. It is designed as a practical decision-support instrument rather than a passive data repository. The study integrates historical analysis from 2020 through 2025 with forward-looking forecasts spanning 2026 through 2032, all expressed in million USD and anchored to a transparent analytical methodology.
Key components of the full report include:
Worldwide PDMAT Market
- A detailed market size and growth forecast that traces revenue progression across the forecast window, enabling financial planning, budgeting, and scenario modeling for procurement and R&D investment cycles.
- Strategic segmentation analysis examining market structure across major axes including region, grade, and deposition method. The report dissects how ultra-high purity electronic-grade material compares with standard industrial-grade supply, and how ALD and CVD application preferences shape demand distribution. The complete segmentation breakdowns, including precise regional and application-level figures, are provided in full within the downloadable dataset.
- Company profiles and competitive benchmarking for the leading PDMAT suppliers, covering headquarters locations, product offerings, geographic availability, packaging capabilities, and technological positioning. This section allows procurement teams to map supplier strengths against internal qualification criteria.
- An assessment of market concentration, including the revenue share held by top-tier participants, which helps decision-makers evaluate supply risk, negotiation dynamics, and the feasibility of multi-sourcing strategies.
- Contextual industry intelligence addressing synthesis pathways, purification requirements, handling and storage protocols, packaging formats, and regulatory classifications. These operational details support vendor evaluation, logistics planning, and laboratory or fab-side safety compliance.
- An examination of underlying demand drivers tied to semiconductor device scaling, interconnect architecture evolution, and the broader adoption of ALD and CVD processes in advanced manufacturing.
The report is structured to serve multiple stakeholder groups. Procurement leaders can use the supplier profiles and concentration data to inform qualification pipelines and negotiate terms with an awareness of market structure. R&D directors can draw on the purity, handling, and packaging intelligence to align precursor specifications with process requirements. Strategic planners and executive teams can leverage the forecast trajectory and regional demand context to prioritize investments, anticipate supply constraints, and evaluate long-term sourcing architectures.
Translating Intelligence into Action: How 2026 Leaders Can Use This Report
Market intelligence delivers value only when it informs concrete decisions. For organizations operating in the semiconductor materials ecosystem, the Worldwide PDMAT Market report provides several immediate applications. Leaders can benchmark internal procurement assumptions against independent market size and growth estimates, reducing reliance on anecdotal supplier claims. Teams can structure request-for-quotation processes with clearer expectations around purity thresholds, packaging formats, and volume flexibility. Supply chain managers can evaluate vendor diversification strategies in light of concentration metrics and regional availability patterns. Technology roadmapping groups can align precursor qualification timelines with anticipated device node transitions and the corresponding demand for TaN barrier layer materials.
The report also facilitates scenario planning. Because the forecast period extends through 2032, decision-makers can model how changes in device adoption rates, regional capacity expansion, or supplier entry and exit might affect pricing stability and availability. This extended horizon is particularly valuable for capital-intensive organizations that must make sourcing commitments with multi-year implications. Rather than reacting to short-term fluctuations, leaders can position procurement architectures to absorb variability while preserving quality and continuity.
Conclusion: Accessing the Complete Intelligence
The PDMAT market may operate at the scale of specialized electronic chemicals rather than commodity volumes, but its strategic significance within semiconductor manufacturing is substantial. As device architectures advance and fabrication requirements grow more exacting, the availability of ultra-high purity tantalum precursors with reliable supply chains and proven purification pedigrees becomes a critical enabler of performance and yield. The Worldwide PDMAT Market research report from PW Consulting captures this landscape in granular detail, combining historical analysis, forward-looking forecasts, competitive profiling, and operational context into a single decision-ready resource.
The preview presented here underscores the breadth and analytical rigor of the full study while preserving the complete segmentation data, regional breakdowns, and granular financial figures for direct access through the source platform. Executives who require precise regional revenue splits, grade-level comparisons, and deposition-method distributions will find those insights fully documented in the complete report. To obtain the comprehensive dataset, detailed tables, and proprietary analysis underpinning the strategic overview above, visit the official PW Consulting Worldwide PDMAT Market report page and secure your copy of the full intelligence package.
For detailed analysis of this topic, please visit the official page: Worldwide PDMAT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com