

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Paper Napkin Market Hits $5,000M in 2025, Forecast 4.31% CAGR to 2032

Navigating the Napkin Economy: Strategic Intelligence for the Global Paper Napkin and Serviette Market Through 2032
The global paper napkin and serviette market is entering a period of structural transformation where volume growth, sustainability mandates, and input cost volatility intersect. For executives operating across foodservice, retail, and institutional channels, the difference between resilient margin performance and strategic drift will increasingly depend on access to granular, forward-looking intelligence. Our latest Worldwide Paper Napkins and Serviettes Market study is engineered to provide exactly that: a decision-grade framework that translates historical performance, competitive maneuvering, and regulatory momentum into executable strategy for 2026 and beyond.
This report is not a retrospective snapshot. It is a living strategic compass designed to help leadership teams size opportunity, anticipate supply-side friction, and position portfolios ahead of shifting consumer and buyer expectations. Below, we outline the analytical architecture of the study, the competitive dynamics it unpacks, and the operational levers it brings into focus.
Market Trajectory: A Decade of Resilient Demand and Structural Inflection
Drawing on a consolidated historical baseline spanning 2020 through 2025, the study maps a market that has consistently expanded despite periodic input cost shocks, supply chain disruptions, and fluctuating away-from-home activity. The broader revenue trajectory underscores a category that has moved well beyond cyclical recovery and is now operating within a structurally elevated demand environment. By the base year of 2025, total market revenue reached approximately USD 5,000.0 million, reflecting the cumulative effect of foodservice normalization, sustained household consumption, and incremental premiumization in certain away-from-home segments.
The forward outlook reinforces this momentum. The analysis projects a forecast period from 2026 through 2032, during which the market is expected to advance at a compound annual growth rate of 4.31 percent. This growth path is neither linear nor uniformly distributed across end-use channels or geographic corridors; rather, it is shaped by divergent consumption patterns, shifting hospitality activity, and the pace at which sustainability-driven product formats gain commercial traction. The report quantifies these pathways without relying on simplistic top-line extrapolations, instead modeling the interplay between volume, pricing, product mix, and channel economics.
For decision-makers, this macro trajectory matters because it defines the envelope of opportunity. A market advancing at this pace creates room for share gains, but only for organizations that understand where growth concentrates, which product architectures command price resilience, and how procurement cycles align with capacity expansions. Our study surfaces those intersections so that strategy teams can prioritize investments rather than react to aggregated industry noise.
Report Architecture: From Sizing to Execution
The study is structured to move seamlessly from broad market quantification to actionable commercial insight. Rather than presenting a single static view, it decomposes the industry across the dimensions that most directly influence procurement, product development, and go-to-market planning.
At its foundation, the report delivers a disciplined segmentation of the market along three axes that matter to operators:
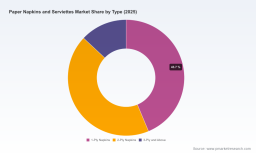
- Product architecture, capturing the relative commercial weight and growth behavior of single-ply, two-ply, and multi-ply formats, each of which serves distinct absorbency, cost, and presentation requirements across channels.
- Application footprint, distinguishing between foodservice and hospitality-driven demand and household retail consumption, two end-use environments with fundamentally different purchasing triggers, margin structures, and sustainability expectations.
- Regional distribution, mapping how demand, competitive intensity, and supply economics differ across major global corridors without reducing the picture to oversimplified rankings.
Beyond segmentation, the analysis incorporates market concentration metrics that reveal the degree of competitive cohesion in the category. By quantifying the share held by leading participants, the study helps readers assess where pricing power resides, how vulnerable supply bases may be to consolidation, and which market segments remain accessible to challengers or niche innovators. This concentration lens is particularly valuable for procurement teams evaluating supplier diversification and for commercial leaders assessing potential partnership or acquisition targets.
The report also integrates a forward-looking demand and supply framework that ties historical consumption behavior to anticipated shifts in hotel, restaurant, and institutional activity, retail basket composition, and the adoption of certified or recycled-content products. Crucially, it pairs this demand view with a supply-side assessment that accounts for capacity additions, fiber sourcing strategies, and the operational implications of regulatory pressure on material composition. The result is a multi-variable perspective that supports scenario planning rather than single-point forecasting.
Competitive Dynamics: Strategy, Scale, and the Sustainability Imperative
The paper napkin and serviette landscape is defined by a mix of global household names, regionally anchored manufacturers, and specialized players that compete on customization, certification, or channel intimacy. The study profiles the companies shaping this environment, examining how each leverages brand equity, distribution reach, product engineering, and sustainability positioning to defend or expand its footprint.
In North America, major consumer and away-from-home players continue to rely on established brand franchises while progressively shifting product specifications toward higher recycled content and reduced packaging footprint. Their strategies illustrate a broader industry theme: defending share in mature channels while using formulation and packaging changes to meet buyer expectations and regulatory drift. These moves are not cosmetic. They influence procurement cost structures, reorder economics, and the narrative that foodservice operators can use in their own sustainability reporting.
Across the Atlantic, European manufacturers emphasize professional hygiene, dispenser-linked consumption control, and certified sustainable sourcing. Several of these organizations compete not only on the napkin itself but on the systems surrounding it, including dispensing technology designed to reduce consumption without compromising user experience. That system-level approach reflects a market where total cost of use, waste reduction, and compliance documentation increasingly determine supplier selection in commercial and institutional settings.
In Asia and other high-growth corridors, manufacturers are building capacity and export-oriented supply chains that combine cost competitiveness with expanding sustainability credentials. Their growth is tied both to domestic consumption and to their ability to serve international foodservice, retail, and hospitality buyers seeking reliable volume at competitive terms. The study evaluates how these players are positioning themselves relative to established Western suppliers and where their scale, logistics, or product mix may create differentiated value.
Recent corporate activity reinforces how actively the competitive field is evolving. In early 2026, one leading European hygiene supplier expanded its next-generation dispenser platform across multiple markets, targeting meaningful reductions in napkin consumption per service cycle. That launch highlights a strategic shift from selling units to selling efficiency and waste reduction. Shortly before that, a major European manufacturer inaugurated a new tissue production facility in the United States, adding substantial annual capacity that includes napkin production and signaling a deliberate push into North American supply proximity. Earlier in 2025, another global consumer and away-from-home player completed a reformulation effort that materially increased recycled content and moved to fully recycled packaging, while a North American producer launched a certified compostable, fully recycled-fiber line aimed at healthcare and foodservice buyers. Together, these moves illustrate a market in which sustainability, capacity geography, and product certification are becoming central competitive variables rather than peripheral corporate initiatives.
The study takes these developments seriously not as isolated press items, but as indicators of where margin pools, risk exposure, and differentiation opportunities are shifting. It examines how rival strategies interact, where substitution risk is rising, and which capabilities are becoming table stakes for commercial relevance.
Industry Dynamics: Regulation, Inputs, and the Cost of Sustainability
No strategy for this market can be built on demand alone. The study deliberately integrates the operational and regulatory forces that determine whether growth translates into profitable growth. One of the most consequential themes is the tightening relationship between sustainability expectations and product specification. Across foodservice, healthcare, and retail environments, buyers are increasingly aligning procurement with compostability certifications, recycled-fiber content, and responsible sourcing claims. This is not simply a marketing trend; it is reshaping specification lists, tender requirements, and the relative attractiveness of conventional versus certified product formats.
At the same time, input cost dynamics remain a persistent strategic challenge. Pulp-based tissue economics are exposed to volatility in fiber markets, energy costs, and regional pricing mechanisms. Recent observations in the broader tissue and pulp environment point to elevated pricing levels and intermittent upward pressure on key material indices, with notable movements in pulp benchmarks and regional jumbo roll pricing during the first part of 2026. These fluctuations matter because they influence production economics, quote stability, and the pace at which manufacturers can invest in reformulation or capacity expansion without compressing margins.
The study translates this complexity into operational insight. It identifies where cost pressure is most likely to affect contract terms, where premiumization or format innovation can offset input inflation, and how procurement teams can structure sourcing strategies that balance resilience with cost discipline. Just as importantly, it explores how sustainability-related regulation and buyer standards in major markets are reshaping demand for certified compostable and high-recycled-content napkins, creating both compliance obligations and commercial differentiation opportunities for suppliers that can credibly meet them.
Strategic Implications for 2026 Decision-Making
For executives planning the next twelve to twenty-four months, the market presents a clear set of strategic questions. Which product architectures should anchor the portfolio in foodservice versus household retail? Where does sustainability certification create genuine commercial leverage rather than mere compliance cost? How should capacity, sourcing, and supplier relationships be configured in light of input volatility and regional demand divergence? And where does competitive intensity make share gain unlikely unless supported by differentiated value propositions such as dispenser-linked consumption control, certified compostability, or proximity-driven supply reliability?
Paper Towels Market
The study is designed to help answer these questions with specificity. It equips commercial leaders with the segmentation detail needed to prioritize channel and format investments, supports procurement and supply chain teams in evaluating sourcing risk and supplier viability, and provides competitive intelligence that clarifies which rivals are building durable advantages versus merely defending positions. By connecting market size, growth trajectory, concentration, and recent corporate moves to the operational realities of pulp economics and sustainability regulation, the report creates a unified basis for strategy formulation.
Worldwide Paper Napkins and Serviettes Market
Ultimately, the value of this research lies in its ability to convert broad market momentum into executable direction. A 4.31 percent compound growth outlook over the forecast horizon signals opportunity, but opportunity in this category belongs to organizations that understand the structure beneath the headline number. The report delivers that structure.
Access the Full Strategic Framework
This article provides a high-level view of the study’s analytical scope and strategic relevance, but the decision-grade detail resides in the full report. The complete Worldwide Paper Napkins and Serviettes Market analysis contains the segmentation breakdowns, regional demand mapping, competitive profiling, concentration metrics, and forward scenarios that leadership teams need to translate market momentum into precise commercial choices.
For organizations that require deeper visibility into where growth concentrates, how competitors are re positioning around sustainability and capacity, and what input-cost and regulatory dynamics mean for near-term sourcing and product strategy, the full study offers the comprehensive intelligence necessary to act with confidence. Exploring the complete analysis is the logical next step for any team seeking to align its 2026 planning with a rigorous, data-grounded view of the global paper napkin and serviette landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Napkins and Serviettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com