

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global High-Capacity NFC Chip Market to Reach $1.53B by 2032 at 12.71% CAGR

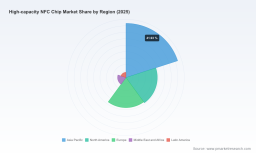
Strategic Intelligence for the Next Era: Inside the Worldwide High-capacity NFC Chip Market
The global transition toward contactless, secure, and data-rich interactions is no longer a speculative trend. It is an operational imperative. As enterprises across transportation, healthcare, consumer electronics, luxury authentication, and industrial monitoring embed radio-frequency identification into daily workflows, the underlying silicon must evolve. Memory capacity, read-range reliability, cryptographic resilience, and protocol interoperability now dictate product competitiveness. For leadership teams planning capital allocation, supplier partnerships, and technology roadmaps in 2026, a clear, granular view of the high-capacity NFC chip landscape is not optional. It is a strategic differentiator.
This editorial introduces PW Consulting’s latest Worldwide High-capacity NFC Chip Market research. Designed as an executive decision-support instrument, the study maps historical trajectories, quantifies growth vectors, dissects competitive positioning, and translates supply-chain realities into actionable procurement and product strategies. What follows is an overview of the research architecture, the market forces it captures, and the strategic value it delivers to organizations navigating an increasingly complex contactless semiconductor ecosystem.
Worldwide High-capacity NFC Chip Market
Macro Trajectory: From Incremental Growth to Sustained Expansion
Historical revenue data published in the report traces a consistent upward curve across the 2020–2025 baseline period. Market valuation moved from the mid-365 million range in 2020 to approximately 664 million by 2025, reflecting accelerating adoption in transit systems, pharmaceutical logistics, premium authentication, and smart-device ecosystems. This expansion did not emerge from a single vertical. It was driven by compounding demand: higher memory requirements for secure credential storage, richer data payloads for cold-chain and asset-tracking applications, and the migration of legacy low-capacity tags toward next-generation high-capacity variants.
The forward-looking window corroborates this momentum. The research models sustained growth through the 2026–2032 forecast horizon, with projected revenue scaling steadily toward the 1.5-billion range by the end of the period. The implied compound annual growth rate of 12.71 percent underscores a market that is not merely recovering from post-pandemic normalization, but structurally expanding. For enterprise planners, this trajectory signals that high-capacity NFC is transitioning from a niche specification to a mainstream design requirement across multiple verticals.
Revenue is tracked in U.S. dollars, expressed in millions, providing a consistent baseline for cross-market comparison. The report deliberately abstracts away from fragmentation that obscures strategic signal, allowing executives to focus on total addressable expansion, inflection points, and the pacing of adoption across application domains rather than getting lost in isolated regional or segment-level accounting.
Chip Antenna Market
Why 2026 Decisions Require a Granular View
Year 2026 represents a pivotal planning juncture. Several converging dynamics make static assumptions dangerous. First, the operational requirements of end-use sectors are shifting faster than legacy chip architectures can accommodate. Transit operators are demanding richer passenger-data management and tamper-resistant ticketing. Healthcare and pharmaceutical stakeholders require authenticated, high-integrity tracking that can withstand regulatory scrutiny. Consumer-electronics and gaming brands seek seamless tap-to-pair experiences with enhanced security. Luxury-goods manufacturers increasingly rely on cryptographic verification to combat counterfeiting. Industrial and cold-chain operators need tags that survive harsh environments while storing extended sensor logs.
Second, the competitive set is not standing still. Tier-one semiconductor vendors are continuously refreshing product lines, expanding memory ceilings, and embedding features that blur the line between passive tagging and intelligent edge connectivity. Product launches in 2025 already point toward higher read rates, self-adjusting RF optimization, secure key storage, and protocol-level compatibility with emerging smart-home and IoT onboarding standards. These releases reshape design-in criteria and influence sourcing strategies.
Third, supply-side pressures are redefining procurement timelines and cost structures. Extended lead times for certain silicon wafers and packaging substrates have pushed delivery windows for advanced high-capacity variants into longer cycles, influencing inventory planning and pricing negotiations. Simultaneously, strategic price adjustments across major product lines, driven by materials, energy, and manufacturing cost escalations, are altering total-cost-of-ownership calculations. The report captures these dynamics in a structured framework, allowing buyers and product planners to evaluate risk exposure, contract timing, and alternate sourcing pathways with greater precision.
Finally, regulatory and trade environments remain fluid. Export control measures and commerce ministry policies affecting certain semiconductor components and sub-assemblies introduce continuity considerations for organizations with cross-border production or assembly footprints. The study integrates these contextual factors so that market sizing and competitive analysis are interpreted through a realistic operational lens rather than a purely theoretical one.
Research Architecture: What the Report Delivers
PW Consulting structured the research to serve multiple internal stakeholders simultaneously: product management, procurement, strategy, and investor relations. Instead of presenting a single aggregated figure, the report decomposes the market along dimensions that matter for decision-making, while deliberately withholding the granular percentage splits and exact dollar allocations in this summary to preserve the analytical edge of the full publication.
The segmentation framework includes:
- Regional distribution: A structured mapping of how demand concentrates across major geographic corridors, with contextual commentary on adoption maturity, infrastructure readiness, and localized supply dynamics.
- Memory-capacity tiers: An analysis of how demand partitions across low-to-mid capacity ranges and higher-capacity variants, reflecting different application needs, security requirements, and cost-performance trade-offs.
- End-use industry verticals: A detailed examination of how transportation, healthcare and pharmaceuticals, consumer electronics and gaming, luxury authentication, and industrial/cold-chain monitoring each shape specification requirements, purchasing cycles, and technology roadmaps.
Beyond segmentation, the report delivers operational content designed for immediate use:
- Competitive profiling: Company-by-company assessments covering product portfolios, technical differentiators, headquarters and operational footprint, and strategic positioning within high-capacity NFC and adjacent contactless technologies.
- Recent development tracking: Timestamped coverage of product launches, announcements, and technical enhancements that influence design-in windows and specification standards, including high-performance HF tag ICs, secure smart-home onboarding solutions, and multi-protocol contactless architectures.
- Market concentration analysis: Quantitative framing of top-player dominance to help readers gauge bargaining dynamics, innovation velocity, and the risk/reward balance of supplier consolidation versus diversification.
- Supply-chain and pricing context: An integrated discussion of lead-time extensions, average selling price pressures on advanced variants, and material cost trends, enabling more accurate forecasting and contract structuring.
- Regulatory and trade context: A concise synthesis of export-control and commerce measures that touch semiconductor supply continuity, with practical implications for sourcing and production planning.
This architecture ensures that the report functions as both a market map and a decision toolkit. Readers can connect macro growth signals to segment-level drivers, align procurement strategies with supplier innovation calendars, and stress-test product roadmaps against realistic supply and pricing conditions.
Competitive Landscape: Positioning, Innovation, and Strategic Implications
The high-capacity NFC chip arena is shaped by established semiconductor leaders with broad portfolios and specialized capabilities. The report profiles the companies that consistently influence specification standards, design-in momentum, and supply availability. Each profile is evaluated not only on technical specifications, but on strategic posture: how product roadmaps align with vertical demand, how security and memory features differentiate offerings, and how geographic and operational footprints affect supply resilience.
Several themes emerge from the competitive analysis. One is the movement toward higher effective memory and faster, more robust RF performance. Recent high-performance tag IC introductions highlight user memory expansions and improved read rates, coupled with features such as self-adjusting RF optimization and tamper-detection options. These enhancements directly serve IoT labeling, vicinity applications, and use cases where reliability and data integrity are non-negotiable.
A second theme is the convergence of NFC with broader smart-environment protocols. Secure NFC solutions designed for smart-home onboarding, digital signature capabilities, and secure key storage reflect an industry pushing beyond simple identification toward authenticated, battery-less commissioning and trusted device pairing. These developments alter the criteria by which product teams evaluate tag ICs for consumer and connected-home applications.
A third theme is multi-protocol flexibility and security integration. Solutions supporting secure, high-capacity contactless transactions across payments, identification, and industrial contexts continue to refine cryptographic handling, interface options, and protocol compatibility. Mobile-optimized ICs with crypto features and multiple interface pathways illustrate how handset and lifestyle ecosystems are pushing for compact, secure, and versatile contactless subsystems. Meanwhile, FeliCa-compliant IC chips provide secure high-capacity contactless options widely used in payments and transit, reinforcing the importance of regional standard alignment and interoperability planning.
The report also quantifies market concentration to help executives interpret competitive intensity. A high concentration among top players indicates strong incumbency advantages in R&D, reference designs, and supply relationships, but it also highlights the importance of monitoring innovation cycles, negotiating leverage, and fallback options. Understanding concentration is not about counting vendors; it is about anticipating how pricing, availability, and feature roadmaps will evolve when a few firms shape a disproportionate share of the market.
Strategic Playbook: Turning Market Intelligence into 2026 Action
For organizations preparing 2026 initiatives, the report supports several practical moves:
- Specification alignment: Match memory-capacity selection and protocol requirements to real vertical needs rather than over-engineering or under-specifying. The segmentation analysis clarifies where higher-capacity variants justify their cost and where mid-range options remain sufficient.
- Supplier strategy: Use competitive profiles and concentration metrics to balance incumbency benefits against diversification needs. The tracking of recent product releases helps teams anticipate design-in windows and evaluate alternate sources before supply tightness constrains options.
- Procurement timing and cost modeling: Factor extended lead times and recent price adjustments into inventory planning, contract negotiation, and total-cost-of-ownership estimates. The report’s supply-chain context helps teams avoid surprises and structure agreements that protect margin and continuity.
- Regulatory risk planning: Incorporate export-control and commerce-policy considerations into sourcing and production-continuity roadmaps, particularly where cross-border operations or sub-assembly dependencies exist.
- Product roadmap validation: Stress-test device and system designs against evolving tag capabilities, security expectations, and interoperability standards. The report’s focus on recent launches and protocol-level developments offers a forward-looking reference for feature prioritization.
Conclusion: Access the Full Intelligence
The Worldwide High-capacity NFC Chip Market is expanding at a pace that rewards organizations who plan with evidence rather than assumption. Macrosignal growth, segment-level divergence, competitive innovation, and supply-side realities all point to one conclusion: the window for informed positioning is open, but it will not remain wide indefinitely. The full PW Consulting report transforms these signals into a structured, decision-ready format—providing the granularity, supplier context, and operational framing that executives need to act with confidence.
To access the complete segmentation analysis, exact regional and industry breakdowns, detailed company profiles, and the full set of strategic recommendations, visit the official research page and download the complete publication. The summary presented here is designed to demonstrate analytical depth and set expectations; the complete report delivers the data precision and operational detail your 2026 planning requires.
For detailed analysis of this topic, please visit the official page: Worldwide High-capacity NFC Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com