

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Coconut Shell Activated Carbon Market to Grow at 9.15% CAGR, Valued at $480.87M in 2025

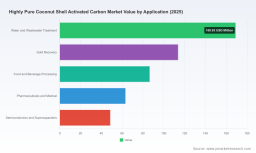
Strategic Intelligence for the 2026 Horizon: Why Highly Pure Coconut Shell Activated Carbon Demands Executive Attention
The global market for highly pure coconut shell activated carbon is entering a period of accelerated transformation. As industries confront tightening environmental regulations, rising raw material costs, and evolving purification standards, the need for precise, forward-looking intelligence has never been greater. Our latest Worldwide Highly Pure Coconut Shell Activated Carbon Market study is designed as a strategic compass for decision-makers navigating this complex landscape through 2026 and beyond. This report does not simply present static figures. It delivers a layered, actionable intelligence framework that maps structural shifts, competitive realignments, and demand catalysts across the value chain, enabling leadership teams to align capital allocation, sourcing strategy, and product positioning with measurable market momentum.
Macro Trajectory: A Market Accelerating on a Compounding Growth Arc
Drawing on a comprehensive historical baseline spanning 2020 through 2025 and extending into a rigorous forecast window through 2032, the research quantifies a market that has consistently expanded its revenue footprint at an accelerating pace. The compound annual growth rate of 9.15 percent underscores a sector that is outpacing broader industrial filtration benchmarks. Total market revenue climbed from USD 310.25 million in 2020 to USD 480.87 million by 2025, reflecting a sustained escalation in procurement volumes, premium-grade adoption, and cross-industry purification requirements. The forward trajectory projects continued expansion, with total market revenue anticipated to approach USD 520.34 million in 2026 and continue its ascent toward the upper-range forecasts by the early 2030s.
This growth curve is not merely a function of volume. It reflects a structural recalibration in how end-users evaluate adsorption efficiency, purity thresholds, and lifecycle performance. The pricing dynamics observed over the past eighteen months further reinforce the urgency of strategic preparedness. With average import prices for coconut shell charcoal-based activated carbon climbing to USD 2,502 per metric ton in the first half of 2025, up from USD 2,078 per metric ton in 2024, procurement teams and product developers alike must recalibrate cost models, hedging approaches, and supplier negotiations. The market’s compounding trajectory signals that passive procurement strategies will increasingly yield margin compression, while proactive, intelligence-led positioning will capture structural upside.
Inside the Research: What Decision-Makers Will Find
The report is engineered as an operational reference tool rather than an academic overview. It translates high-level market signals into executable frameworks for sourcing, product development, competitive benchmarking, and regional expansion. Readers will encounter a systematic breakdown of the market architecture, anchored in a detailed segmentation analysis that isolates the performance characteristics, demand intensity, and pricing sensitivities across product forms and end-use verticals. The study maps how granular activated carbon continues to anchor large-volume industrial purification, while powdered and extruded or pelletized formats capture specialized applications where particle geometry, flow dynamics, and adsorption kinetics dictate procurement decisions.
Equally central to the research is a granular competitive landscape assessment that profiles the dominant manufacturers shaping global supply. Companies such as Haycarb PLC, with its expansive production footprint and low-ash, high-hardness grades sourced from Sri Lanka, Indonesia, and Thailand; Jacobi Carbons Group, whose global manufacturing network emphasizes sustainable sourcing and high-purity water and air purification grades; Raj Carbon and Kalpaka Chemicals, whose Indian-based capacities target process water, air filtration, and industrial purification at scale; and a broad roster of specialized producers including Activcarb, CG Carbon, Concepts Ecotech, Carbon Activated Corporation, Karbonous Inc., Mellifiq, Xingsen Carbon, TingyuanCarbon, Qizhong Carbon, Hongsen Carbon, Starke Aquacare Technologies, and Innizh Carbon are examined through a strategic lens. The analysis unpacks how geographic positioning, feedstock access, activation technology, and capacity investments influence pricing power, supply resilience, and customer lock-in across major application sectors.
The study also integrates a thorough review of recent market-moving developments that directly affect 2026 planning horizons. Jacobi Carbons Group’s 15 to 20 percent price increase across coconut shell-based activated carbons, implemented in mid-2025 in response to escalating feedstock costs, exemplifies the pricing recalibration now permeating the industry. Concurrently, U.S. import data showing approximately 30,460 metric tons of coconut shell charcoal-based activated carbon valued at USD 76.22 million during the first seven months of 2025 highlights both sustained demand intensity and the tightening supply environment. These developments are contextualized within broader raw material dynamics, including the sharp upward revision in coconut shell charcoal pricing across Sri Lanka, Indonesia, and India between late 2024 and mid-2025, and the expectation that supply constraints will persist into 2026.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The market’s competitive architecture reflects a blend of established global manufacturers, regionally anchored specialists, and fast-expanding producers investing in automation, capacity, and purity optimization. With a CR3 concentration level indicating meaningful share held by leading producers and a CR5 metric reflecting further consolidation among top-tier players, the industry rewards scale, feedstock security, and consistent quality assurance. Yet the presence of multiple high-capacity producers across South Asia, East Asia, and North America ensures that competitive dynamics remain highly active, particularly as buyers evaluate total cost of ownership, batch consistency, and compliance with evolving industry specifications.
Haycarb PLC’s recent inauguration of a fully automated activation plant in Eastern Sri Lanka, adding 7,500 metric tons of annual production capacity, illustrates how leading incumbents are investing in process automation and throughput to reinforce quality consistency and supply reliability. At the same time, regional manufacturers such as Raj Carbon, Kalpaka Chemicals, Activcarb, and CG Carbon continue to expand their granular and powdered product portfolios to serve industrial water treatment, air filtration, and purification end markets with strong proximity to feedstock sources and export logistics. In China, producers including Xingsen Carbon, TingyuanCarbon, Qizhong Carbon, and Hongsen Carbon are scaling high-iodine, low-ash grades that address stringent drinking water, gold recovery, food processing, and air purification requirements, while U.S.-based and European-linked players such as Carbon Activated Corporation, Karbonous Inc., and Mellifiq emphasize integrated solutions spanning manufacturing, regeneration, and filtration system integration.
This competitive density does not dilute strategic differentiation. Instead, it sharpens the importance of understanding which manufacturers possess durable advantages in feedstock access, activation technology, quality certification, and logistics networks. The report evaluates each profiled company against these dimensions, clarifying where scale translates into pricing resilience, where regional sourcing provides cost and lead-time advantages, and where specialized pore-structure engineering creates premium positioning in high-purity applications.
Worldwide Highly Pure Coconut Shell Activated Carbon Market
Market Dynamics Shaping the 2026 Decision Environment
Several interlocking forces are reshaping procurement, pricing, and product strategy as organizations plan for 2026. The first is raw material supply pressure. Coconut shell charcoal prices across major producing countries have followed a pronounced upward trajectory, driven by reduced coconut production and tightening shell availability. With price levels in Sri Lanka, Indonesia, and India rising substantially between December 2024 and July 2025, and with outlooks pointing toward sustained tightness into 2026, manufacturers and buyers must navigate a procurement environment where feedstock cost volatility becomes a structural consideration rather than an intermittent disruption. This dynamic elevates the strategic importance of long-term supply agreements, diversified sourcing portfolios, and transparency into feedstock origin and pricing linkage.
The second force is regulatory and compliance-driven demand. Stricter environmental standards in water treatment and air purification continue to reinforce consistent demand for coconut shell activated carbon across the United States and other major markets. As purity thresholds rise and end-use industries face more rigorous discharge, emission, and filtration specifications, the premium attached to highly pure, low-ash, and consistently performing grades becomes a decisive purchasing criterion. Buyers are increasingly prioritizing certification alignment, batch reproducibility, and technical support over lowest-cost procurement, especially in applications where adsorption failure carries regulatory or operational risk.
The third force involves geopolitical and tariff-related cost pressure. Increased U.S. tariffs on imported raw materials, including coconut shell charcoal and processing equipment, have raised production costs for certain market participants and prompted a broader reassessment of regional sourcing, reshoring considerations, and supply chain configuration. For buyers and manufacturers alike, these shifts introduce new complexity into cost modeling and capacity planning. Organizations that map tariff exposure, identify alternative sourcing corridors, and evaluate total landed cost across procurement scenarios will be better positioned to protect margins while maintaining supply continuity.
Finally, the interplay between capacity expansions, automation investments, and pricing actions is reshaping competitive expectations. The market is witnessing a phase where producers are simultaneously pursuing volume growth, quality consistency, and cost recovery. Price increases from major suppliers, coupled with rising import price benchmarks, indicate that the era of flat or declining input costs has transitioned into a period of structural price normalization. In this environment, strategic advantage will accrue to organizations that integrate market intelligence into procurement timing, inventory strategy, product mix optimization, and supplier diversification.
Worldwide Natural Coconut Activated Carbon Market
How to Use This Report for 2026 Strategic Decision-Making
The study is organized to support multiple decision pathways. Procurement and supply chain leaders can use the segmentation and competitive profiles to benchmark supplier capabilities, identify sourcing vulnerabilities, and evaluate alternatives in granular, powdered, and extruded or pelletized formats. Product and R&D teams can align purity and pore-structure requirements with application-specific demand signals, particularly in water and wastewater treatment, gold recovery, food and beverage processing, pharmaceuticals and medical applications, and emerging semiconductor and supercapacitor uses. Strategy and corporate development teams can leverage the competitive concentration data, recent capacity expansions, and pricing developments to assess market entry feasibility, partnership opportunities, and investment timing.
Because the report deliberately integrates historical performance, forward forecasts, and current market-moving events, it functions as both a diagnostic tool and a planning framework. Decision-makers can use it to validate internal assumptions, stress-test sourcing strategies against raw material and tariff scenarios, and prioritize where to allocate analytical resources for the remainder of the planning cycle. The depth of company profiling, combined with the market-level trajectory and segmentation context, ensures that users can move from broad market recognition to targeted, evidence-based action.
Access the Full Intelligence Suite
This overview provides a strategic snapshot of the forces defining the highly pure coconut shell activated carbon market and why 2026 represents a pivotal planning year. The complete Worldwide Highly Pure Coconut Shell Activated Carbon Market research extends far beyond this summary, delivering the detailed segmentation performance, competitive benchmarking, regional demand context, pricing analysis, and forward forecasts required to execute with precision. To secure the full dataset, company profiles, and actionable market forecasts that will inform your 2026 decisions, access the complete report through our source page. The intelligence contained within is designed to convert market complexity into strategic clarity, enabling your organization to anticipate shifts, capitalize on structural growth, and maintain competitive advantage in a rapidly evolving purification landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Highly Pure Coconut Shell Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com