

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Phenolic Foam Insulation Market to Reach $2,368 Million by 2032 at 5.85% CAGR

Strategic Horizons: Navigating the Global Phenolic Foam Insulation Sheet Market Through 2032
In an era where energy efficiency and fire safety mandates are reshaping the built environment, phenolic foam insulation has emerged as a critical material class. As we enter 2026, the strategic importance of understanding market trajectories cannot be overstated. The evolution from 2020 to the forecasted landscape of 2032 presents a complex narrative of recovery, technological advancement, and regulatory shifts. This article serves as a strategic prelude to our comprehensive Worldwide Phenolic Foam Insulation Sheet Market research, designed to equip decision-makers with the foundational intelligence required to navigate the coming years. The clock is ticking on decarbonization targets and retrofit mandates; understanding who leads, where growth concentrates, and what risks lie ahead is no longer optional—it is a prerequisite for resilient capital allocation.
Macro Trajectory: Growth, Resilience, and the 2026 Baseline
The historical performance of the phenolic foam insulation sheet market reveals a sector defined by robust demand drivers despite periodic supply chain volatility. Reflecting on the baseline year of 2025, the market commanded a significant revenue position compared to its 2020 starting point. The compound annual growth rate of 5.85% over the forecast period from 2026 to 2032 signals sustained expansion, though the path is nuanced. Early in the decade, the market navigated the post-pandemic industrial reactivation, with revenue climbing steadily through 2022 before encountering macroeconomic headwinds in 2024. Yet, the resilience of the sector is evident in the rebound observed in 2025 and the projected trajectory moving forward.
Phenolic Foam Board Market
Looking ahead to the 2026-2032 horizon, the aggregate market valuation is poised to scale new heights. By the end of the forecast period in 2032, the global revenue is expected to reach over 2300 million USD. This growth is not merely a reflection of broader economic recovery but is structurally underpinned by the increasing penetration of phenolic foam in high-performance building envelopes and industrial thermal management. The baseline figures for 2026 establish a pivotal moment for stakeholders. The incremental growth observed from the 2025 base indicates that while immediate post-recession surges have stabilized, the underlying demand fundamentals remain intact. For corporate strategists, this trajectory suggests that scaling capacity or securing supply chains in the near term could yield significant competitive advantages as the market matures toward the 2028-2030 acceleration phase. The data implies a shift from volatility to a more predictable, albeit competitive, growth pattern where market share defense becomes as critical as revenue generation.
Segmentation Intelligence: Product Types and Application Verticals
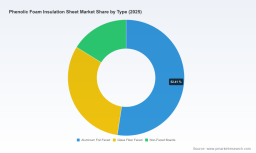
Deeper analysis of the market structure reveals distinct profitability and volume drivers that vary significantly across product types, applications, and geographies. The landscape is dominated by specialized variants that cater to rigorous performance standards, with aluminum foil faced boards representing the largest revenue share among product categories. This dominance is driven by the material's enhanced moisture barrier properties and ease of integration into HVAC and roofing systems, making it the preferred choice for contractors seeking comprehensive thermal and vapor solutions. Glass fiber faced boards occupy a substantial secondary position, valued for their mechanical strength and specific fire-retardant characteristics in applications where foil facing may be less suitable. Non-faced boards, while representing a smaller portion of the revenue mix, serve niche requirements where direct adhesion or specific finishing processes are prioritized. The choice between these types often hinges on regional building codes, end-user specifications, and the specific thermal conductivity requirements of the project.
On the application front, HVAC ductwork stands as the primary consumption vertical. The relentless push for energy-efficient building operations and the retrofitting of aging infrastructure drive consistent demand for duct insulation that minimizes thermal loss and condensation risk. Roofing and wall insulation follow closely, benefiting from stringent energy codes and the broader trend toward high-performance building envelopes. The structural integrity and fire resistance of phenolic foam make it particularly attractive in these applications, where safety and long-term performance are paramount. Pipe and industrial insulation, while contributing a smaller share of the total revenue, represents a critical segment for process industries and district heating networks. Here, the focus is on durability and corrosion resistance under harsh operating conditions. Understanding the interplay between these segments is vital; a slowdown in construction activity may be offset by sustained industrial maintenance spending, and vice versa. The report delves into these cross-segment dynamics, illuminating where volume growth is likely to outpace margin expansion and where premium pricing strategies can be sustained.
Competitive Landscape: Market Concentration and Key Players
The global phenolic foam insulation sheet market is characterized by a moderately concentrated competitive structure. The top three players collectively account for approximately 36.45% of the market revenue, while the top five extend their grip to nearly half of the total market share at 49.2%. This concentration indicates that while large multinational corporations hold significant sway, there remains ample room for regional specialists and niche fabricators to compete on service, customization, and local responsiveness. The presence of diversified chemical giants alongside specialized insulation manufacturers creates a dynamic ecosystem where raw material sourcing advantages can translate directly into downstream market power.
Kingspan Insulation, headquartered in Ireland, remains a towering figure in this space. As the primary UK and major European producer, Kingspan's Kooltherm range of closed-cell phenolic foam boards sets a benchmark for thermal efficiency and fire resistance. Their global footprint and continuous investment in R&D allow them to command premium positioning in both building and industrial segments. Similarly, Unilin, operating under the Xtratherm brand, reinforces the strong European presence with rigid phenolic sheets designed for energy-efficient building envelopes. Both entities leverage established distribution networks and brand reputation to maintain high barriers to entry in their core markets.
From the Asian manufacturing hub, Jinan Shengquan Group and Fujian Tenlead Advanced Materials represent significant production capacity. Shengquan's specialization in phenolic foam panels and advanced chemical materials supports a wide range of construction and industrial applications worldwide. Tenlead's focus on boards, blocks, and pipe sections, including Therma-Phen type products, underscores the versatility of Chinese manufacturers in supplying both standard and customized solutions. Guibao further adds to this regional density, catering primarily to construction insulation needs. These players often compete on scale and cost efficiency, making them formidable partners or rivals depending on the procurement strategy. In Japan, Asahi Kasei and Sekisui Chemical bring global chemical expertise to the insulation sector. Asahi Kasei's focus on high-performance thermal and fire-resistant applications aligns with stringent building standards, while Sekisui emphasizes durability and insulation properties. Their involvement often signals a higher tier of material science integration and quality assurance.
Worldwide Phenolic Foam Insulation Sheet Market
The competitive field also includes specialized fabricators and regional manufacturers that add granularity to the supply chain. LG Hausys (LX Hausys) from South Korea produces boards and panels that emphasize fire safety and thermal performance, targeting both construction and HVAC markets. In the United States, General Insulation Company and Resolco, Inc. play crucial roles in the fabrication of custom sheets, buns, pipe coverings, and equipment insulation. General Insulation's capability to fabricate from high-density closed-cell rigid foam allows for tailored solutions in thermal applications, while Resolco's Insul-Phen line emphasizes fire safety for pipe and equipment, addressing critical industrial compliance needs. MW Insulation in the United Kingdom operates as an independent fabricator, supplying Supaphen products with various factory-applied finishes, offering flexibility that larger integrated producers may not always match. In the Middle East, Gulf Cool Therm and SAT Insulation Materials Industry L.L.C. focus on rigid, environmentally compliant phenolic foam sheets and pre-insulated panels, catering to the region's rapid infrastructure development and cooling demands. Autex Industries in New Zealand, with its GreenStuf brand, brings a focus on foil-faced boards for thermal and moisture resistance, serving the Oceania market with localized production. Finally, Prefere Resins in Germany occupies a vital upstream position, supplying phenolic foam resins that feed into the production of insulation foams. This resin supply chain link is critical, as access to high-quality, cost-effective resins can determine the manufacturing economics for downstream foam producers. BASF recently entered the conversation with a March 2025 product launch of a new bio-based phenolic resin line, aiming to support phenolic foam insulation production with an improved sustainability profile. This move highlights a growing trend where raw material suppliers are innovating to help downstream manufacturers meet carbon reduction targets and enhance the green credentials of their final products.
Regulatory and Raw Material Dynamics: The 2026 Reality Check
Strategic planning in 2026 must account for a tightening regulatory environment and volatile input costs. Formaldehyde emissions regulations, including California's CARB ATCM and the EU's REACH framework, impose strict requirements on low-emission formulations. Manufacturers must ensure their phenolic foam insulation products address indoor air quality concerns to maintain market access in key regions. Compliance is not merely a legal checkbox; it is a competitive differentiator that can unlock procurement contracts in sensitive environments such as schools, hospitals, and high-end residential projects.
Simultaneously, fire safety standards continue to drive adoption. Phenolic foam's ability to achieve high ratings such as Euroclass B-s1,d0, BS 476 Class 0, and ASTM E-84 Class A supports its use under building codes that emphasize fire resistance. The EN 14314 standard further specifies requirements for factory-made phenolic foam thermal insulation products for building equipment and industrial installations, providing a clear technical framework for quality and performance. Adherence to these standards reduces liability and enhances the value proposition of phenolic foam over alternative materials that may struggle to meet equivalent fire performance criteria.
On the cost side, raw material dynamics present both challenges and opportunities for margin management. In March 2026, phenolic resin prices were recorded at approximately 1,790 USD per metric ton FOB China and 1,877 USD per metric ton CIF USA, directly impacting production costs as the primary feedstock. Earlier in the cycle, phenol-formaldehyde resin prices in the USA reached roughly 1,715 USD per metric ton in Q3 2025, with volatility tied to benzene and methanol feedstock costs. This input price pressure affects phenolic foam sheet manufacturing margins and necessitates strategic hedging or long-term supply agreements. Companies that can secure stable resin supplies or pass through costs effectively will maintain healthier profitability profiles than those exposed to spot market fluctuations. The interplay between resin pricing, energy costs, and freight rates creates a complex cost structure that requires sophisticated procurement strategies and potentially regionalized production footprints to mitigate risk.
Strategic Imperatives for 2026 and Beyond
As organizations formulate their strategies for the remainder of this decade, several imperatives emerge from the current market intelligence. First, the concentration of revenue in aluminum foil faced products and HVAC applications suggests that innovation in these high-volume segments should be prioritized. Enhancing moisture resistance, improving ease of installation, and developing integrated solutions can capture additional market share. Second, the presence of strong regional players in Asia and the Middle East indicates that global expansion strategies must be localized. Understanding regional building codes, preference for specific face types, and logistical constraints is essential for success in markets like Europe and Asia Pacific, where the largest revenue concentrations exist. Third, the push towards sustainability, exemplified by developments like bio-based resins, offers a pathway to differentiate products and appeal to eco-conscious buyers. Investing in sustainable formulations or partnering with resin innovators can future-proof product portfolios against tightening environmental regulations. Fourth, the fragmentation below the top five players suggests that M&A activity or strategic partnerships could be viable routes to scale. Acquiring regional fabricators with strong local service networks or forming alliances with chemical suppliers can accelerate growth and improve supply chain resilience. Finally, risk management regarding raw material volatility and regulatory compliance must be embedded in operational planning. Building flexibility into supply chains and maintaining rigorous quality assurance to meet standards like EN 14314 and fire ratings will protect brand reputation and ensure uninterrupted market participation. The market is moving toward a phase where efficiency, compliance, and sustainability converge. Companies that align their capabilities with these trends will be best positioned to capture the value projected in the forecast period. The insights presented here merely scratch the surface of the opportunities and risks inherent in this evolving landscape.
Unlocking the Full Intelligence Framework
This overview provides a strategic foundation, but the depth of actionable intelligence required for precise decision-making extends far beyond aggregate trends and company profiles. To truly capitalize on the market trajectory through 2032, stakeholders need granular visibility into volume-to-value conversions, detailed regional growth vectors, and specific application-level demand forecasts. The complete research deliverable offers a multi-layered analysis that dissects the market by region, type, and application with precise segmentation splits, historical data normalization, and scenario-based forecasting. It includes exhaustive company profiling that goes beyond public summaries to analyze market positioning, capacity expansions, and strategic moves. Furthermore, the full report incorporates comprehensive data tables, supply chain mapping, and competitive benchmarking tools that enable quantitative modeling and risk assessment. Access to this level of detail allows procurement teams to benchmark costs, sales leaders to identify untapped geographies, and R&D divisions to align product roadmaps with emerging regulatory and 성능 requirements. The macroeconomic indicators and segmentation data discussed here are anchors within a much larger dataset that reveals the subtle shifts in market share, the impact of local manufacturing initiatives, and the nuanced demand patterns across HVAC, roofing, and industrial verticals.
For boards, investors, and strategy teams, the difference between a good decision and a great one often lies in the granularity of the underlying intelligence. The 5.85% CAGR and the projected revenue scale to 2032 are compelling, but understanding the drivers behind the regional balances, the margins within specific product segments, and the timing of capacity additions requires the full analytical framework. We invite you to explore the complete Worldwide Phenolic Foam Insulation Sheet Market research to secure the comprehensive data, detailed segmentation insights, and strategic recommendations necessary to navigate the complexities of this dynamic market. The insights awaiting in the full report will transform high-level awareness into executable strategy, ensuring your organization is not just observing the market evolution but actively shaping its outcome in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Foam Insulation Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com