

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Ultrasonic Scissor Market to Reach $2.26B by 2032 at 6.5% CAGR

Strategic Intelligence for the Ultrasonic Scissor Market: Navigating Growth and Change Through 2032
The global surgical landscape is undergoing a profound transformation, driven by the accelerating adoption of minimally invasive techniques and the continuous refinement of energy-based surgical platforms. Within this evolving ecosystem, the ultrasonic scissor segment stands out as a critical enabler of surgical precision, tissue preservation, and procedural efficiency. As healthcare systems worldwide confront rising procedural volumes, cost containment pressures, and an expanding roster of clinical indications, executives across medical device manufacturers, hospital procurement leaders, and strategic investors require a clear, forward-looking view of market trajectories. This comprehensive Worldwide Ultrasonic Scissor Market research study is positioned to serve as that strategic compass, translating macroeconomic trends, competitive movements, and regulatory shifts into actionable intelligence for 2026 and beyond.
Understanding where the market is heading requires more than tracking headline growth figures. It demands a disciplined examination of demand drivers, product architecture evolution, regional purchasing dynamics, and the strategic calculus of entrenched incumbents and emerging challengers. The analysis that follows distills these layers into a structured, decision-ready framework. Rather than offering static snapshots, the report maps the interplay between clinical advancement, manufacturing scale, and market access pathways, equipping leadership teams with the contextual depth required to allocate capital, shape product roadmaps, and anticipate competitive responses with confidence.
Market Trajectory and the Architecture of Growth
Over the past half-decade, the ultrasonic scissor market has demonstrated a steady, structurally supported expansion. Total global revenue scaled from approximately $1,050.5 million in 2020 to an estimated $1,452.5 million in 2025, reflecting a composite annual growth pattern shaped by surgical volume recovery, technology adoption cycles, and broadening clinical utilization. Looking ahead through the 2026–2032 forecast horizon, the market is projected to continue its upward arc, reaching an estimated $2,257.2 million by the close of the period. This trajectory corresponds to a forecast compound annual growth rate of 6.5 percent, signaling a market that is maturing but still capable of generating meaningful incremental value for participants who align their strategies with underlying demand fundamentals.
Several interconnected forces underpin this growth profile. The continued migration of general, gynecologic, urologic, and specialized surgical procedures toward minimally invasive and laparoscopic approaches favors advanced energy instruments that offer controlled transection, reliable hemostasis, and ergonomic integration within constrained operative fields. Simultaneously, hospital systems and ambulatory surgical centers are increasingly prioritizing instrument durability, reprocessing economics, and single-use architectures as part of broader supply chain optimization initiatives. These operational considerations, combined with surgeon familiarity and training pathways, create a durable pull for ultrasonic scissor platforms across both established and emerging clinical settings.
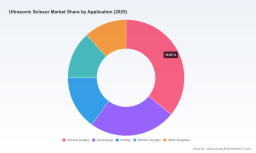
Importantly, the growth environment is not uniformly distributed across all product architectures or clinical applications. The market reflects a segmented demand landscape in which handheld surgical devices and generator- or console-based systems serve distinct workflow requirements, while procedural specialties such as general surgery, gynecology, urology, and bariatric applications each present differentiated adoption curves. Understanding how these segments interact, where substitution risk exists, and which configuration aligns with specific care delivery models is essential for any organization seeking to capture sustainable share. The full report unpacks these structural nuances without reducing them to simplistic abstractions, enabling readers to assess where strategic emphasis will yield the highest return.
What the Report Delivers: Analytical Depth and Operational Utility
A market study gains strategic value only when it translates observation into execution. This research is designed from the ground up to support that transition. Rather than limiting itself to high-level revenue tables, the report assembles a multidimensional view of the ultrasonic scissor market, covering historical context, forward-looking projections, competitive positioning, and the operational levers that shape commercial outcomes. Each analytical layer is intended to inform discrete decision points, whether a manufacturer is evaluating product pipeline prioritization, a distributor is assessing regional entry timing, or a healthcare organization is benchmarking instrument adoption against clinical and financial objectives.
The analysis draws on a broad set of structured inputs, spanning market sizing across multiple time horizons, segmentation by product type and application, regional demand characterization, and market concentration metrics that illuminate the balance between incumbent dominance and emerging competitive pressure. In parallel, the report integrates qualitative intelligence on product innovation, regulatory activity, and strategic developments that influence near-term momentum. By combining quantitative structure with contextual narrative, the study enables leadership teams to move beyond static benchmarks and toward scenario-based planning.
Readers will find practical value in several areas of focus. First, the report clarifies how historical demand patterns through the base year connect to the forward forecast window, helping stakeholders distinguish cyclical fluctuations from structural shifts. Second, it examines segmentation dynamics in a way that supports product architecture decisions, pricing strategy, and channel planning, without relying on oversimplified assumptions about uniform adoption. Third, it situates regulatory activity and recent product introductions within the broader competitive landscape, offering insight into how market access timelines and device classifications can accelerate or constrain commercialization pathways. Together, these elements create a working framework that can be adapted to internal strategy sessions, investment committees, and operational planning cycles.
Competitive Landscape and Strategic Positioning
The ultrasonic scissor market is characterized by a mix of globally established medical technology firms and increasingly capable regional manufacturers. At the higher end of market concentration, the top three and top five participants collectively command a substantial share of total revenue, underscoring the strategic importance of brand equity, clinical evidence, distribution reach, and reprocessing or single-use economics. Yet the landscape is not static. New product introductions, regulatory clearances, and targeted expansion efforts continue to reshape the competitive perimeter, creating opportunities for companies that can execute on differentiation, supply chain reliability, and clinical workflow alignment.
Ultrasonic Dissector Market
Among the market’s prominent participants, Johnson & Johnson MedTech continues to leverage its HARMONIC platform, with instrument configurations such as the HARMONIC 1100 Shears and HARMONIC FOCUS+ Shears designed for precise ultrasonic dissection, vessel sealing up to 7 millimeters, and tissue transection across minimally invasive and open procedures. Medtronic maintains a strong presence through its Sonicision 7 Curved Jaw cordless ultrasonic dissection devices, which address vessel coagulation and dissection within the broader surgical energy category. Olympus Corporation contributes ultrasonic dissection and cutting instruments as part of its surgical energy portfolio, supporting endoscopic and laparoscopic workflows. Stryker Corporation participates through reprocessed HARMONIC shears and broader advanced energy offerings spanning general, pediatric, gynecologic, urologic, and thoracic applications. B. Braun Melsungen AG markets ultrasonic dissection devices within its surgical energy and minimally invasive surgery portfolio, reinforcing a comprehensive approach to procedural support.
Alongside these global players, a cohort of China-based manufacturers has been expanding its footprint with a focus on cost-competitive designs, regulatory filings, and incremental certification progress. Miconvey manufactures minimally invasive ultrasonic surgical instruments, including scissors-type ultrasonic scalpels, backed by CE, FDA, and ISO 13485 certifications. Ezisurg Medical develops the easyUS Ultrasonic Surgical System for hemostatic cutting and coagulation of soft tissues and vessels up to 5 millimeters. Reach Surgical, operating under Genesis MedTech, produces SR7 ultrasonic shears capable of sealing vessels up to 7 millimeters within an advanced energy platform that integrates ultrasonic and advanced bipolar modalities. BBT Medical specializes in scissors-type ultrasonic scalpels and harmonic scalpels for surgical applications, while Hunan Handlike Minimally Invasive Surgery Co., Ltd. offers disposable ultrasonic shears as part of its ultrasonic surgical system portfolio. These companies illustrate a broader industry trend in which regional manufacturing ecosystems are increasingly capable of contributing to global supply and product diversity, particularly as clinical and commercial requirements evolve.
Recent activity further highlights how product strategy and regulatory progress continue to shape the market’s direction. In December 2024, CMR Surgical launched an Ultrasonic Dissector for its Versius surgical robot, extending advanced energy cutting and coagulation capabilities into robotic-assisted procedures. Earlier in the same year, Genesis MedTech introduced SR7 ultrasonic shears designed to seal vessels up to 7 millimeters alongside an integrated advanced bipolar and ultrasonic energy platform. In June 2024, Hunan Handlike received FDA 510(k) clearance for its disposable ultrasonic shears within its ultrasonic surgical system, an action that not only advanced a specific product pathway but also reflected the broader regulatory framework governing ultrasonic surgical instruments under FDA product code LFL, where substantial equivalence review remains a central requirement for market access. These developments demonstrate how technological integration, platform expansion, and regulatory clearance cycles can create near-term momentum and alter competitive positioning.
Strategic Priorities for 2026 Decision-Makers
For organizations operating in or adjacent to the ultrasonic scissor market, the 2026 decision environment calls for disciplined attention to a handful of strategic priorities. First, product roadmap decisions should be anchored in clinical workflow realities rather than technology aspirations alone. The value proposition of ultrasonic shears lies in their ability to support reliable transection, vessel sealing, and tissue handling within the constraints of minimally invasive procedures, and future differentiation will increasingly depend on ergonomics, consistency, and integration with broader surgical ecosystems. Second, supply chain and instrument lifecycle strategy deserve renewed emphasis. The balance between reusable, reprocessed, and single-use formats carries implications for procurement economics, sterilization throughput, regulatory exposure, and surgeon preference, making it a central variable in commercial planning.
Worldwide Ultrasonic Scissor Market
Third, regional strategy must account for uneven adoption dynamics and varying procurement structures. Demand characteristics differ across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and the most effective go-to-market models will be those tailored to local clinical priorities, reimbursement realities, and distributor capabilities. Fourth, competitive positioning will increasingly hinge on evidence generation, regulatory alignment, and platform versatility. As advanced energy instruments become more closely associated with robotic-assisted workflows and integrated surgical platforms, manufacturers that can demonstrate predictable performance, efficient training pathways, and compatibility with evolving procedural standards will be better positioned to defend and expand share.
Finally, leadership teams should monitor the pace and pattern of regulatory activity, not only for compliance reasons but because clearance cycles and classification pathways can influence time-to-market, competitive entry windows, and the attractiveness of specific product configurations. The interplay between technical differentiation, market access, and procurement economics will shape which players capture durable advantage as the market expands through the end of the decade.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Ultrasonic Scissor Market research study is built to support exactly that kind of informed, forward-looking decision-making. By combining historical context, forecast structure, segmentation insight, competitive profiling, and recent market-moving events, the report gives executives a reliable foundation for evaluating where value is likely to be created and how to position accordingly. The numbers alone tell only part of the story; the strategic value lies in understanding the forces behind them and the commercial choices they demand.
For organizations preparing for 2026 and the years that follow, the ability to act on granular, up-to-date intelligence can make a meaningful difference in product investment timing, market entry decisions, pricing architecture, and competitive response. To access the full dataset, regional and segment-level breakdowns, and the complete competitive and regulatory analysis, readers are encouraged to explore the complete report at the source page. There, the deeper market intelligence becomes available in a form designed to support internal strategy sessions, investment evaluation, and operational planning with precision and confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Ultrasonic Scissor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com