

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Prescription Cat Food Market to Hit $9.67B by 2032 at 6.45% CAGR

Prescription Cat Food Market Outlook 2026: Strategic Intelligence for Veterinary and Pet Care Leaders
Executive Overview
The global prescription cat food market has entered a phase of disciplined expansion, driven by a convergence of rising feline health awareness, veterinary endorsement of therapeutic nutrition, and an increasingly sophisticated pet parent demographic. For senior executives navigating the pet care ecosystem, the 2026-2032 forecast period presents a critical window to refine product portfolios, optimize supply chain resilience, and align commercial strategies with emerging clinical demand. Our latest Worldwide Prescription Cat Food Market research offers a comprehensive, data-grounded view of this trajectory, translating macro trends into actionable intelligence for portfolio planning, competitive positioning, and regional expansion.
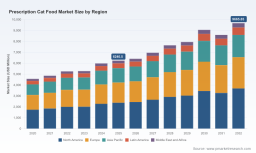
The market has demonstrated consistent upward momentum over the past half-decade, with historical performance reflecting both post-pandemic normalization and sustained clinical adoption of veterinary diets. Looking ahead, the projected compound annual growth rate of 6.45 percent through the end of the decade signals a market that is no longer dependent on cyclical novelty but is instead anchored in steady demand for condition-specific nutrition. Revenue is expected to surpass the nine-billion-dollar threshold by the early 2030s, a milestone that underscores both the commercial maturity of the segment and the strategic importance of anticipating shifts in feline health epidemiology, formulation preferences, and distribution dynamics.
For decision-makers, this growth narrative is not merely a top-line headline. It represents a structural shift in how therapeutic cat nutrition is developed, marketed, prescribed, and distributed. Veterinary clinics, specialty retailers, and direct-to-consumer channels are each evolving their engagement models, while manufacturers are balancing formulation innovation with cost pressures in raw materials and ingredient sourcing. The strategic value of our research lies in its ability to connect these intersecting forces into a coherent playbook for 2026 and beyond.
Market Trajectory and Growth Dynamics
The historical arc from 2020 through 2025 reveals a market that recovered quickly from early volatility and then accelerated through broadened clinical adoption and stronger retail execution. Total revenue expanded steadily across that period, with notable momentum in the most recent years as consumer education around feline health conditions intensified and veterinary practices continued to recommend condition-specific diets as part of comprehensive care plans. This foundation has positioned the market to transition into a higher-growth phase, though the trajectory is not uniform across every commercial dimension.
Forecasting through 2032 suggests a market that compounds at a rate consistent with mid-single-digit expansion, reflecting a balance between underlying demand growth and operational realities such as ingredient inflation, regulatory compliance, and competitive saturation in certain categories. The projected revenue pathway indicates that while the market will continue to scale, growth will be shaped by nuanced factors including palatability improvements, formulation efficacy, veterinary endorsement strength, and the ability of manufacturers to maintain price integrity amid varying cost environments.
For strategic planners, the growth outlook carries several implications. First, the market's durability suggests that long-term investment in therapeutic nutrition is warranted, but that growth will favor companies that can differentiate through clinical credibility, channel execution, and responsive product development. Second, the pace of expansion implies that capacity planning and supply chain agility will be critical, particularly as manufacturers seek to meet demand without compromising quality or margin structure. Third, the forecast period is likely to see intensified competition for veterinary trust and consumer attention, meaning that brand positioning must be supported by clear therapeutic value propositions and consistent commercial execution.
Competitive Landscape and Brand Positioning
The prescription cat food segment remains concentrated, with a small group of leading manufacturers commanding a substantial share of market revenue. This concentration reflects the category's reliance on veterinary validation, established clinical reputations, and deep relationships with veterinary practices and specialty distribution networks. The leadership positions are held by companies that have built multi-decade portfolios around condition-specific nutrition, investing in research, formulation science, and veterinary education to reinforce their authority in therapeutic pet care.
Hill's Pet Nutrition, headquartered in Topeka, Kansas, continues to reinforce its leadership through a broad Prescription Diet portfolio that spans kidney disease, urinary health, diabetes, and gastrointestinal support. The company's recent product activity illustrates its focus on expanding therapeutic reach while sustaining core category strength. In February 2024, Hill's launched Prescription Diet Derm Complete dry cat food for dermatology support, extending its capability into skin and coat-related conditions and broadening the clinical scenarios for which veterinarians can recommend its offerings.
Royal Canin, based in Aimargues, France, maintains a strong veterinary diet presence with targeted formulations for renal support, urinary care, gastrointestinal needs, and mobility. Its November 2023 update to Renal Support formulas, designed to enhance palatability for cats, highlights the competitive emphasis on acceptance and compliance. In therapeutic nutrition, formulation performance is only part of the equation; the ability to encourage consistent consumption is equally important, especially in chronic care scenarios where adherence directly influences outcomes and customer retention.
Nestlé Purina PetCare, with its St. Louis, Missouri base, continues to advance its Pro Plan Veterinary Diets line, which includes offerings such as HA Hydrolyzed for allergen management, UR Urinary support, NF Kidney Function, and OM Overweight Management. In May 2024, Purina released an updated Pro Plan Veterinary Diets cat food portfolio with refreshed packaging, a move that signals both brand renewal and a focus on shelf impact, consumer clarity, and veterinary practice familiarity. In a category where trust is cumulative, packaging and presentation can play a meaningful role in reinforcing recognition and easing purchase decisions within retail and clinic channels.
These three leaders represent a competitive core defined by broad clinical portfolios, sustained R&D activity, and established veterinary relationships. Yet the market's structure also invites strategic nuance. High concentration does not eliminate room for differentiation; rather, it elevates the importance of execution in specific health conditions, product forms, and regional channels. Companies that can align formulation innovation with strong veterinary communication, palatability performance, and channel-specific demand generation are better positioned to capture share within an otherwise mature competitive field.
Worldwide Prescription Cat Food Market
Segment Dynamics Across Health Conditions, Product Forms, and Regions
The prescription cat food market is defined by multiple overlapping segmentation dimensions, each with its own growth logic and commercial implications. The health condition landscape reflects the clinical needs that drive veterinary recommendations and consumer purchases. Urinary health represents a major demand center, consistent with the prevalence of lower urinary tract concerns in feline medicine and the long-standing role of prescription diets in managing urinary pH, crystal formation, and hydration-related risk factors. Renal support is another substantial pillar, reflecting the importance of nutritional management in chronic kidney disease, a condition that remains highly relevant in aging feline populations. Weight management continues to draw attention as pet obesity and its downstream health implications gain recognition among both veterinarians and owners. Digestive care forms a meaningful segment as gastrointestinal sensitivities, food intolerances, and microbiome-focused nutrition become more prominent in clinical conversations. Diabetes and other condition-specific categories round out the demand picture, underscoring the breadth of therapeutic applications that contribute to overall market scale.
Product form introduces an additional strategic layer. Dry food constitutes the largest share of revenue, shaped by its convenience, shelf stability, and compatibility with routine feeding practices. Wet food holds a significant position as well, driven by its hydration benefits, higher moisture content, and appeal in cases where increased water intake is clinically desirable. Therapeutic treats represent a smaller but increasingly relevant category, often used as adjuncts for compliance, reward-based feeding, or targeted nutritional supplementation. The interplay among these forms matters because consumer preference, veterinary recommendation, and condition-specific requirements do not always align neatly. Manufacturers that can offer coherent cross-form solutions, or that can optimize one format for a specific clinical use case, may gain advantage in both practice recommendation and consumer adoption.
Regional dynamics further shape the market's competitive rhythm. North America and Europe represent substantial demand bases, supported by mature veterinary infrastructure, high pet humanization, and established prescription diet channels. Asia Pacific reflects a growing opportunity set as pet care markets expand, veterinary services modernize, and awareness of therapeutic nutrition increases. Latin America and the Middle East and Africa contribute additional demand, with growth influenced by local pet ownership trends, import and distribution frameworks, and the pace of veterinary market development. Rather than viewing these regions as uniform blocks, successful strategy requires attention to local clinical practices, channel structures, regulatory expectations, and consumer purchasing behavior. The market's breadth across regions means that a single global approach is rarely sufficient; instead, portfolio allocation and go-to-market execution must be calibrated to regional realities.
Regulatory, Supply Chain, and Operational Considerations
The prescription cat food category operates within a regulatory and operational environment that directly affects product development, labeling, marketing claims, and market access. Pet foods must comply with AAFCO nutrient profiles for complete and balanced diets, and prescription diets require veterinary substantiation. This framework reinforces the category's clinical orientation but also raises the bar for evidence support, claim discipline, and professional credibility. In practical terms, it means that product strategies must be grounded in documented nutritional rationale and that communication must be aligned with veterinary expectations. Regulatory clarity is an asset for established players, but it also creates a higher threshold for entry and differentiation for newer formulations or niche indications.
Labeling requirements add another layer of compliance discipline. FDA requirements for nutritional adequacy statements on pet food labels under 21 CFR 501.13 reinforce the importance of accurate representation and consistent quality assurance. For therapeutic products, this is especially relevant because clinicians and consumers rely on label information to make feeding decisions and to evaluate suitability for specific conditions. Companies that maintain rigorous documentation, transparent communication, and strong quality systems are better positioned to navigate these expectations while preserving brand trust.
On the supply side, ingredient dynamics remain a key operational consideration. Chicken meal prices rose 8 percent year-over-year to $1,450 per metric ton due to feed cost increases, illustrating the ongoing pressure that raw material volatility can place on formulation economics and margin management. In a category where nutritional integrity and consistent quality are non-negotiable, cost optimization cannot come at the expense of ingredient standards. This environment favors manufacturers with diversified sourcing strategies, forward-looking procurement planning, and formulation flexibility that can adapt to input cost shifts without compromising clinical performance.
Trade and market access requirements also influence regional strategy. EU Regulation (EC) No 183/2005 mandates registration of pet food establishments for imports, which affects cross-border distribution and the operational footprint required to serve European markets effectively. In parallel, recall surveillance remains a critical reputational and compliance factor. No active recalls were reported for major prescription cat food brands as of the first quarter of 2026, a positive signal for the segment's quality and process control. Maintaining that track record is essential, because even a single high-profile disruption can affect veterinary confidence, retail execution, and consumer trust across a category that depends heavily on perceived safety and clinical reliability.
Portfolio Strategy and Decision-Making for 2026
For executives planning across 2026 and the broader forecast window, the prescription cat food market rewards strategies that integrate clinical relevance, commercial discipline, and operational resilience. The most effective portfolio decisions will be informed by a clear understanding of where therapeutic demand is stable, where it is expanding, and where competitive intensity requires sharper differentiation. This means looking beyond aggregate growth and paying close attention to the relative strength of health condition segments, the adoption patterns across product forms, and the channel-specific dynamics that shape prescription diet sales.
Several strategic priorities emerge from the current environment. First, condition-specific innovation should be guided by both clinical need and practical adoption. Formulations that address meaningful health concerns are necessary but not sufficient; they must also perform well in terms of palatability, ease of recommendation, and consistency of use. Second, brand execution should reinforce veterinary trust. Given the category's reliance on professional endorsement, educational support, practice relationships, and clear therapeutic positioning can be as important as the product itself. Third, supply chain and cost management deserve active attention. Ingredient price movements, sourcing continuity, and manufacturing efficiency will influence margin outcomes and the ability to sustain competitive pricing without sacrificing quality.
Regional expansion and channel strategy also require tailored thinking. In mature markets, growth may come more from share dynamics, portfolio depth, and veterinary engagement than from broad category expansion. In faster-developing markets, the opportunity may lie in building awareness, strengthening distribution, and aligning product offerings with local clinical and consumer realities. Across all regions, the ability to translate global formulation expertise into locally relevant execution will be a defining capability.
The strategic question for 2026 is not simply whether the prescription cat food market will grow, but how companies will position themselves to capture value within that growth. This requires a view that connects market scale with segmentation logic, competitive behavior, regulatory expectations, and operational constraints. Companies that treat the category as a clinically anchored, commercially complex environment are more likely to build durable advantage than those that approach it as a routine pet food segment.
What's Inside the Report
Our Worldwide Prescription Cat Food Market research is designed to support decision-making at multiple levels, from corporate strategy and portfolio planning to competitive intelligence and regional execution. The report provides a structured analysis of historical performance and forward-looking demand, with a focus on the factors that will shape revenue, share, and competitive dynamics through 2032. It examines the market through the lenses of health condition, product form, and regional distribution, helping readers understand where demand is concentrated and how growth is likely to unfold across different commercial dimensions.
The report also includes a detailed competitive assessment of leading manufacturers, with attention to product positioning, therapeutic coverage, recent product activity, and the strategic implications of brand portfolio choices. By situating each major player within the broader market context, the analysis helps identify where concentration is highest, where differentiation matters most, and how recent launches, formula updates, and portfolio revisions may influence future competition. This competitive view is complemented by a discussion of market structure and concentration dynamics, offering context for assessing barrier levels, share mobility, and the strategic value of veterinary relationships and channel access.
In addition, the research integrates operational and regulatory considerations that affect formulation, labeling, distribution, and market entry. Topics such as nutritional adequacy requirements, veterinary substantiation expectations, ingredient cost trends, import registration requirements, and recall surveillance are addressed as part of the wider market environment. These elements are not treated as background only; they are linked directly to strategic implications for product development, cost planning, compliance readiness, and regional expansion. The report also includes practical guidance-oriented sections that help translate findings into planning assumptions, scenario thinking, and competitive response options.
Importantly, the report is structured to support both high-level strategic assessment and more detailed commercial analysis. Readers will find macro-level market trajectory, segmentation context, and competitive positioning, along with the kind of structured intelligence that can inform product roadmaps, channel strategy, and regional prioritization. The objective is to provide a credible, evidence-based foundation for decisions rather than a superficial trend summary.
How to Use This Intelligence
This research is most valuable when used as a decision-support tool rather than a static reference. For portfolio leaders, it offers context for evaluating which health conditions and product forms warrant continued investment, extension, or repositioning. For competitive strategy teams, it provides a framework for interpreting market concentration, brand differentiation, and the likely impact of recent product actions by leading manufacturers. For commercial and regional teams, it supports calibration of demand expectations, channel focus, and market-access planning in environments where regulatory and supply conditions vary.
The report is also intended to be read alongside internal data and operational knowledge. Market-level findings are most powerful when combined with company-specific sales patterns, veterinary feedback, formulation capabilities, and regional execution realities. Used in that way, the research helps clarify where external trends reinforce internal assumptions and where they suggest the need to revisit planning premises.
Conclusion
The worldwide prescription cat food market is entering a period in which growth is supported by strong clinical foundations, evolving consumer expectations, and sustained veterinary engagement, but is also shaped by competitive concentration, ingredient cost pressures, and regulatory discipline. The companies that navigate this environment successfully will be those that treat therapeutic nutrition as a strategically serious category, investing in clinical credibility, product performance, supply resilience, and channel-specific execution.
Worldwide Prescription Diet Pet Food Market
Our Worldwide Prescription Cat Food Market research provides the depth, structure, and forward-looking perspective needed to make those decisions with confidence. For leaders seeking a detailed view of segmentation dynamics, competitive positioning, regional growth patterns, and the operational factors that influence profitability and market access, the full report offers the complete intelligence foundation for 2026 planning and the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Cat Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com