

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3D Scanning Wind Lidar Market Hits $145M in 2025, Projected 7.85% CAGR to 2032

Strategic Intelligence for the Wind Energy Transition: Inside the Worldwide 3D Scanning Wind Lidar Market
The global transition toward renewable energy infrastructure is no longer a question of ambition, but of precision. As wind farm developers, engineering firms, and meteorological agencies navigate increasingly complex site conditions, the demand for high-fidelity atmospheric data has elevated 3D scanning wind lidar from a niche research tool to a critical asset in project lifecycle management. Our latest Worldwide 3D Scanning Wind Lidar Market report provides a comprehensive strategic roadmap for executives, investors, and technology leaders preparing for the 2026 to 2032 forecast horizon. This article outlines the core dynamics shaping the sector, demonstrates the analytical depth of our research, and illustrates how the full report can directly inform capital allocation, product positioning, and competitive intelligence decisions.
The Macro Trajectory: Sustained Growth Anchored by Measurement Precision
The market has demonstrated consistent expansion across the historical review period, with total revenue climbing from $105.0 million in 2020 to $145.0 million by 2025. This trajectory reflects a broader industry shift toward data-driven site selection, reduced measurement uncertainty, and accelerated permitting timelines. Looking ahead, the forecast period through 2032 positions the market for continued expansion, with projected valuations scaling past $246 million by the end of the cycle. The compound annual growth rate of 7.85% underscores a structural rather than cyclical growth pattern, driven by sustained capital deployment in onshore and offshore wind development, tighter regulatory expectations for resource validation, and the maturation of scanning lidar hardware that now delivers repeatable, high-resolution wind field mapping.
Wind Lidar Market
For enterprise decision-makers, these figures are more than historical markers or projection lines. They represent the commercial envelope within which product roadmaps, partnership strategies, and regional entry plans must be calibrated. Understanding where volume concentrates, how pricing architectures evolve, and which deployment models are gaining operational traction will determine whether organizations can capture margin expansion or remain exposed to commoditization pressure.
Segmentation Realities Shaping Commercial Strategy
The commercial landscape of 3D scanning wind lidar is defined by three structural dimensions that collectively dictate procurement behavior, engineering requirements, and sales motion design. Each dimension carries distinct adoption drivers, performance thresholds, and integration challenges that separate early movers from late followers.
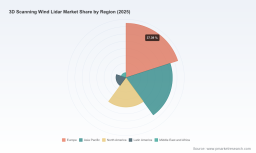
- Regional demand architectures: Market volume is distributed across mature wind markets with established measurement protocols and emerging development corridors where site characterization is accelerating. Procurement patterns differ materially by region, reflecting variations in regulatory frameworks, grid interconnection timelines, local content expectations, and the maturity of service ecosystems. Strategic positioning requires more than top-line allocation awareness; it demands insight into which territories are transitioning from pilot deployments to standardized multi-unit rollouts.
- Deployment model divergence: Ground-based scanning configurations dominate operational practice by a significant margin, reflecting their versatility in complex terrain, flexibility in campaign design, and compatibility with multi-season measurement requirements. Complementary deployment forms, including nacelle-integrated and buoy-mounted architectures, address specialized use cases where continuous turbine-adjacent measurement or offshore platform constraints demand alternative form factors. The interaction between these deployment categories shapes service contracts, calibration cycles, and the value proposition of hybrid measurement campaigns.
- Application-driven purchasing logic: Resource assessment remains the foundational demand driver, as developers require defensible wind field characterization to secure financing and optimize turbine layout. Operations-focused deployments are expanding as operators seek condition-aware performance monitoring and wake interaction insights. Meteorological research applications contribute a specialized but technically demanding demand layer, often setting the benchmark for accuracy, data density, and long-term reliability that commercial buyers subsequently expect.
These segmentation dynamics cannot be interpreted in isolation. The interplay between regional procurement cycles, deployment configuration preferences, and application-specific certification expectations creates a matrix of opportunity that rewards firms with modular product strategies, clear use-case positioning, and localized technical support capabilities.
Competitive Landscape: Differentiated Capabilities in a Consolidating Field
Market concentration metrics indicate a moderately consolidated environment, where a defined group of established manufacturers holds a substantial share of revenue, yet meaningful differentiation remains possible through measurement architecture, software integration, and campaign-level service design. The strategic implications for both incumbents and entrants hinge on how value is captured across hardware, validation, and downstream data services.
Several organizations define the current competitive frontier through distinct technical and commercial positioning:
- Vaisala continues to anchor its offering around the WindCube Scan series, emphasizing dual scanning capabilities for 3D wind field measurement, resource assessment, and offshore wind campaigns. Its recent product update focused on improved performance for wind energy and meteorological applications, reinforcing a strategy centered on measurement reliability and cross-sector applicability.
- ZX Lidars has built a reputation around ground-based scanning systems such as the ZX 300 series for accurate remote wind measurements. Its September 2025 launch of the ZX 300e ground-based wind lidar system, with IEC classification up to 200 metres following independent testing, illustrates the growing commercial weight of standardized validation and the competitive advantage of documented compliance.
- Movelaser contributes a programmable scanning approach through its Molas 3D Scanning Wind LiDAR System, targeting high-accuracy wind measurements in wind energy and adjacent applications. The emphasis on configurable scanning modes reflects a market preference for adaptability across terrain types and campaign objectives.
- Halo Photonics, now part of Lumibird , develops coherent pulsed Doppler wind lidar systems, including the Streamline series, suitable for profiling and scanning applications. Its technical lineage in Doppler measurement continues to influence expectations for signal quality and atmospheric sensitivity.
- ZATA offers the VWL 3D Scanning Doppler LiDAR for atmospheric wind profile measurement, leveraging pulse laser Doppler shift techniques. Its presence highlights the broader ecosystem of providers addressing atmospheric monitoring and wind profiling with specialized optical architectures.
- Leonardo provides the SKIRON3D high-end Doppler lidar system designed for 3D wind shear, gust, and turbulence monitoring, with applications spanning aviation and potential wind energy hazard detection. This high-performance positioning demonstrates how scanning lidar influence extends beyond pure resource assessment into safety-critical and hazard-aware operational contexts.
- Windar Photonics focuses on nacelle-mounted and scanning lidar solutions tailored to wind energy applications, illustrating how deployment-specific design is becoming an increasingly visible competitive axis.
The strategic question for market participants is not simply who leads today, but which capability bundles will define purchasing preference in 2027 and beyond. Product performance, certification readiness, calibration logistics, software interoperability, and service responsiveness collectively determine whether a vendor is viewed as a measurement instrument supplier or a partner in de-risking project development.
Industry Dynamics: Validation, Offshore Expansion, and Component Evolution
Three concurrent dynamics are reshaping how value is created and captured across the 3D scanning wind lidar market. First, measurement confidence is increasingly institutionalized through independent testing and compliance pathways. Wind lidar systems intended for wind energy applications are undergoing rigorous independent evaluation to ensure measurement accuracy and classification alignment with IEC standards. As demonstrated by recent product milestones in the sector, IEC classification is no longer an abstract technical benchmark; it is becoming a procurement prerequisite that influences bankability, risk modeling, and vendor selection criteria. Organizations that treat validation as a core product attribute rather than a post-development formality are gaining structural advantage in tenders and multi-vendor evaluation processes.
Second, offshore wind expansion is accelerating demand for scanning lidar capable of 3D wind field mapping and, in certain configurations, dual lidar setups for enhanced resource assessment. Offshore measurement challenges—complex boundary layer behavior, limited fixed measurement infrastructure, and the cost of met mast deployment—are pushing developers toward remote sensing solutions that can deliver spatially rich data across extended campaign durations. This shift is expanding the technical expectations placed on scanning architectures, data processing pipelines, and offshore deployment logistics.
Worldwide 3D Scanning Wind Lidar Market
Third, the underlying component ecosystem continues to evolve in ways that affect cost structures, performance ceilings, and supply chain resilience. Core systems increasingly rely on eye-safe fiber lasers operating around 1550nm, paired with associated photodetectors and optical assemblies. Advances in these components influence not only measurement range and signal fidelity, but also system reliability, maintenance intervals, and the economic feasibility of extended offshore or remote onshore deployments. Manufacturers that secure access to robust optical and laser component supply chains, and that design around serviceability and calibration durability, are better positioned to protect margins and delivery timelines.
What the Full Report Delivers: Operational Intelligence for 2026 Decision-Making
The complete Worldwide 3D Scanning Wind Lidar Market report translates these dynamics into an actionable decision framework. It is designed for teams that need to move from market awareness to executable strategy, with analytical depth sufficient to support product planning, investment review, and competitive response. The report provides a structured examination of market sizing and forecast behavior across the full historical and projection window, with particular attention to the inflection points and growth drivers most relevant to mid-cycle planning. Rather than presenting static totals, the analysis connects revenue trajectories to the development pipelines, measurement campaigns, and procurement rhythms that generate demand.
Beyond top-line sizing, the report delivers a detailed segmentation architecture that clarifies how regional demand patterns, deployment model adoption, and application-driven purchasing behavior interact. This enables readers to identify where commercial concentration is forming, which segments are most exposed to certification-driven consolidation, and where deployment flexibility can be monetized through differentiated service offerings. The analysis also maps competitive positioning across the principal manufacturers, examining product lineage, recent launches, validation milestones, and the strategic implications of recent moves in the sector. This competitive review is structured to help executive teams assess which capabilities are becoming table stakes and where durable differentiation can still be built.
Industry context is integrated throughout, ensuring that macroeconomic and technical signals are interpreted through a commercial lens. The report addresses how offshore wind momentum, compliance and classification expectations, and component-level evolution are reshaping procurement criteria and supplier evaluation. It further explores the operational realities of deployment, including the logistics of ground-based scanning campaigns, the trade-offs inherent in nacelle and buoy-mounted configurations, and the growing importance of data processing, calibration reliability, and long-term support models.
For corporate strategists, the report functions as a structured input to multiple decision pathways. Product leaders can use the segmentation and competitive maps to prioritize feature development, certification investment, and deployment-specific variants. Commercial teams can align go-to-market design with the regions and applications where measurement requirements and project timelines are converging most rapidly. Investment and partnership teams can evaluate which segments are attracting sustained demand and where supply chain or service capabilities are likely to become the binding constraint on growth.
Why This Report Matters for 2026 and Beyond
The 2026 planning cycle will reward organizations that can connect market growth to segment-level realism. A 7.85% compound growth path over the forecast horizon is meaningful only when paired with clarity on where volume is forming, which deployment models are becoming standard, how certification is reshaping vendor selection, and where offshore measurement requirements are creating premium demand for 3D scanning capability. The market is large enough to support multiple business models, but selective enough that undifferentiated hardware offerings will face increasing pressure on price and procurement cycle time.
Access to the complete report provides the missing granularity required to act with confidence: detailed structural analysis, provider positioning, recent development context, and the segmentation logic needed to translate forecast data into operational decisions. For enterprises operating in wind resource assessment, turbine operations, meteorological research, or lidar hardware and services, this research offers a single, coherent reference point for understanding where the market is heading and how to position for it.
The full Worldwide 3D Scanning Wind Lidar Market report is now available. Readers seeking the complete segmentation analysis, forecast detail, competitive profiles, and strategic recommendations can access the full research package to support 2026 planning and longer-term market strategy.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Scanning Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com