

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Ferrite Cable Cores Market Hits $750M in 2025, Forecast 5.23% CAGR to 2032

Strategic Intelligence for 2026: Navigating the Worldwide Ferrite Cable Cores Market
As global electrification and data transmission speeds accelerate, the ferrite cable cores market stands at a critical inflection point. For executives making capital allocation, supply chain, and R&D decisions in 2026, understanding the trajectory of this specialized EMI suppression sector is no longer optional—it is a strategic imperative. The Worldwide Ferrite Cable Cores Market research report provides a comprehensive, data-driven framework to decode market arithmetic, competitive maneuvering, and structural supply constraints that will define the next seven years of industry growth.
This article previews the analytical architecture of the full study, highlighting the macro momentum, competitive dynamics, and operational realities that corporate strategists must internalize before committing to product roadmaps or vendor partnerships.
Market Trajectory and Structural Growth Drivers
The market has demonstrated resilient expansion over the historical review period, moving from an estimated 580.45 million USD in 2020 to a projected 750.0 million USD in 2025. This growth has been propelled by the irreversible miniaturization of electronic assemblies, the proliferation of high-speed data interfaces, and the tightening of electromagnetic compatibility standards across consumer, industrial, and automotive domains. The base year establishes a clear baseline of demand elasticity tied to device density rather than unit volume alone.
Looking toward the forecast horizon of 2026 through 2032, the sector is positioned to compound at a steady rate, with revenue expected to breach 787.4 million USD in 2026 and continue scaling toward over 1 billion USD by the early 2030s. The 5.23 percent CAGR reflects a mature yet structurally expanding market, where growth is less dependent on headline adoption cycles and more anchored in the continuous need for noise suppression across expanding cable networks. For decision-makers, this trajectory signals that ferrite cable cores are transitioning from a commodity-adjacent component to a performance-critical element in system-level electromagnetic integrity design.
The revenue progression underscores a market that rewards foresight. Early-stage planning in 2026 must account for both the volume uplift driven by electrified transport and high-bandwidth communications, as well as the margin pressure introduced by raw material volatility and regional trade dynamics. Understanding where demand concentrates and how pricing power shifts across the value chain will separate organizations that merely absorb cost increases from those that reposition their portfolios ahead of the curve.
Core Report Scope and Actionable Intelligence
The full research study is engineered to move beyond top-line projections and into the operational granularity that procurement, engineering, and strategy teams require. It delivers a structured dissection of the market across three primary analytical lenses: product typology, end-use application, and geographic distribution. By isolating how cylindrical and sleeve cores, snap-on and split cores, flat and ribbon cable cores, and other specialized formats contribute to total market value, the report enables precise portfolio alignment with high-growth segments without relying on generalized industry narratives.
The application breakdown maps revenue contribution across consumer electronics, automotive electronics, industrial automation, IT and telecommunications, and medical and other sectors. This mapping is essential for companies evaluating market entry, capacity expansion, or customer vertical prioritization. Each application carries distinct qualification requirements, volume profiles, and price sensitivity thresholds, and the study contextualizes how these variables intersect with long-term demand forecasting.
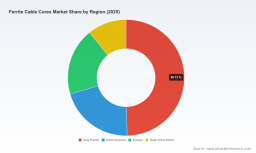
Geographically, the research delineates regional market structures, capturing how local manufacturing footprints, trade flows, and regulatory environments shape demand and supply patterns. Rather than presenting static snapshots, the analysis integrates historical volatility and forward-looking policy trajectories to help executives anticipate where regional opportunities will open or contract. The report also incorporates competitive benchmarking, pricing architecture, and regulatory overlay, providing a multi-dimensional view that supports scenario planning rather than point forecasts.
Practitioners will find the study particularly valuable for its integration of supply-side realities with demand-side growth. By linking material sourcing dependencies, certification pathways, and lead-time extended conditions to market sizing, the report offers a pragmatic lens for building resilient sourcing strategies and realistic production calendars.
Competitive Landscape and Strategic Positioning
The ferrite cable cores market exhibits moderate concentration, with the top three firms accounting for approximately 38.45 percent of total revenue and the top five capturing roughly 52.12 percent. This structure indicates a competitive arena where established multinationals hold meaningful share, but specialized manufacturers and regional players retain the ability to command niche positioning through material innovation, application-specific certification, and localized service capabilities.
Leading participants such as TDK Corporation and Murata Manufacturing Co., Ltd. continue to anchor the market with broad portfolios spanning clip-on, toroidal, and snap-on configurations tailored for EMI suppression across consumer electronics, automotive, and industrial cable assemblies. Their scale enables sustained investment in high-permeability formulations and high-frequency performance, which is increasingly relevant as data rates climb and cable architectures become more densely packed. Laird Technologies, operating under its advanced materials heritage, competes with snap-on and cable core solutions designed for high-frequency noise suppression in power cords, USB cables, and automotive wiring harnesses, emphasizing qualification depth and application reliability.
Fair-Rite Products Corp. has carved a distinct position by specializing in ferrite cores, rods, and snap-on assemblies for EMI and RFI suppression across telecom, medical, and aerospace cable assemblies, where stringent validation and material consistency carry outsized weight. Ferroxcube, part of the Yageo Company ecosystem, contributes ferrite cable cores and toroidal cores focused on power line filtering and EMI suppression in industrial and consumer electronics, while Vacuumschmelze GmbH & Co. KG brings high-performance ferrite core expertise to automotive, renewable energy, and telecommunications applications where thermal and frequency performance thresholds are demanding.
Ferrite Cores Market
Mitsubishi Materials Corporation and Samsung Electro-Mechanics reinforce the Asian manufacturing base with ferrite cores and EMI suppression components targeting mobile devices, PCs, and automotive cables, aligning component performance with the rapid product cycles of consumer and automotive electronics. Sunlord Electronics focuses on cost-effective ferrite cable cores and snap-on filters for consumer electronics and data cables, appealing to value-sensitive volume segments. Epcos AG, as aTDK subsidiary, adds specialized capability in ferrite cores for EMI suppression in power supply cables and high-speed interfaces, extending the portfolio breadth of larger industrial groups.
Recent corporate activity illustrates how competition is shifting from pure volume toward performance differentiation. In October 2025, TDK Corporation introduced new high-permeability ferrite snap-on cores for 5G and automotive Ethernet cables, emphasizing improved noise suppression up to 10 GHz. In June 2025, Fair-Rite Products Corp. released an updated catalog featuring 31-material ferrite cores optimized for USB4 and PCIe Gen5 cable EMI filtering, reflecting the market's migration toward higher data-rate standards. In March 2025, Laird Performance Materials achieved AEC-Q200 qualification for automotive-grade ferrite cable cores for EV charging cables, a milestone that underscores the increasing importance of automotive reliability certifications in securing design wins. In November 2024, Murata Manufacturing showcased compact ferrite cores for high-speed data cables at Electronica 2024, reinforcing continued investment in form-factor reduction and integration-friendly designs.
For strategists, these developments point to a market where material science, certification readiness, and application-specific engineering now determine share shifts more than broad distribution reach alone. Companies that can align product attributes with fast-emerging cable standards and automotive electrification requirements will capture disproportionate value in targeted segments.
Supply Chain, Regulatory, and Pricing Dynamics
Beyond demand and competition, the operational environment for ferrite cable cores is shaped by material sourcing concentration, trade policy, and regulatory compliance. Ferrite core production depends on iron oxide, manganese, and zinc, with sourcing heavily concentrated in China, which accounts for more than 80 percent of global supply. This dependency creates structural sensitivity to raw material availability, logistics disruptions, and regional production policy shifts. For companies building multi-year procurement plans in 2026, mapping exposure to these inputs is essential to avoid margin erosion and production delays.
Trade dynamics further complicate sourcing and cost planning. US tariffs on Chinese ferrite components increased to 25 percent under Section 301 in 2024, directly affecting import costs for cable core assemblies and compressing the economics of cross-border procurement strategies. Organizations that previously relied on centralized Asian sourcing must now evaluate regionalization, dual-sourcing, or localized assembly models to protect cost structures and delivery reliability.
Worldwide Ferrite Cable Cores Market
Regulatory requirements add another layer of complexity. The EU RoHS Directive 2011/65/EU restricts lead and cadmium in ferrite cores to below 0.1 percent by weight for all electronics cables, maintaining compliance as a continuous operational requirement rather than a one-time certification event. This standard influences material selection, supplier qualification, and documentation processes, especially for multinational product lines that must satisfy multiple jurisdictional requirements simultaneously.
Pricing pressure has become more visible as input constraints intersect with demand momentum. The average price of snap-on ferrite cores rose 12 percent year-over-year to a range of roughly 0.45 to 1.20 USD per unit, driven by raw material shortages and tighter availability. This increase affects not only component cost but also the broader economics of cable assembly manufacturers, who must balance price pass-through with competitive positioning. Lead times have also extended, with NiZn ferrite cores reaching 20 to 24 weeks amid surging demand for EV and data center cables. Such extended lead times alter inventory planning, engineering validation cycles, and time-to-market assumptions, making supply visibility a strategic asset rather than an operational footnote.
Why This Research Matters in 2026
In 2026, the ferrite cable cores market will reward organizations that combine demand foresight with supply discipline. The convergence of high-speed data standards, automotive electrification, and stringent electromagnetic compliance requirements is expanding the addressable need for effective noise suppression, but it is also intensifying competition for materials, certifications, and qualified manufacturing capacity. The strategic question is no longer whether the market will grow, but how to position within that growth in a way that preserves margin, agility, and customer relevance.
This research provides the analytical scaffolding to answer that question. It equips leadership teams with a structured view of where revenue is accumulating, how competitive advantages are being built, and which external pressures will most affect cost and availability. By linking market sizing to material realities, trade exposure, and product differentiation trends, the study enables more confident decisions on capacity planning, vertical focus, supplier selection, and R&D prioritization.
For executives seeking to move from observation to action, the full report delivers the detail required to translate macro momentum into executable strategy. The complete analysis, including granular segmentation, regional dynamics, competitive benchmarking, and forward-looking scenario considerations, is available through the official market research page, where organizations can access the full intelligence needed to guide 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com