

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Computer Consulting Services Market to Hit $865B in 2025, Forecast 8.2% CAGR to 2032

Strategic Intelligence for the Digital Era: Navigating the Computer Consulting Services Market in 2026
Executive Overview
The computer consulting services market stands at a critical inflection point in 2026. As organizations worldwide accelerate their digital transformation journeys, the demand for strategic IT guidance, implementation expertise, and managed solutions has reached unprecedented levels. This market intelligence report provides a comprehensive examination of an industry that has evolved from a supportive function to a central driver of corporate strategy and competitive advantage.
The global computer consulting services market demonstrates robust expansion trajectories, with historical data from 2020 through 2025 revealing consistent growth patterns that underscore the sector's resilience and momentum. The base year valuation of 865.0 billion USD in 2025 represents a significant acceleration from the 586.84 billion USD recorded in 2020, reflecting a compound annual growth rate that positions this market among the most dynamic segments in the broader technology services landscape. Forward projections through 2032 indicate continued expansion, with the market anticipated to surpass 1.5 trillion USD by the end of the forecast period.
This growth narrative is not merely quantitative. It reflects fundamental shifts in how enterprises perceive and engage with technology consulting partners. The integration of artificial intelligence capabilities, the proliferation of hybrid cloud architectures, and increasingly complex regulatory requirements have transformed the consulting engagement model from periodic advisory interactions to continuous strategic partnerships.
Market Growth Dynamics and Structural Evolution
The expansion of the computer consulting services market between 2020 and 2025 demonstrates remarkable consistency, with revenue progression from 586.84 billion USD to 865.0 billion USD marking a substantial increase over the historical observation period. Each year within this window reflects compounding growth factors including enterprise digitalization acceleration, post-pandemic technology investment rebalancing, and the emergence of AI-driven operational models.
The forecast period from 2026 through 2032 projects sustained momentum, with annual revenue expectations climbing from 926.17 billion USD in 2026 to 1501.78 billion USD by 2032. This trajectory reflects an 8.2 percent compound annual growth rate that positions the market for a near doubling of its current scale within seven years. Such growth rates signal more than incremental expansion. They indicate structural market transformation driven by enterprise appetite for specialized technology expertise.
Several macroeconomic and technological forces underpin this growth projection. Organizations are increasingly recognizing that technology consulting is no longer an optional enhancement but a core competency requirement. The convergence of generative AI deployment, cybersecurity threat escalation, cloud migration complexity, and regulatory compliance demands has created a consulting engagement landscape where breadth and depth of expertise directly correlate with client outcomes.
The market concentration metrics reveal a moderately fragmented landscape, with the top three players commanding 18.5 percent of total market share and the top five holding 24.1 percent. This concentration pattern indicates opportunities for both established leaders and emerging specialists. Large-scale integrators leverage global delivery capabilities and brand recognition, while regional and niche players compete through domain expertise, localized service models, and agile engagement structures.
Demand Architecture: Service Lines and Sector Adoption
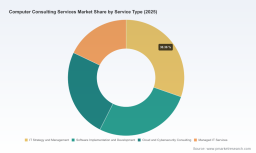
The computer consulting services market encompasses multiple service categories, each addressing distinct enterprise needs while often intersecting in client engagements. IT strategy and management consulting represents the largest service segment, reflecting the persistent demand for executive-level technology roadmapping, governance frameworks, and transformation oversight. Organizations increasingly seek consulting partners who can align technology investments with business objectives, manage vendor ecosystems, and establish operating models that sustain digital initiatives beyond initial implementation phases.
Software implementation and development services constitute a substantial portion of market activity, driven by enterprises modernizing legacy systems, deploying new platforms, and customizing solutions for industry-specific workflows. This service line benefits from the continuous evolution of software portfolios, API-driven architectures, and low-code development platforms that expand the scope of implementable solutions.
Cloud and cybersecurity consulting has emerged as a critical growth vector, reflecting the dual imperatives of infrastructure modernization and threat protection. Enterprises navigating multi-cloud strategies, data sovereignty requirements, and zero-trust architecture adoption require specialized guidance that combines technical depth with risk management acuity. The regulatory environment has further amplified demand, as compliance frameworks increasingly mandate documented IT resilience, data protection protocols, and incident response capabilities.
Managed IT services round out the service portfolio, providing ongoing operational support, monitoring, and maintenance capabilities that allow client organizations to focus internal resources on strategic initiatives. This segment benefits from the trend toward outsourcing non-core IT functions and the growing complexity of maintaining heterogeneous technology environments.
Management Consulting Services Market
Across end-user sectors, diverse industries demonstrate varying degrees of consulting engagement intensity. Financial services organizations lead adoption, driven by regulatory compliance requirements, digital customer experience expectations, and the need for robust technology infrastructure to support transaction processing and risk management. Manufacturing enterprises invest in consulting services to support Industry 4.0 initiatives, supply chain digitization, and operational technology integration. Healthcare organizations seek guidance on electronic health record optimization, data interoperability, and telehealth platform deployment. Retail and e-commerce operators leverage consulting expertise for omnichannel strategy, customer data platforms, and inventory management system modernization. Government entities and broader public sector organizations engage consulting partners for digital service delivery, cybersecurity hardening, and legacy system transformation.
Competitive Landscape: Strategic Positioning of Market Leaders
The computer consulting services market features a diverse array of global competitors, each differentiated by geographic reach, service specialization, industry focus, and delivery model evolution. The competitive dynamics reflect both consolidation pressures and differentiation opportunities as enterprises evaluate consulting partners across multiple criteria including technical capability, industry knowledge, cost structures, and cultural alignment.
Accenture maintains a prominent position as a global leader providing technology consulting, digital transformation, cloud, AI implementation, and IT strategy services across industries. The firm's extensive global delivery network, dedicated industry practices, and investment in proprietary platforms and methodologies support its positioning as a comprehensive transformation partner for large enterprise clients.
IBM Consulting offers IT consulting, hybrid cloud, AI, data platforms, and enterprise systems integration with particular emphasis on real-time data capabilities and generative AI applications. The organization's deep enterprise relationships, IBM technology ecosystem integration, and focus on data-driven decision architectures differentiate its consulting approach. Recent strategic moves, including the completed 11 billion USD acquisition of Confluent in March 2026, demonstrate the firm's commitment to strengthening real-time data streaming platform capabilities that enhance enterprise AI and agent functionality. The acquisition announcement made in December 2025 had signaled this strategic intent, reflecting a broader industry trend where consulting organizations invest in technology assets that augment their advisory and implementation capabilities.
Deloitte Consulting provides technology consulting encompassing enterprise modernization, AI, cloud, cybersecurity, and digital transformation services. The firm's professional services heritage, multidisciplinary team structures, and integration of consulting with audit, tax, and advisory capabilities create a differentiated value proposition for clients seeking holistic organizational guidance.
Capgemini delivers IT consulting, digital services, cloud, AI, and engineering solutions with strong industry domain expertise. The organization's emphasis on combining technology capabilities with sector-specific knowledge supports its positioning for complex transformation programs where operational context and technical execution must align closely.
Tata Consultancy Services operates as a global IT consulting and services provider focusing on digital transformation, cloud, AI, and enterprise solutions. The firm's scale, offshore and nearshore delivery capabilities, and extensive client portfolio across industries and geographies provide competitive advantages in cost-efficient service delivery and broad technology exposure.
Cognizant offers IT consulting, digital engineering, cloud migration, AI, and business process services. The organization's focus on digital engineering and process-centric transformation creates differentiation for clients seeking to reimagine operational workflows alongside technology modernization.
Infosys provides consulting, technology, and next-generation digital services including AI and cloud solutions. The firm's investment in innovation hubs, academic partnerships, and technology platform development supports its ability to offer contemporary solution architectures and emerging technology expertise.
Wipro delivers IT consulting and business process services with expertise in digital, cloud, and engineering domains. The organization's integrated service model and focus on client outcomes across technology and process dimensions positions it as a comprehensive engagement partner for enterprises pursuing operational and technological improvement.
Recent market activity illustrates the competitive intensity and strategic maneuvering characteristic of this landscape. Beyond IBM's significant acquisition, New Charter Technologies' April 2026 acquisition of GraVoc expanded strategic IT consulting, managed services, and cybersecurity offerings across North America. Such consolidation activity reflects the market's dynamism, as organizations pursue scale, capability expansion, and geographic reach through acquisition strategies.
Regulatory and Operational Context Shaping 2026 Engagement Models
The consulting engagement environment in 2026 operates within a regulatory framework that directly influences project scope, implementation requirements, and risk assessment protocols. The EU Digital Operational Resilience Act, which took full effect in January 2026, applies to financial institutions and their IT service providers with requirements for ICT risk management and resilience testing. This regulation has expanded the consulting mandate beyond technology optimization to include documented resilience frameworks, testing protocols, and ongoing compliance monitoring. Organizations providing consulting services to financial sector clients must now demonstrate capabilities that align with these resilience standards, influencing both project deliverables and partnership qualification criteria.
In the United States, the Department of Justice Bulk Data Rule, effective from April 2025 with additional requirements introduced in October 2025, imposes cybersecurity controls and record-keeping obligations for certain bulk sensitive personal data transactions. This regulatory development affects consulting engagements involving data migration, integration, and processing activities, requiring enhanced security architecture guidance and documentation practices.
Labor market dynamics also shape the consulting services landscape. Projected average salary increases across technology and IT roles of 1.6 percent in 2026 reflect moderate compensation growth, while AI and machine learning engineer and data scientist salaries are projected to rise by 4.1 percent. Consulting and enterprise systems positions are expected to see salary gains of 1.7 percent amid ongoing demand for digital skills. These compensation trends influence consulting firm cost structures, pricing models, and talent acquisition strategies. Organizations seeking consulting partners must evaluate not only service quality and industry expertise but also the partner's ability to attract and retain specialized talent in a competitive labor market.
What This Research Delivers: Framework for Informed Decision-Making
This comprehensive market research report provides decision-makers with a deep, structured understanding of the computer consulting services market as it exists in 2026 and is projected to evolve through 2032. The analysis integrates quantitative market sizing, segmentation insights, competitive profiling, and contextual factor assessment into a coherent intelligence framework designed to support strategic planning, vendor selection, investment allocation, and competitive positioning activities.
The report delivers detailed market size estimates across historical and forecast periods, enabling stakeholders to contextualize current market conditions within long-term growth trajectories. Revenue projections are structured to facilitate scenario planning and sensitivity analysis, allowing organizations to evaluate how variations in adoption rates, regulatory developments, or economic conditions might influence market outcomes.
Segmentation analysis examines the market across multiple dimensions, including geographic regions, service types, and end-user sectors. These breakdowns illuminate demand concentration patterns, growth differentials across categories, and the relative significance of various market segments. Understanding which service lines command the largest revenue shares and which industry sectors drive the highest consulting engagement volumes enables organizations to align their strategic priorities with market opportunity distributions.
Competitive intelligence components provide detailed profiles of key market participants, including organizational background, service offerings, headquarters locations, and publicly available digital resources. The analysis incorporates recent corporate developments, including acquisitions, partnerships, and strategic announcements, to illuminate how leading firms are reshaping their capabilities and market positions. Tracking these developments enables stakeholders to anticipate competitive moves, identify consolidation patterns, and evaluate how market structure evolution might affect service availability, pricing dynamics, and partnership opportunities.
Contextual analysis sections address the operational factors that influence consulting engagement execution and outcomes. Regulatory developments, labor market conditions, technology adoption trends, and macroeconomic indicators are examined for their implications on service demand, project scoping, risk management, and vendor evaluation criteria. This contextual layer transforms raw market data into actionable intelligence that accounts for the real-world conditions under which consulting services are delivered and consumed.
The report is structured to support multiple use cases. Strategic planners can leverage growth projections and segmentation insights to inform market entry decisions, investment prioritization, and capability development roadmaps. Procurement and sourcing teams can utilize competitive profiles and market structure analysis to inform vendor evaluation criteria, negotiation strategies, and portfolio construction approaches. Investment analysts and financial stakeholders can reference market sizing data and growth trajectories to assess sector attractiveness and competitive positioning dynamics. Executive leadership teams can draw on the integrated analysis to calibrate digital transformation strategies, assess technology partnership models, and align organizational capabilities with market evolution patterns.
Strategic Implications for Enterprise Decision-Makers
The computer consulting services market in 2026 presents both opportunities and complexities for organizations navigating technology-driven transformation. The scale and growth trajectory of the market indicate sustained demand for consulting expertise, while the diversity of service lines and end-user sectors reflects the broad applicability of consulting engagements across organizational functions and industries.
Enterprise leaders evaluating consulting partnerships should consider several strategic dimensions. The breadth versus depth trade-off requires careful assessment of whether organizations need comprehensive transformation partners capable of addressing multiple technology domains simultaneously or specialized consultants with deep expertise in particular service areas. The growing importance of AI implementation, cybersecurity resilience, and regulatory compliance suggests that consulting partners must demonstrate current and forward-looking capabilities in these domains rather than relying solely on historical service delivery track records.
Market concentration patterns indicate that while large global integrators maintain significant market presence, substantial opportunities exist for regional specialists, boutique firms, and emerging players that offer differentiated value propositions. Enterprises should evaluate consulting partners against criteria that include industry-specific knowledge, geographic delivery capabilities, technology platform expertise, cultural and communication alignment, and cost competitiveness relative to engagement scope and complexity.
The regulatory environment adds a layer of due diligence to consulting partner selection. Organizations in regulated industries or those handling sensitive data should assess consulting partners' capabilities related to compliance frameworks, security architecture, resilience testing, and documentation practices. The EU Digital Operational Resilience Act and US Department of Justice Bulk Data Rule exemplify regulatory developments that influence consulting engagement requirements and elevate the importance of demonstrated compliance competency.
Talent availability and cost dynamics warrant ongoing monitoring as organizations structure long-term consulting engagements. Salary trends for specialized roles, including AI and machine learning engineers, data scientists, and consulting professionals, influence service pricing and delivery model viability. Understanding how consulting partners manage talent acquisition, retention, and deployment provides insight into their ability to sustain service quality and meet engagement commitments over time.
Conclusion
The computer consulting services market represents a dynamic, expanding landscape in 2026, shaped by technological innovation, regulatory evolution, competitive intensity, and sustained enterprise demand for strategic technology guidance. Organizations that approach consulting engagement decisions with comprehensive market intelligence, clear strategic objectives, and rigorous partner evaluation criteria position themselves to extract maximum value from consulting relationships while mitigating execution risk. This research report provides the foundational intelligence necessary to navigate this complex market environment with confidence and strategic clarity.
Computer Consulting Services Market
For detailed analysis of this topic, please visit the official page: Computer Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com