

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pearls Market to Hit $5.95B by 2032, Driven by 5.25% CAGR from 2025

Strategic Clarity in a Polishing Market: Unlocking Value in the Global Pearls Sector through 2032
The global pearls market stands at a pivotal inflection point. As consumer preferences evolve and sustainability transitions from a niche concern to a baseline expectation, industry participants face a complex landscape where historical growth trajectories intersect with emerging geopolitical and regulatory realities. This report delivers a comprehensive analysis of the market environment, synthesizing five years of historical performance with a seven-year forecast horizon to equip executives with the intelligence required for decisive action in 2026 and beyond.
Understanding the trajectory of the pearls industry requires more than a surface-level glance at headline figures. It demands a rigorous examination of how production dynamics, consumer application trends, and regional shifts converge to shape profitability and market share. Our analysis provides the structural framework necessary to navigate these variables, ensuring that strategic planning is grounded in verified data rather than anecdotal observation.
Market Trajectory and Growth Dynamics
The sector has demonstrated resilient expansion over the recent historical period, with total market revenue reaching approximately 4150.0 million USD in the base year of 2025. This figure represents a steady climb from 3315.2 million USD recorded in 2020, reflecting a market that has successfully navigated supply chain disruptions and shifting luxury spending patterns during the review window.
Looking forward, the market forecast indicates a compound annual growth rate of 5.25 percent across the forecast period extending to 2032. By the end of this projection window, estimated revenues are poised to approach the 5937.77 million USD mark. This growth trajectory suggests that while the market is maturing, there remain significant avenues for expansion, particularly as value-added products and sustainable sourcing narratives deepen consumer engagement. The 5.25 percent CAGR signals a consistent, compound opportunity for stakeholders who can align their operations with the evolving demands of the luxury and semi-luxury segments.
The forecast period from 2026 through 2032 reveals a market that is not merely growing but transforming. Early forecast years show a stabilized baseline, while later years project accelerated momentum as new consumer cohorts enter the market and established buyers seek higher-tier offerings. This progression underscores the importance of timing in capital allocation and product development strategies.
Decoding the Competitive Landscape
The pearls industry is characterized by a mix of heritage houses, vertically integrated producers, and agile manufacturers. Competitive dynamics are shaped by control over supply chains, brand heritage, and the ability to respond to regulatory and sustainability mandates. Our analysis profiles the key organizations that define the market structure, providing a clear view of where influence and market power are concentrated.
Japanese firms remain central to the luxury pearl narrative. Mikimoto, a pioneer in cultured pearls since 1893, continues to specialize in high-quality Akoya and other cultured pearls, leveraging a legacy that bridges traditional craftsmanship with modern luxury jewelry offerings. Similarly, Tasaki operates as a luxury jeweler controlling full pearl production from farming to design, distinguishing itself through innovative combinations of pearls and diamonds. These entities exemplify the premium segment where brand equity and product quality drive valuation.
In the South Sea segment, Australian and regional producers play a critical role. Paspaley, a family-owned enterprise headquartered in Darwin, leads in premium Australian South Sea pearls with a focus on sustainable high-quality pearl farming and jewelry. Atlas Pearls, based in Subiaco, Australia, stands as a major producer and distributor of white and silver South Sea pearls, with farming operations extending into Indonesia. Jewelmer, headquartered in Makati, Philippines, specializes in golden South Sea pearls sourced from sustainable farms in Palawan, offering high jewelry that integrates cultivation and design. These players highlight the importance of provenance and operational control in the higher value tiers of the market.
Jewelry Beads Market
The retail and manufacturing landscape is further shaped by major jewelry retailers and regional producers. Chow Tai Fook, based in Hong Kong, leverages its significant Asian market presence to offer extensive pearl jewelry offerings, capitalizing on regional demand and distribution networks. In China's dominant pearl farming region, Zhejiang Grace Pearl Jewelry Co Ltd operates as a key player in freshwater pearl production and jewelry manufacturing, representing the scale and capacity of the freshwater sector. Together, these organizations illustrate the diverse operational models that coexist within the market.
Market concentration metrics indicate a fragmented yet evolving structure. The CR3 and CR5 values suggest that while leading firms hold notable positions, a substantial portion of market activity remains distributed across a broader base of producers and retailers. This fragmentation presents both challenges and opportunities for consolidation, partnership, and niche positioning.
Structural Shifts Across Regions and Applications
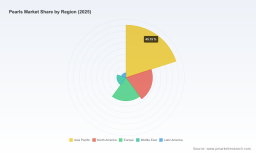
Regional performance patterns reveal distinct demand centers and growth vectors. Asia Pacific stands out as a dominant region, reflecting the combined influence of production capacity, cultural affinity for pearl jewelry, and expanding middle-class consumption. North America and Europe maintain significant market presence, driven by established luxury retail channels and demand for high-quality pearl pieces. The Middle East and Latin America contribute additional layers of demand, with evolving consumer behaviors and retail infrastructure shaping their respective trajectories. Each region presents unique entry barriers, channel dynamics, and consumer expectations that require localized strategic approaches.
Pearls Market
Application-level analysis highlights the enduring prominence of necklaces and pendants, which capture the largest share of market revenue. This segment benefits from the versatile nature of pearl jewelry and its strong association with both formal occasion wear and everyday luxury. Earrings and rings represent substantial secondary applications, offering diversification opportunities for designers and retailers. The "others" category encompasses a range of jewelry pieces and bespoke applications, indicating that innovation in design and product formats continues to expand the ways pearls are utilized. Understanding the revenue distribution across these applications enables companies to optimize product mix and inventory strategies.
In terms of product type, the market encompasses a range of pearl varieties, each with distinct value propositions. Freshwater pearls account for a significant portion of market activity, supported by robust production capabilities and broad accessibility. Akoya pearls remain synonymous with classic luster and precision, appealing to consumers who value traditional elegance. South Sea pearls, including both white and golden varieties, command premium positioning through size, rarity, and sustainable farming narratives. Tahitian pearls offer unique coloration and exotic appeal. The interplay among these types shapes pricing architecture, sourcing strategies, and brand positioning across market tiers.
Industry Dynamics and Emerging Influences
Recent developments underscore a market that is actively addressing transparency, sustainability, and standardization. In September 2025, the Global Pearl Development Community (GPDC) launched as a non-governmental organization uniting pearl producers and stakeholders to collaborate on sustainability, standards, and innovation. This initiative reflects a broader industry push toward ethical practices and global awareness across both saltwater and freshwater sectors. The formation of such a body signals a maturing market that recognizes the strategic value of collective action in maintaining consumer confidence and operational integrity.
Parallel to industry-led efforts, regulatory and informational frameworks are expanding. The CIBJO Pearl Commission released an updated Pearl Special Report in late 2025, highlighting science for nature-positive positioning and progress on an expanded 267-page Pearl Guide. This publication marks a significant increase from previous editions, incorporating sustainability impact case studies and classification systems designed to enhance industry transparency and consumer trust. The expanded guide provides a more rigorous reference for sourcing, classification, and communication, helping brands align their messaging with verifiable standards.
Further reinforcing this trajectory, subsequent publications in late 2025 emphasized sustainability, Australian South Sea pearls market overviews, and scientific monitoring initiatives. These developments collectively indicate that sustainability is no longer a peripheral concern but a core component of market strategy, influencing everything from farming practices to retail storytelling.
Navigating Risks and Strategic Considerations
Strategic planning in the pearls market must account for external pressures that can alter cost structures and supply chain reliability. Trade policy discussions have surfaced potential tariff impacts on imports, including references to significant tariff levels affecting Chinese freshwater pearls in certain trade conversations. Such dynamics can influence pricing, sourcing decisions, and the competitive balance between regions. Companies must monitor these developments closely and build flexibility into procurement and distribution strategies to mitigate exposure.
At the same time, demand patterns in premium channels remain nuanced. Australian South Sea pearl demand continues to show steadiness in luxury channels, with a focus on sustainability and provenance storytelling. However, price sensitivity in some markets introduces complexity, requiring careful calibration of pricing strategies and value communication. Brands that can effectively articulate the quality, origin, and ethical credentials of their products are better positioned to sustain margins even in environments where consumers are more discerning.
Why This Report Matters for 2026 Decision-Making
The 2026 decision cycle demands more than broad market awareness. Executives need actionable intelligence that connects macro trends to operational implications. This report delivers a detailed examination of the factors shaping the pearls market, providing a structured basis for strategy formulation across multiple dimensions.
- Comprehensive market sizing and forecast analysis that maps revenue trajectories and growth rates across the historical and forecast periods.
- Detailed segmentation analysis covering region, product type, and application, enabling precise identification of high-potential segments and underpenetrated opportunities.
- In-depth profiles of key companies, including their operational focus, market positioning, and strategic capabilities, to support competitor benchmarking and partnership evaluation.
- Assessment of recent industry developments, including sustainability initiatives, regulatory publications, and standardization efforts, to anticipate shifts in consumer expectations and compliance requirements.
- Analysis of market concentration and competitive dynamics to inform positioning, pricing, and expansion strategies.
- Contextual evaluation of trade and geopolitical factors that may influence sourcing costs, supply chain resilience, and regional competitiveness.
By integrating these elements, the report equips decision-makers with a holistic view of the market landscape. The analysis is designed to support a range of strategic use cases, from market entry and product portfolio optimization to investment prioritization and risk management. Readers will gain clarity on where value is being created, which segments are driving growth, and how leading organizations are adapting to a rapidly evolving environment.
Conclusion
The pearls market is entering a period of sustained growth underpinned by evolving consumer values, expanding sustainability frameworks, and dynamic competitive interactions. With a projected CAGR of 5.25 percent and revenues expected to climb toward the 5.9 billion USD range by 2032, the sector offers meaningful opportunities for organizations that can combine operational excellence with strategic foresight. However, realizing these opportunities requires a deep understanding of segmentation patterns, competitive positioning, and the external forces that shape market outcomes.
This report provides the foundation for that understanding. It translates complex market data into a coherent strategic narrative, highlighting the factors that will matter most in 2026 and beyond. For executives seeking to make informed, forward-looking decisions, the full report delivers the granular insights, company-level analysis, and scenario-aware commentary needed to turn market potential into measurable results. To access the complete dataset, detailed segmentation breakdowns, and proprietary competitive assessments, we invite you to explore the full market research publication.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com