

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Pet Veterinary Diets Market Hits $13.62B in 2025, Forecast 5.81% CAGR to 2032

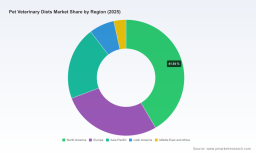
Strategic Intelligence for the Veterinary Diet Sector: Navigating a High-Growth Clinical Nutrition Landscape
As pets are increasingly integrated into household family structures, the diagnostic sophistication of veterinary medicine is accelerating demand for specialized clinical nutrition. The Worldwide Pet Veterinary Diets Market is no longer a peripheral consumer category; it is a therapy-adjacent ecosystem where nutritional intervention, regulatory compliance, and practitioner trust converge. Our newest market research initiative is designed to equip executives, product leaders, and commercial strategists with a decision-grade blueprint of this arena as it enters a critical growth window in 2026. The study balances historical trajectory with forward-looking scenario analysis, translating macro momentum into granular competitive and operational intelligence that can be actioned before the next fiscal cycle begins.
The global market for pet veterinary diets has demonstrated sustained resilience over recent years, expanding from a base valuation of approximately US$10,120 million in 2020 to an estimated US$12,987 million in 2024. The trajectory through 2025 reflects continued adoption of prescription-grade formulations, with the overall market reaching roughly US$13,620 million. Looking ahead, the study projects the market to reach approximately US$14,310 million in 2026, culminating in a 2032 valuation of about US$20,224 million. These figures translate into a compound annual growth rate of 5.81 percent across the 2026 to 2032 forecast window, positioning the category to outperform broader pet food segments as clinical indications, veterinary channel penetration, and premiumization reinforce one another. What makes this expansion strategically significant is not just the headline pace, but the structural shifts underneath it: therapeutic positioning is increasingly defining brand equity, formulation science is differentiating products within crowded therapeutic indications, and supply chain discipline is becoming a competitive moat rather than a baseline requirement.
Worldwide Prescription Diet Pet Food Market
For 2026 decision-makers, this research functions as a strategic orchestration tool. It does more than report size and growth; it maps where value is accumulating, which levers matter most for margin and share, and how the competitive center of gravity is shifting. The analysis is constructed around practical questions that leadership teams face now: How should portfolios be weighted across dry and wet formats as palatability, hydration, and handling convenience gain importance in specific clinical protocols? Where do indication-level demand drivers create the strongest pull for formulation investment, and which clinical categories are becoming crowded versus those still offering white space? How will regional regulatory frameworks and import scrutiny alter sourcing strategies, manufacturing footprints, and time-to-market for therapeutic claims? And crucially, how can companies defend against concentration risk when the category already exhibits pronounced leading-player dominance? The answer set is detailed in the full report; here, the objective is to surface the architecture of that intelligence and signal the areas where leadership will need sharper resolution to act confidently.
Rather than relying on generic trend commentary, the study is built as a practitioner’s field guide. It opens with a comprehensive market sizing and trajectory framework that stitches together historical performance from 2020 through 2025 with a multi-year forecast that extends to 2032. This historical-to-projection bridge is essential because it exposes inflection behavior, not just endpoints, enabling teams to test planning assumptions against both momentum and potential deceleration in specific sub-segments. The segmentation architecture then disentangles the market across multiple axes that matter operationally: product format, animal species, clinical indication, and regional footprint. These lenses are deliberately cross-referenced so a strategy team can evaluate, for example, how a given indication’s demand profile intersects with format preferences and species mix, instead of reading each dimension in isolation. That is where actionable insight emerges: in the tension between categories that appear strong on their own and the realities of how they perform when layered against distribution models and clinical adoption patterns.
Beyond sizing, the report scrutinizes competitive positioning with a level of detail aimed at go-to-market execution. It examines how leading companies leverage exclusive veterinary distribution, formulation credibility, and therapeutic branding to defend share, while also assessing how portfolio breadth, innovation cadence, and manufacturing compliance differentiate contestants in a market where clinical trust is the ultimate currency. The analysis integrates recent corporate moves as signals of strategic direction: a major prescription provider expanded its dermatologic care offering with a new skin-support formula targeting both food and environmental sensitivities in dogs, underscoring how symptom-specific positioning is being sharpened for practitioner recommendation. A competitor broadened its renal support wet diet format for cats to improve palatability and hydration uptake, reflecting a growing emphasis on adherence and feeding practicality in chronic-condition management. Separately, one large pet care manufacturer secured recognized food-safety certification for its U.S. veterinary diet manufacturing facility, reinforcing how supply chain credibility and quality assurance are becoming visible brand assets in professional channels. These developments are not isolated headlines; they are inputs into a competitive map that helps executives anticipate where rivals are placing bets and which capabilities are becoming table stakes.
Worldwide Pet Veterinary Diets Market
The research also embeds these competitive dynamics within a realistic operational environment. Clinical nutrition does not operate in a vacuum; it is shaped by ingredient economics, regulatory labeling expectations, establishment registration obligations, and import oversight. The study traces how carbohydrate-source costs and commodity volatility can compress formulation economics, how nutritional adequacy statements and therapeutic-claim safeguards influence labeling strategy, and how regional compliance regimes reshape the cost of market entry and maintenance. Import scrutiny on certain ingredient streams adds another layer of sourcing complexity, particularly for companies balancing cost efficiency with ingredient traceability and regulatory defensibility. In parallel, the report addresses quality and recall risk management, including how past industry incidents elevated protein testing standards and how current market conditions reflect a stabilized safety posture among principal brands. Together, these elements form a practical compliance-and-operations backdrop that leadership can use to pressure-test supply continuity, labeling claims, and channel readiness.
The competitive landscape remains shaped by a small group of influential players, with the top three firms collectively representing a substantial share of category revenue and the top five reinforcing a high concentration structure. This concentration has implications that extend beyond market share tables. It affects pricing dynamics, the ease with which new therapeutic lines can gain veterinary traction, and the strategic burden on manufacturers that must either scale credible research-backed positioning or differentiate through niche indications and specialized channels. Hill’s Pet Nutrition operates from a strong prescription-diet foundation, channeling therapeutic formulations through veterinary practice networks for conditions ranging from renal care to allergy management. Royal Canin maintains a broad veterinary diet architecture with emphasis on urinary, gastrointestinal, and mobility support, and continues to extend its range in response to palatability and adherence considerations. Nestlé Purina PetCare advances its Pro Plan Veterinary Diets line with joint, weight, and dermatologic formulations developed in coordination with veterinary professionals and distributed through professional channels. Virbac integrates therapeutic nutrition into a wider animal health portfolio, including support formulas for obesity, renal, and cardiac conditions. Dechra Pharmaceuticals contributes specialized nutrition within its companion animal health business, with product activity focused on dermatology and gastrointestinal care. The strategic question for 2026 is not simply who leads today, but which combination of formulation credibility, distribution control, indication expansion, and manufacturing compliance will determine who holds defensible advantage as the market grows and as therapeutic expectations rise.
What distinguishes this study from a conventional market overview is the emphasis on decision utility. The report is structured to help leaders answer concrete questions: where should innovation resources be concentrated to maximize clinical relevance and practitioner adoption? Which format and indication combinations offer the most attractive margin and growth profile under current competitive conditions? How should regional priorities be sequenced given differing regulatory intensity, import constraints, and consumer-pet owner sophistication? Where does concentration risk create vulnerability, and where might consolidation or targeted brand positioning open new routes to share? The study also maps the interplay between therapeutic positioning and channel economics, because veterinary diets are sold through a trust-mediated system where recommendation behavior, labeling legitimacy, and formulation precision jointly determine uptake. By integrating these considerations, the research gives executives a common factual base and a sharpened lens for portfolio debate.
Our Worldwide Pet Veterinary Diets Market research is built for teams that need more than headline growth numbers. It is intended for strategy leaders planning 2026 portfolio adjustments, commercial teams designing indication-led launches, supply and quality leaders assessing sourcing and compliance exposure, and competitive intelligence units tracking how the leading players are placing bets in clinical nutrition. The full document goes further into the segmentation contours, regional pacing, company-level strategic posture, and operational risk variables that underpin the category’s next phase of expansion. If your objective is to move from recognizing that the veterinary diet market is expanding to knowing exactly where to allocate resources, which therapeutic areas to prioritize, and how to position against a concentrated but innovating competitive set, the detailed intelligence within the report is the missing layer.
The strategic window opened by this 5.81 percent CAGR environment will reward companies that combine clinical credibility with operational rigor and clear indication focus. This research is designed to help you enter that window with precision rather than assumption. In the sections that follow in the complete study, we unpack the segmentation splits, competitive positioning logic, development signals, and regulatory and supply variables that turn broad growth into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Veterinary Diets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com