

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pancreatic & Biliary Stent Market To Hit $886.58M By 2032

Global Pancreatic and Biliary Stent Market Outlook 2026: Navigating Growth, Innovation, and Competitive Complexities
Executive Perspective for Strategic Decision-Makers
The worldwide pancreatic and biliary stent market stands at a critical inflection point as we move deeper into 2026. Driven by aging demographics, rising prevalence of pancreatobiliary malignancies, and continuous refinement of endoscopic retrograde cholangiopancreatography (ERCP) workflows, the sector has demonstrated resilient demand patterns across both established and emerging care settings. Our most recent Worldwide Pancreatic and Biliary Stent Market research synthesizes five years of historical performance with a forward-looking trajectory extending through 2032, equipping executives, investors, and clinical-commercial leaders with the analytical framework needed to allocate capital, shape pipeline priorities, and position portfolios against shifting reimbursement and competitive realities.
This article serves as a strategic preview of the full study. It outlines the macro momentum shaping the sector, dissects the structural forces influencing adoption and pricing, introduces the competitive architecture defining the battlefield, and details the operational intelligence embedded in the complete report. Throughout, we deliberately withhold granular segmentation tables, precise regional revenue splits, and product-type share percentages. Those figures are not merely supplementary details; they are decision-grade inputs that require the methodological rigor and cross-referenced validation of the full publication. Readers seeking actionable precision are encouraged to access the complete dataset through our dedicated research portal.
Worldwide Pancreatic and Biliary Stent Market
Macro Trajectory and Revenue Architecture: Reading the Growth Signal
From 2020 through 2025, the global pancreatic and biliary stent market navigated a period marked by pandemic-era supply chain friction, procedural backlog normalization, and subsequent demand catch-up across hospital endoscopy suites and ambulatory surgical centers. Historical revenue movements during this window reflect both volume recovery and modest price stabilization as procurement teams recalibrated vendor relationships. By 2025, total market revenue had settled at approximately 572.4 million USD, establishing a baseline that carries meaningful implications for 2026 planning cycles.
Looking ahead, the forecast horizon spanning 2026 to 2032 projects a compound annual growth rate of nearly 6.45 percent. Under the base scenario, revenue is expected to advance from roughly 613.85 million USD in 2026 toward approximately 886.58 million USD by 2032. This trajectory is not a straight line; it incorporates cyclical sensitivities around procedure volume shifts, evolution in inpatient versus outpatient care settings, and the pacing of regulatory clearances for next-generation devices. The overall contour suggests sustained expansion, yet the distribution of that growth across indications, product architectures, and geographies will be highly uneven, requiring executives to move beyond aggregate indices when constructing market-entry or portfolio-investment strategies.
Two strategic takeaways emerge from the macro view. First, the mid-single-digit CAGR environment rewards companies that can align product development with demonstrable clinical differentiation and health-economic value, rather than relying on volume-driven commoditization. Second, because the market is relatively concentrated, incremental share gains at the top of the competitive hierarchy can translate into outsized revenue implications. The full report quantifies these concentration dynamics and maps the strategic levers that incumbents and challengers are deploying to protect or expand their positions.
Structural Market Dynamics: Regulation, Reimbursement, Materials, and Clinical Adoption
Market performance in this space is heavily conditioned by a set of interdependent dynamics that extend well beyond simple procedure counts. Regulatory classification, material science choices, reimbursement coding pathways, and procedure-side economics collectively shape the speed of adoption, the pricing architecture, and the barriers to entry that new participants must navigate.
On the regulatory front, biliary and pancreatic stents are classified as Class II devices under 21 CFR 876.5010, as biliary catheters and accessories, requiring 510(k) premarket notification to demonstrate substantial equivalence to legally marketed predicates. This framework establishes a predictable but demanding clearance pathway. Sterile-labeled stents and delivery systems must also satisfy sterility information submission expectations consistent with FDA guidance and packaging standards such as AAMI/ANSI/ISO 11607-1. The practical consequence for commercial teams is twofold: time-to-market is sensitive to predicate selection, design controls, and documentation rigor, while post-clearance execution depends on disciplined manufacturing and labeling practices that stand up to inspection and real-world clinical use.
Reimbursement architecture further influences adoption. ERCP procedures involving the placement of an endoscopic stent into the biliary or pancreatic duct are commonly reported under CPT code 43274, with associated APC 5331 payment structures in hospital outpatient settings. Because procedural coding and payment grouping affect hospital procurement decisions, physician preference, and the relative attractiveness of specific stent platforms, understanding the interplay between device attributes and coding pathways is essential for forecasting demand by care setting. The complete study unpacks how these reimbursement mechanics intersect with volume trends and site-of-service shifts, enabling more granular scenario planning.
Materials and design continue to differentiate products in a crowded field. The majority of self-expanding metal biliary stents are constructed from nitinol, a nickel-titanium alloy favored for its biocompatibility, thermal memory properties that enable self-expansion at body temperature, and corrosion resistance. Plastic stents, by contrast, are typically manufactured from polyethylene, polyurethane, or material blends, with standard diameters such as 7.0, 8.5, or 11.5 French and lengths ranging from 5 to 18 centimeters. Pigtail configurations are frequently employed to reduce migration risk. These technical considerations are not academic; they translate directly into deliverability, patency duration, complication profiles, and ultimately clinician preference. Our analysis evaluates how material and design choices map to clinical use cases, debasing decisions around short-term drainage versus longer-term obstruction management.
Application Landscape and Product Architecture: Mapping Clinical Demand to Commercial Opportunity
The clinical application mix is central to understanding where growth will materialize and which product types will capture the greatest share of value. Biliary stenosis remains the dominant therapeutic context, reflecting a broad patient population with benign and malignant strictures, stone disease, and post-surgical or oncologic obstructions. Pancreatic cancer represents a second major demand center, driven by the need for ductal decompression and palliative drainage in advanced disease. Chronic pancreatitis contributes a distinct but consistent demand stream, often requiring iterative interventions and careful balancing of drainage efficacy against stent-related complications. A separate category of other applications rounds out the indication landscape, encompassing additional procedural scenarios that nonetheless influence overall volume and procurement patterns.
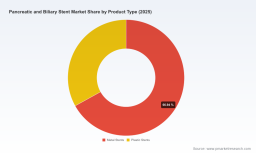
From a product architecture perspective, the market is anchored by metal stents and plastic stents, each serving different clinical and economic roles. Metal stents are commonly selected where longer patency and larger lumen diameter are prioritized, particularly in malignant obstructions and select benign indications. Plastic stents remain relevant where temporary drainage, lower unit cost, and easier exchange workflows are valued, especially in benign strictures and certain pancreatic duct applications. The relative attractiveness of each product type is not static; it shifts with clinical guidelines, operator training, cost-containment pressures, and the introduction of devices that blend deliverability improvements with durability advantages. The full report evaluates these trade-offs without reducing them to simplistic share declarations, providing instead a structured view of how application needs, procedural economics, and device attributes intersect across segments.
This is precisely where disaggregated intelligence becomes indispensable. Aggregate revenue trajectories can mask significant divergence in segment performance, and assuming uniform growth across regions, applications, or product types introduces material risk to forecasting and resource allocation. The complete study isolates these layers while intentionally withholding exact segment percentages and revenue figures in this preview, reserving that level of granularity for subscribers and purchasers who require it for pricing, capacity, and geographic prioritization decisions.
Competitive Architecture and Recent Strategic Moves
The competitive landscape reflects a mix of large diversified medtech players, focused endoscopic device specialists, and emerging innovators pursuing differentiated material and design platforms. Competitive dynamics are shaped not only by installed base and sales coverage, but also by regulatory timing, procedural compatibility, hospital procurement consolidation, and the ability to demonstrate clinical and operational value in high-throughput endoscopy environments.
Among the most prominent participants, Boston Scientific Corporation maintains a broad portfolio spanning plastic and self-expanding metal biliary stents, including the Advanix biliary plastic stents and WallFlex biliary stents for management of biliary strictures, stone disease, and malignancies, alongside pancreatic stent offerings. The company’s scale and procedural ecosystem integration give it significant commercial leverage, and recent product-level actions underscore a continued emphasis on deliverability and indication breadth. In October 2025, Boston Scientific reported receiving FDA 510(k) clearance and CE Mark approval for Advanix Biliary Plastic Stents with enhanced deliverability features, followed by launch activity in Europe and international markets with a US rollout planned.
Cook Medical is another central figure, manufacturing plastic and metal biliary and pancreatic stents that include the Cotton-Huibregtse biliary stents and a range of ERCP-compatible pancreatic duct stents for drainage and stricture management. Olympus Corporation contributes through its EndoTherapy biliary and pancreatic stent offerings and has actively expanded its portfolio footprint by entering an exclusive international distribution agreement with W. L. Gore & Associates in October 2025 for the GORE VIABIL Biliary Endoprosthesis, broadening options for endoscopic placement in biliary applications. Medtronic Plc supplies biliary and pancreatic stents within its gastrointestinal endoscopy portfolio, supporting ERCP procedures for duct drainage and obstruction relief, while CONMED Corporation offers biliary and pancreatic stents within its endoscopic technologies for therapeutic ERCP interventions.
Beyond the established leaders, the field includes specialist and emerging players whose strategies are increasingly defined by regulatory milestones and product differentiation rather than volume alone. Q3 Medical Devices Ltd., operating with a presence in Ireland and the United States, has focused attention on the ARCHIMEDES fully biodegradable biliary and pancreatic stents for temporary drainage of obstructed ducts. The company received FDA 510(k) clearance in July 2025 for the ARCHIMEDES Biodegradable Pancreatic Stent, and in January 2026, UI Health Care performed the nation’s first procedure using the FDA-approved device during ERCP for pancreatic duct drainage. This kind of milestone matters strategically: biodegradable platforms can address clinical pain points around stent retrieval and repeat interventions, but their commercial trajectory depends on procedure adoption, reimbursement interpretation, and demonstrated comparative value against conventional options.
Additional participants reinforce the breadth of the competitive arena. Medi-Globe Corporation produces Endoflux Biliary & Pancreatic Stent Sets and received FDA 510(k) clearance in April 2026 for these devices. Abbott Laboratories markets biliary and pancreatic stents within its structural heart and endoscopy-related offerings, while Becton, Dickinson and Company provides biliary stents within its interventional and surgical product lines for pancreaticobiliary procedures. Blue Neem Medical Devices Pvt. Ltd., based in Bengaluru, India, manufactures pancreatic stents designed for endoscopic drainage of obstructed pancreatic and biliary ducts with global distribution reach. The presence of both globally scaled vendors and regionally oriented manufacturers contributes to a market environment where local service capacity, price positioning, and product specialization can be as influential as headline brand recognition.
This preview intentionally summarizes the strategic posture of the competitive set without breaking down revenue attribution or precise share structure by company. The full report provides a detailed competitive analysis, including concentration metrics and the operational moves that are reshaping positioning across regions and segments. Given that the market exhibits meaningful concentration, even small advantages in clearance timing, delivery-system performance, or indication coverage can produce disproportionate competitive effects. Accessing the complete study allows decision-makers to evaluate these dynamics with the specificity required for partnership assessment, competitive intelligence, and product roadmap calibration.
What the Full Research Delivers: Decision-Ready Intelligence
The Worldwide Pancreatic and Biliary Stent Market report is designed as an operational compass rather than a static snapshot. It integrates historical performance, base-year market sizing, and a multi-year forecast to support scenario planning, while layering in the market dynamics, competitive actions, and application-level context needed to translate numbers into strategy.
Key deliverables and analytical components include:
- A structured market overview with base-year valuation, historical trend analysis from 2020 through 2025, and a forecast model extending to 2032, enabling executives to test growth assumptions against multiple demand and pricing scenarios.
- Macro-to-micro segmentation coverage that separates regional demand patterns, product-type architecture, and application-level usage without relying on blunt averages, so that strategists can identify where growth is structurally supported versus where it is dependent on incremental adoption.
- Competitive profiling of leading participants, with attention to product portfolios, procedural alignment, regulatory positioning, and recent commercial or clearance events that affect near-term market behavior.
- An examination of market concentration and the strategic implications of a top-heavy competitive field, helping leaders evaluate barriers to entry, share-gain feasibility, and the relative value of product differentiation versus commercial scale.
- Contextual analysis of regulatory requirements, reimbursement coding frameworks, material and design considerations, and procedural economics, providing the connective tissue between clinical practice and commercial outcomes.
- Recent development tracking across key players, including clearance events, distribution agreements, launch activity, and first-in-nation procedural use cases, to inform timing decisions and competitive response planning.
Crucially, the report is organized to support practical use cases: market-entry assessment, portfolio prioritization, pricing and procurement strategy, partnership and distribution evaluation, and competitive response planning. It is written for teams that must reconcile clinical realities with commercial constraints, and that need to distinguish between trend-level momentum and segment-specific opportunity.
Strategic Implications for 2026 and the Road to 2032
For executives planning around 2026, several strategic imperatives stand out from the market’s architecture. First, growth management must be indication-aware. The prominence of biliary stenosis, pancreatic cancer, and chronic pancreatitis means that demand drivers differ substantially by clinical pathway, surgical oncology volume, ERCP utilization, and palliative care norms. Strategies that assume uniform expansion are likely to misallocate effort and capital.
Second, product strategy should account for the durability-versus-cost-and-exchange trade-off that shapes stent selection in practice. Innovations that improve deliverability, reduce migration, support temporary drainage, or simplify procedural workflow can gain traction even in a market where established product types remain deeply embedded. The recent clearance and launch activity around enhanced plastic stent deliverability, biodegradable pancreatic stent platforms, and new biliary stent sets illustrates how targeted differentiation is being pursued across the field.
Third, competitive positioning will increasingly depend on the ability to combine regulatory readiness, procedural compatibility, and commercial execution. Companies that can secure timely clearances, align with hospital outpatient and endoscopy-center economics, and support clinician adoption with credible evidence and service infrastructure are better placed to convert market growth into durable share. At the same time, the concentrated nature of the market means incumbents have room to defend positions through portfolio breadth and procedural integration, while challengers must identify specific unmet needs and win them decisively.
Finally, forecasts should be treated as scenario anchors rather than fixed predictions. Procedure behavior, reimbursement interpretation, supply conditions, and clinical guideline evolution can all shift the pace of adoption for individual product types and applications. The complete research provides the analytical scaffolding needed to adjust assumptions as the environment changes, ensuring that strategic plans remain robust under multiple futures.
Accessing the Complete Intelligence
This article has outlined the structural forces, competitive dynamics, and growth trajectory shaping the worldwide pancreatic and biliary stent market while deliberately leaving the most decision-critical segmentation figures, regional breakdowns, application splits, and product-type revenue details inside the full study. That approach is intentional. The value of this market research lies not only in confirming that the sector is expanding, but in helping leaders understand where growth is concentrated, which device strategies are gaining procedural traction, and how regulatory and reimbursement realities alter the commercial math.
For organizations preparing 2026 budgets, prioritizing indications, evaluating partnerships, or assessing competitive threats, the complete report offers the depth required to convert direction into execution. We invite you to visit the source webpage for the Worldwide Pancreatic and Biliary Stent Market research to access the full dataset, detailed segmentation intelligence, competitive profiles, and scenario-ready forecast tables. In a market where margin discipline and product differentiation increasingly determine winners, precision in the underlying numbers is not a luxury—it is the foundation of sound strategy.
Worldwide Tubular Metal Biliary Stents Market
For detailed analysis of this topic, please visit the official page: Worldwide Pancreatic and Biliary Stent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com