

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Offshore Riser Systems Hit $4.12B in 2025, Projected to Soar to $6.41B by 2032

Strategic Intelligence for the Offshore Energy Transition: Navigating the 2026-2032 Riser Systems Landscape
The offshore oil and gas industry stands at a critical inflection point. As upstream capital expenditure faces renewed discipline amid price volatility and evolving energy transition mandates, the offshore riser systems market has become a strategic battleground. Risers—the critical umbilical links connecting floating production systems, drilling rigs, and subsea infrastructure to surface facilities—are no longer mere commoditized components. They represent engineering-intensive, high-value assets where material quality, fatigue resistance, dynamic performance, and supply chain reliability directly dictate project economics and operational safety.
Worldwide Offshore Riser Systems Market
PW Consulting's latest Worldwide Offshore Riser Systems Market study delivers a comprehensive, data-driven assessment designed explicitly to equip corporate strategists, procurement leaders, and capital allocators with the intelligence required to navigate the 2026-2032 forecast horizon. This article previews the strategic architecture of the report, demonstrating how its analytical framework translates into actionable decision support for enterprises operating in one of the most technically demanding segments of the offshore energy sector.
Market Trajectory: From Recovery to Sustained Expansion
The global offshore riser systems market has demonstrated remarkable resilience and structural growth over the past half-decade. Valued at approximately $3.1 billion in 2020, the market expanded steadily to reach $4.1 billion by 2025, reflecting a compound trajectory shaped by deepening water exploration, aging field redevelopment, and the incremental electrification and digitalization of subsea infrastructure. Our base-year analysis anchors the forecast period at 2026, with projected revenues scaling to $4.4 billion that year and continuing upward toward $6.4 billion by 2032.
This expansion is underpinned by a projected compound annual growth rate of 6.52 percent across the forecast window. Such growth is not merely cyclical revival but structurally driven by several converging realities: the persistent shift of new field development toward deepwater and ultra-deepwater regimes, the industry's growing reliance on extended-reach subsea production architectures, and the increasing complexity of well access in pre-salt, deep shelf, and frontier sedimentary basins. Companies that fail to align their supply chain planning, technology roadmaps, and commercial positioning with this growth curve risk ceding strategic advantage to more agile competitors.
Importantly, the forecast does not assume uniform growth across all segments. Production risers dominate volume and revenue contribution, reflecting the market's prioritization of long-life production architectures over short-cycle drilling campaigns. Drilling and workover/completion risers maintain substantial share, driven by the ongoing need for well intervention, field life extension, and high-pressure well access in both shallow and deepwater settings. The report decomposes these dynamics with granularity, revealing how application mix, water depth classification, and regional project pipelines collectively shape revenue allocation and technology demand profiles.
Segmentation Architecture and Technology Divergence
A defining feature of this study is its multi-dimensional segmentation framework, which maps market value across product type, water depth classification, and regional deployment zones. Rather than treating risers as a monolithic category, the analysis distinguishes between production risers, drilling risers, and workover/completion risers, each carrying distinct engineering requirements, procurement cycles, and margin structures.
Production risers command the largest revenue share within the product taxonomy, reflecting their integral role in long-duration floating production operations where fatigue life, corrosion management, and dynamic movement compensation are paramount. Drilling risers follow as a substantial segment, driven by deepwater exploration and development drilling campaigns that demand high-pressure containment, robust tension management, and rapid deployment/retrieval capabilities. Workover and completion risers, while smaller in aggregate value, represent a critical enabler for field life extension and brownfield redevelopment strategies that are increasingly prioritized as operators seek to maximize legacy asset returns.
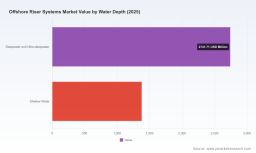
By water depth, the market reveals a pronounced skew toward deepwater and ultra-deepwater applications, which account for the majority of segment value. This concentration underscores the technological premium associated with riser systems engineered for extreme hydrostatic pressures, complex vessel motion dynamics, and extended tie-back distances. Shallow water riser applications, while still significant, increasingly compete within price-sensitive procurement environments where standardization and supply chain efficiency take precedence over bespoke engineering customization. The report provides detailed scrutiny of how these depth-based divergences influence material selection, connector technology, buoyancy module specification, and lifecycle cost modeling.
Regional Dynamics and Geopolitical Considerations
Geographic distribution of riser system demand reflects the uneven geography of offshore hydrocarbon development and the varying maturity of regional project pipelines. Latin America emerges as a dominant regional contributor, propelled by pre-salt basin development, deepwater export infrastructure expansion, and large-scale floating production initiatives. North America sustains robust demand rooted in Gulf of Mexico deepwater activity, legacy field redevelopment, and the periodic re-evaluation of stranded resources under evolving regulatory and fiscal frameworks.
Europe, particularly the Norwegian Continental Shelf and adjacent North Sea basins, continues to represent a sophisticated demand center characterized by stringent integrity management standards, high-specification subsea architectures, and strong emphasis on emissions reduction and operational efficiency. Africa and the Asia Pacific region each present distinct growth vectors: African projects often involve deepwater frontier exploration and export-infrastructure build-out, while Asia Pacific demand is shaped by mixed shallow-to-deepwater activity, national oil company procurement cycles, and the gradual introduction of floating production concepts in traditionally shallow-water operating environments.
Middle East represents an emerging but currently smaller share of riser system demand, with activity concentrated in specific subsea tie-back and enhanced recovery applications. The report avoids superficial regional generalizations, instead examining how local content requirements, vessel availability, installation campaign scheduling, and logistics corridors create differentiated value propositions for suppliers and contractors operating across these zones.
Competitive Landscape: Concentration, Capabilities, and Differentiation
Market concentration remains moderately consolidated, with the top three participants collectively commanding a significant share of total market value and the top five firms extending that reach further. This concentration reflects the high barriers to entry inherent in the riser systems sector: the need for specialized manufacturing capabilities, certified material supply chains, engineering validation under dynamic loading conditions, and established relationships with major operators and EPCI contractors.
Leading participants such as TechnipFMC and Subsea 7 anchor the competitive environment through integrated SURF and URF offerings that span design, manufacture, and installation of flexible and rigid riser systems for complex deepwater architectures. Their strategic positioning increasingly emphasizes lifecycle service, integrity management, and the ability to bundle riser solutions within broader export pipeline and subsea production system contracts. OneSubsea, operating as a joint venture with complementary capabilities, brings focused expertise in high-pressure/high-temperature production architectures and fatigue-resistant riser design, particularly relevant for harsh-environment and ultra-deepwater developments.
Baker Hughes and National Oilwell Varco contribute specialized riser technologies spanning drilling riser systems, buoyancy modules, strakes, fairings, and riser running tools that address the mechanical and operational demands of floating drilling and production units. Oil States International reinforces its position through proprietary flex-joint and high-pressure drilling riser products, alongside connector technologies critical to riser string integrity. Vallourec's premium seamless steel tubular solutions provide essential input for steel catenary riser and hybrid riser applications, while Aquaterra Energy and Balmoral Offshore Engineering address niche but operationally vital segments of drill riser systems and buoyancy modules for jack-up and floating deployments. Weatherford's mechanized riser running services and Saipem's high-performance flexible riser and EPCI capabilities round out a competitive field where differentiation increasingly arises from service integration, technical problem-solving, and execution reliability rather than hardware commoditization alone.
The report includes detailed company profiles, capability assessments, and strategic positioning analyses that enable readers to compare competitors across technology breadth, geographic reach, project execution track record, and likely response patterns to emerging market stimuli such as regulatory changes, material cost fluctuations, and major contract awards.
Recent Industry Developments: Signals for Strategic Positioning
Several recent developments illuminate the trajectory of the riser systems market and underscore the need for proactive strategic planning. In late 2025, TechnipFMC secured a substantial EPCI contract for the Coral North FLNG development offshore Mozambique, encompassing flexible flowlines and risers in approximately 2,000-meter water depth—a project that exemplifies the continued momentum of ultra-deepwater floating production architectures. Around the same period, Subsea 7 obtained an EPCI contract from ConocoPhillips for redevelopment of previously produced fields offshore Norway, with offshore campaigns projected for 2027-2028, highlighting the growing importance of brownfield life-extension and subsea infrastructure refurbishment.
In November 2025, Allseas was awarded a contract by Enbridge for installation of deepwater export pipelines in the US Gulf of Mexico, integrated with steel catenary risers, reinforcing the interconnected nature of riser demand with broader export infrastructure build-out. On the regulatory front, the American Petroleum Institute published the third edition of API Standard 2RD in October 2025, updating design and integrity management requirements for dynamic risers on floating production systems including spars, semi-submersibles, and tension-leg platforms. This standard revision directly affects riser qualification, inspection protocols, and engineering reference assumptions, with cascading implications for both suppliers and operators.
More recently, in February 2026, Petrobras issued what has been characterized as the largest-ever tender for subsea systems, planning contracts for over 6,000 kilometers of rigid and flexible risers, umbilicals, and related infrastructure. Such a procurement event signals a major demand catalyst that will reverberate across supplier capacity planning, material procurement strategies, and installation vessel scheduling. The report examines these and other recent developments to help readers anticipate contract cycles, competitive bidding dynamics, and technology requirement shifts that may affect their strategic positioning.
Operational and Macroeconomic Dynamics: Risk, Cost, and Standards
Strategic decision-making in the riser systems market cannot be divorced from broader operational and macroeconomic contexts. Global upstream E&P capital expenditure is projected to decline modestly year-on-year in 2026 amid oil price volatility below sixty dollars per barrel, with spending discipline favoring selective offshore projects that demonstrate clear returns and operational resilience. This environment does not eliminate riser system demand but rather sharpens the focus on value engineering, lifecycle cost optimization, and technology selection that minimizes total cost of ownership rather than simply minimizing upfront hardware cost.
Raw material dynamics introduce additional complexity. Chinese carbon steel pipe exports, a primary input for steel catenary and drilling risers, are projected in a specific price range per ton FOB for the first quarter of 2026, while benchmark steel rebar prices exhibit modest volatility with slight monthly increases. These material cost signals affect procurement timing, contract structuring, and margin management for manufacturers and contractors alike. The study integrates such cost indicators into its segment-level analysis, helping readers understand how input cost fluctuations may impact pricing strategies, inventory planning, and supplier negotiations across different riser types and regional markets.
Regulatory and standards evolution continues to shape technical requirements. Alongside the updated API 2RD, the ISO 13624 series and API Specification 16F remain core standards governing marine drilling riser systems and equipment, defining safety, performance, and testing parameters that influence product qualification and operational compliance. Companies that proactively align their engineering practices, inspection regimes, and documentation frameworks with evolving standards reduce the risk of redesign delays, contract disqualification, and operational non-conformance. The report provides a consolidated overview of the standards landscape and examines how regulatory developments intersect with technology design, procurement, and integrity management practices.
What the Full Study Delivers: A Toolkit for Executive Decision-Making
This article has outlined the strategic contours of the Worldwide Offshore Riser Systems Market analysis. The full report goes significantly deeper, offering a structured intelligence toolkit designed for executives, strategy teams, and commercial leaders who require precise, actionable data rather than generic market commentary.
Offshore ROV Market
Inside the study, readers will find:
- Detailed historical revenue analysis for the base period and forward-looking revenue projections through 2032, calibrated to realistic project pipeline assumptions and macroeconomic scenarios.
- Granular segmentation data across product types, water depth categories, and regional markets, enabling portfolio planning, market entry assessment, and revenue forecasting at a level of precision not available in summary formats.
- Comprehensive competitive profiling that evaluates the strategic positioning, capability breadth, and recent project activity of leading riser system participants, with implications for partnership, procurement, and competitive response strategies.
- Analysis of recent contract awards, tender issuances, and regulatory updates, contextualized within market dynamics to help readers anticipate demand catalysts and compliance shifts.
- Integration of raw material cost indicators and macro expenditure trends into segment-level observations, supporting cost planning and sensitivity analysis for procurement and manufacturing decision-makers.
- Strategic implications and actionable recommendations tailored to operators, EPC contractors, riser system manufacturers, and technology suppliers seeking to align their commercial and operational strategies with the market's trajectory.
The report is structured to support scenario planning, allowing readers to evaluate how shifts in deepwater project cadence, regulatory requirements, material costs, or competitive entry might alter market outcomes over the forecast period. By connecting macro trends to segment-level realities, the study provides a foundation for informed capital allocation, technology investment, and supply chain strategy.
Why This Intelligence Matters in 2026 and Beyond
The offshore riser systems market is not a static commodity arena. It is a technically sophisticated, capital-intensive, and strategically consequential segment where engineering performance, supply chain reliability, regulatory compliance, and commercial positioning converge. The projected growth trajectory toward the mid-2030s offers substantial opportunity, but realizing that opportunity requires more than passive participation. It demands disciplined analysis of segment dynamics, proactive engagement with standards evolution, careful management of material cost exposure, and strategic positioning relative to a competitive field that includes both integrated SURF/URF providers and specialized technology suppliers.
PW Consulting's Worldwide Offshore Riser Systems Market study equips decision-makers with the depth, granularity, and strategic context needed to navigate this complexity. The executive summary and high-level figures presented in this article offer a glimpse of the analysis framework, but the complete intelligence—segment-level revenue breakdowns, regional demand mapping, competitive capability assessments, and forward-looking strategic recommendations—is available only through full access to the study. For organizations preparing procurement strategies, evaluating partnership opportunities, planning technology investments, or assessing market entry, the complete dataset and accompanying analysis provide the strategic foundation necessary to make informed, timely decisions in a rapidly evolving offshore environment.
To access the full report, including detailed segmentation data, competitive profiles, and strategic implications tailored to your organization's needs, please visit our research portal to download the complete Worldwide Offshore Riser Systems Market study.
For detailed analysis of this topic, please visit the official page: Worldwide Offshore Riser Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com