

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Industrial Flexible Hose Market Hits $15.74B in 2025, Forecasting 5.12% CAGR to 2032

Strategic Imperatives in the Global Industrial Flexible Hose Market 2026-2032
The global industrial landscape is undergoing a profound transformation driven by infrastructure expansion, energy transition projects, and stringent safety regulations. At the heart of fluid transfer systems lies the industrial flexible hose, a critical component that ensures operational continuity across sectors ranging from oil and gas to food processing. For executives and strategy leaders, understanding the trajectory of this market is not merely about tracking sales figures; it is about anticipating supply chain resilience, material innovation, and competitive positioning. This analysis draws upon comprehensive research to outline the strategic value of the Worldwide Industrial Flexible Hose Market study, offering a roadmap for decision-makers navigating the forecast period from 2026 to 2032.
Market Trajectory and Macro Economic Drivers
The industrial flexible hose market has demonstrated consistent resilience and growth over the past half-decade. Historical data indicates a steady climb in revenue, with the market valuation rising from approximately 12,050 million USD in 2020 to an estimated 15,744 million USD in 2025. This upward trend reflects the compounding effects of industrial automation, increased hydraulic system complexity, and the replacement cycle of aging infrastructure. As we look toward the forecast period, the momentum is expected to continue, with projected revenues reaching over 22,331 million USD by 2032.
The compound annual growth rate (CAGR) during the forecast period is estimated at 5.12 percent. This moderate yet robust growth rate suggests a maturing market that is still expanding due to fundamental industrial demand rather than speculative bubbles. Several macro drivers are fueling this expansion. Notably, global oil and gas capital expenditure is projected to hit significant levels in 2025, directly boosting demand for chemical-resistant flexible hoses capable of withstanding harsh environments. Additionally, the manufacturing sector continues to prioritize efficiency and safety, driving adoption of high-performance hose assemblies that reduce downtime and maintenance costs.
However, growth is not without friction. Raw material volatility remains a key concern for procurement leaders. Natural rubber prices averaged around 1,800 USD per metric ton in the fourth quarter of 2024, marking an increase due to supply constraints in Southeast Asia. Similarly, PTFE resin prices rose significantly driven by competing demand from the semiconductor sector. These input cost pressures necessitate strategic sourcing and may influence pricing strategies across the value chain. Furthermore, regulatory updates such as the ISO 1436 standard revisions impose stricter requirements on rubber hoses used in petroleum-based hydraulic fluids, forcing manufacturers to adapt compliance protocols quickly.
Segmentation Dynamics and Operational Implications
Understanding where value is generated within the market is crucial for targeted investment. The market structure is defined by distinct segmentation splits including region, material, and end-user industry. In terms of material composition, the landscape is diversified. Rubber continues to hold a significant share due to its versatility and durability in high-pressure applications. PVC remains a cost-effective solution for lighter duty transfers, while Polyurethane is gaining traction for its abrasion resistance. Metal hoses are essential for high-temperature and corrosive environments, and composite materials are emerging for specialized technical applications.
Industrial Hose Market
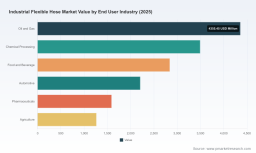
End-user industry segmentation reveals where the demand originates. The oil and gas sector remains a dominant force, driven by upstream and downstream fluid transfer needs. Chemical processing follows closely, requiring hoses that meet rigorous safety and contamination standards. Food and beverage applications demand hygienic designs, while the automotive and agriculture sectors rely on durable hydraulic and fluid lines. Pharmaceuticals require high-purity solutions, often pushing the adoption of specialized materials like PTFE. Each segment presents unique technical requirements and procurement cycles, making a one-size-fits-all strategy ineffective.
Regional dynamics also play a pivotal role in market access. Asia Pacific represents a substantial portion of market activity, reflecting rapid industrialization and infrastructure development. North America and Europe maintain mature markets with high emphasis on replacement demand and regulatory compliance. Latin America and the Middle East and Africa offer growth opportunities tied to energy exploration and agricultural output. For multinational corporations, aligning distribution networks and local manufacturing capabilities with these regional variances is essential for capturing market share.
Competitive Landscape and Strategic Positioning
The market is characterized by a fragmented yet competitive landscape. The concentration of market share among the top players indicates a competitive environment where differentiation is key. The top three companies account for roughly 18.45 percent of the market, while the top five hold approximately 28.12 percent. This suggests that while large players dominate, there is significant room for specialized manufacturers and regional leaders to thrive through niche specialization and service excellence.
Several key companies define the competitive edges of this industry. Gates Corporation, headquartered in Denver, is a leading global manufacturer of industrial rubber and thermoplastic hoses, particularly strong in mining and construction sectors. Parker Hannifin Corporation, based in Cleveland, provides a comprehensive range of hydraulic and pneumatic solutions, recently enhancing its portfolio with the launch of the 7100FC thermoplastic hose series for mining and construction in March 2024, featuring enhanced abrasion resistance. Eaton Corporation, from Dublin, offers Aeroquip branded hoses for heavy-duty applications and exhibited Weatherhead hydraulic hoses at MINExpo International in September 2024.
Continental AG and Trelleborg Group represent significant European strength. Continental's ContiTech division focuses on conveying liquids and gases in chemical and petrochemical industries. Trelleborg specializes in polymer-based hoses for high-temperature and corrosive media, showcasing new Trigear hybrid hoses at the Offshore Technology Conference in April 2024 for subsea applications. In Asia, Yokohama Rubber and Bridgestone Corporation leverage their material science expertise for marine and construction applications. Bridgestone offers industrial hoses through its Firestone brand for air and chemical transfer.
Worldwide Industrial Flexible Hose Market
Specialized manufacturers also play a critical role. Alfagomma from Italy manufactures hydraulic hoses for construction machinery, while Manuli Hydraulics produces thermoplastic and hybrid hoses for mining and oil and gas. Goodall Rubber Company in the USA custom manufactures rubber and PVC hoses for chemical and food industries. Novaflex in Canada produces ducting and rubber hoses for ventilation and material handling. Aflex Hose Ltd in the UK specializes in PTFE flexible hoses for high-purity applications. Regional players like Ryco Hydraulics in Australia and Pacific Hoseflex supply critical support for Asia-Pacific markets and high-pressure industrial uses respectively. Strategic partnerships, acquisitions, and product innovation among these entities will shape the competitive intensity in the coming years.
Industry Dynamics and Risk Management
Beyond the raw numbers, the operational environment is shifting. Labor costs in key manufacturing hubs are rising. For instance, US manufacturing labor costs for hose assembly increased by 4.2 percent to 28.50 USD per hour in 2024. This trend pressures margins and encourages automation in assembly lines. Companies must evaluate whether near-shoring or investing in automated production technology offers a better return on investment compared to traditional labor-intensive models.
Innovation cycles are accelerating. Recent developments highlight a focus on durability and specific application performance. Gates Corporation introduced the MegaBlast mining hose in November 2023 with 20 percent higher burst pressure for underground operations, addressing safety and efficiency in extraction industries. These product launches signal to the market that performance metrics are shifting toward higher pressure ratings and longer service life. Companies that fail to align their R and D pipelines with these emerging performance standards risk losing relevance in high-value segments.
Supply chain security is another dynamic element. The reliance on specific raw materials like natural rubber and PTFE creates vulnerability to geopolitical and environmental disruptions. Mitigation strategies involve diversifying supplier bases and investing in alternative material research. Furthermore, regulatory compliance is not static. The update to ISO 1436 requires ongoing vigilance to ensure product certifications remain valid across different jurisdictions, especially for exporters dealing with multiple regulatory frameworks.
Strategic Value of Comprehensive Market Intelligence
For organizations operating in this space, generic market overviews are insufficient. Decision-makers require granular intelligence that connects market size data with actionable strategy. The full research report provides detailed segmentation analysis that goes beyond high-level aggregates. It offers specific insights into volume trends, pricing mechanisms, and regional growth hotspots that are not visible in summary data. Access to this depth allows procurement teams to negotiate better contracts, sales teams to identify untapped territories, and R and D departments to prioritize technologies with the highest commercial potential.
The report also covers competitive profiling in depth, analyzing the strategic moves of the key companies mentioned earlier. Understanding the product launch cadence and trade show presence of competitors like Parker, Trelleborg, and Gates helps in benchmarking internal performance and anticipating market shifts. Moreover, the inclusion of raw material price trends and labor cost data enables more accurate financial forecasting and risk assessment models.
Investing in this level of market intelligence is an investment in operational agility. In a market projected to grow to over 22 billion USD by 2032, the difference between market share gain and loss often comes down to timing and precision. Knowing exactly which material segments are expanding in which regions, or how regulatory changes will impact specific end-user industries, allows companies to pivot resources before competitors react. The 5.12 percent CAGR indicates steady growth, but the distribution of that growth is uneven across segments and geographies.
Conclusion and Call to Action
The Worldwide Industrial Flexible Hose Market presents a landscape of stable growth tempered by complex operational challenges. From raw material volatility to regulatory compliance and competitive innovation, the factors influencing success are multifaceted. While the aggregate data suggests a healthy trajectory with revenues climbing toward 22,331 million USD by 2032, the real value for enterprise strategy lies in the details beneath the surface. Understanding the specific drivers in oil and gas capex, the implications of ISO standards, and the competitive maneuvers of industry leaders is essential for crafting robust strategies.
To fully capitalize on the opportunities within this forecast period, stakeholders need access to the complete dataset and analytical frameworks provided in the full study. The summary provided here outlines the structural dynamics and competitive environment, but the specific segmentation splits, precise regional valuations, and detailed company profiling contained in the full report are critical for executable planning. We invite you to access the source webpage to obtain the comprehensive intelligence required to navigate the 2026-2032 period with confidence. Securing this data is the first step toward optimizing your supply chain, refining your product portfolio, and securing a competitive advantage in the global industrial flexible hose market.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Flexible Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com