

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Composite Railroad Tie Market Hits $943.15M in 2025, Projected 6.12% CAGR Through 2032

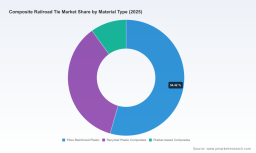
Navigating the Next Decade: Strategic Insights from the Worldwide Composite Railroad Tie Market
The global railroad infrastructure sector stands at a pivotal intersection of sustainability mandates, lifecycle cost optimization, and material innovation. For executives, capital allocators, and procurement leaders operating in 2026, the decision to commit to traditional timber, concrete, or advanced composite sleepers is no longer a purely technical evaluation. It is a strategic imperative shaped by regulatory shifts, supply chain resilience requirements, and rapidly maturing field validation data. The recently published Worldwide Composite Railroad Tie Market research report delivers a comprehensive intelligence framework designed to translate these complex forces into actionable strategy. This overview illuminates the report's architectural depth and its direct relevance to enterprise decision-making in the current operating environment.
Worldwide Composite Railroad Tie Market
Market Trajectory and the 2026 Inflection Point
Tracking the evolution of the composite railroad tie segment from 2020 through the present reveals a clear acceleration curve. Over the past half-decade, market valuation expanded from a baseline of approximately 712 million USD to a projected 2026 valuation of roughly 1,001 million USD. The trajectory continues its upward momentum across the forecast horizon, reaching an estimated 1,429 million USD by 2032, underpinned by a compound annual growth rate of 6.12 percent. These figures are not merely illustrative of sector growth; they signal a structural reallocation of capital toward materials that offer extended service intervals, reduced maintenance footprints, and compatibility with circular economy objectives.
For operators managing extensive network portfolios, the inflection represented by this growth curve demands rigorous scenario planning. The transition from reactive replacement cycles to proactive infrastructure hardening requires visibility into how material adoption scales across different track classifications, climate zones, and freight/passenger mix profiles. The report dissects the historical performance data alongside forward-looking utilization models, enabling leadership teams to calibrate procurement timing, capex phasing, and vendor qualification roadmaps against realistic adoption curves rather than speculative projections.
Strategic Content Architecture: From Data to Execution
A market intelligence publication only creates enterprise value when it bridges the gap between macro indicators and ground-level operational variables. This research report is engineered to function as a working decision-support system. The analysis begins with a granular examination of material composition dynamics, evaluating how fiber-reinforced polymer formulations, recycled plastic composite architectures, and rubber-based composite variants perform across load-bearing requirements, environmental exposure profiles, and installation logistics. Rather than treating material categories as static silos, the report maps performance differentiators against real-world track conditions, providing clarity on where specific composite formulations deliver defensible return on investment.
The analytical framework extends into application-specific deployment modeling. Mainline railway corridors, transit and metro networks, and industrial and mining environments each impose distinct thermal, vibration, and dwell-time stresses on sleeper systems. The report correlates historical installation data with operational outcomes, helping engineering and asset management teams anticipate where composite ties can compress maintenance cycles, reduce track geometry degradation, and extend the interval between replacement campaigns. This application-level perspective is critical for procurement teams evaluating whether composite integration aligns with the duty cycles of specific line segments or rolling stock profiles.
Beyond material and application mapping, the publication integrates regulatory and sustainability overlays that are reshaping procurement evaluation criteria. Environmental compliance frameworks, creosote treatment phase-outs, and corporate decarbonization commitments are no longer peripheral considerations. They now function as primary drivers of specification adjustments and vendor selection matrices. The report quantifies the directional influence of these policy vectors on procurement behavior, giving executives the context needed to anticipate specification changes before they disrupt bidding timelines or create supply gaps.
Competitive Dynamics and Ecosystem Positioning
The composite railroad tie landscape is characterized by a concentrated yet highly differentiated competitive field. The report provides detailed profiling of the organizations actively shaping technology standards, scaling production capacity, and securing specification approvals across major rail networks. Companies such as Evertrak LLC, Sicut Enterprises, Pioonier GmbH, and TieTek have established distinct market positions through combinations of patented processing methods, certification achievements, and targeted deployment campaigns in high-decay or heavy-haul environments. Their track records illustrate how material engineering, regulatory compliance, and field trial execution converge to build commercial momentum.
International players further complicate and enrich the competitive mosaic. AGICO's cost-competitive synthetic sleeper programs for metro and high-speed applications, Triton Group's fiber-reinforced polymer portfolio, and Sekisui Chemical's long-standing presence in synthetic sleeper technology each demonstrate how regional manufacturing capabilities and material specialization influence specification adoption. Organizations such as Axion Structural Innovations, IntegriCo Composites, Lankhorst Mouldings, and Vossloh contribute additional layers of differentiation, whether through recycled-content formulations, concrete-composite hybrid offerings, or CO2-optimized design approaches tailored to project-specific requirements.
The report does more than catalog these entities. It evaluates coordination patterns, partnership architectures, and certification pathways that determine which suppliers can scale reliably in Class I railroad environments, transit authorities, and industrial freight corridors. By examining the intersection of proprietary technology claims, field trial outcomes, and procurement qualification status, the analysis helps sourcing leaders distinguish between marketing narratives and commercially deployable solutions. This distinction is essential when evaluating long-term supply continuity, warranty risk, and total cost of ownership across multi-year infrastructure programs.
Fiberglass Composite Rail Ties Market
Recent Developments and Strategic Implications for 2026
Several recent events have materially altered the operating context for composite tie deployment, and the report incorporates these developments into its forward-looking assessment. In April 2026, Progress Rail, as a Caterpillar company, entered into an agreement with Triton Group to serve as the exclusive seller and marketer of Triton's composite railroad tie technology. This arrangement couples specialized materials expertise with broader engineering capabilities and global distribution reach, signaling a strategic push to improve track reliability, reduce environmental impact, and lower lifecycle costs through coordinated commercialization.
Field validation activity has also intensified. A large-scale trial involving Norfolk Southern in 2025 saw the installation of approximately 30,000 glass-reinforced polymer composite sleepers sourced from multiple manufacturers, achieving a 100 percent installation success rate at conventional deployment speeds. Additional installation activity noted with BNSF and CSX, alongside pending approvals for Union Pacific, reflects a broader pattern in which major Class I railroads are expanding trial scope and moving toward broader adoption to address wood tie decay in high-humidity regions while targeting reduced long-term maintenance and replacement expenditures.
Capital and supply chain movements further illustrate the sector's maturation. In early 2025, Sumitomo Corporation made a strategic investment in Evertrak to support expanded production capacity for glass fiber reinforced polymer composite ties manufactured from recycled plastics, reinforcing the alignment between sustainability goals and North American infrastructure demand. Meanwhile, procurement policy shifts in the United Kingdom, including the termination of hardwood and softwood sleeper procurement by Network Rail executive leadership and the subsequent capability transfer to composite alternatives following full product approval and track trials, demonstrate how regulatory and environmental strategies can rapidly reshape supplier landscapes and create new specification defaults.
For strategy teams, these developments are not isolated news items. They represent structural signals about where specification authority is moving, which partnerships are likely to influence distribution and service coverage, and how quickly field validation can translate into procurement volume. The report synthesizes these dynamics into scenario-based guidance, allowing decision-makers to evaluate how partnership structures, trial outcomes, and policy transitions might affect supply availability, lead times, and competitive positioning over the forecast period.
Why This Intelligence Matters for Decision-Makers
Enterprise leaders evaluating infrastructure material strategies in 2026 need more than headline growth figures. They need to understand where concentration risk resides, how certification and performance standards filter supplier eligibility, and which operational variables determine whether composite integration delivers the expected reduction in maintenance exposure. The market exhibits meaningful concentration, with the top three firms accounting for a substantial share of revenue and the top five firms extending that coverage further. This concentration has direct implications for procurement diversification, supply continuity planning, and negotiation leverage. The report provides the analytical context required to interpret these concentration patterns without over-simplifying the underlying competitive differentiation.
Equally important is the need to align material selection with environmental and lifecycle performance expectations. Advanced composite ties increasingly incorporate post-consumer recycled plastics reinforced with glass fibers, supporting diversion of plastic waste from landfills while meeting or exceeding recognized strength and stiffness standards. Some products have achieved industry certification benchmarks and demonstrated extended service life in high-decay zones, contrasting sharply with the shorter replacement intervals associated with traditional timber. The report connects these performance and sustainability attributes to procurement economics, enabling asset managers to evaluate whether lifecycle cost reductions, regulatory compliance benefits, and circular-economy alignment justify specification changes within their specific operating environments.
The forecast window through 2032 offers additional strategic utility. By mapping anticipated revenue expansion alongside the underlying material, application, and regional adoption variables, the report helps leadership teams anticipate demand pressure points, capacity constraints, and specification migration timelines. This forward view supports capital planning, vendor onboarding schedules, and internal business case development for composite integration projects, ensuring that investment decisions are tied to defensible adoption trajectories rather than optimistic assumptions.
Conclusion: Turning Market Intelligence into Infrastructure Advantage
The Worldwide Composite Railroad Tie Market research report is designed for organizations that treat infrastructure material strategy as a long-duration competitive variable rather than a routine purchasing function. By combining macro market sizing, material and application differentiation, competitive profiling, and recent partnership and trial developments into a single analytical framework, the publication equips executives to make procurement, investment, and specification decisions with greater confidence. The data trajectory, competitive dynamics, and policy-driven adoption signals discussed here represent only the entry layer of the full analysis. Organizations seeking to evaluate exact market size breakdowns, segment-level utilization models, supplier positioning matrices, and forecast-driven procurement scenarios will find the complete report essential to aligning their 2026 and beyond strategies with the realities of a rapidly evolving composite tie landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Composite Railroad Tie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com