

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low-Frequency Geophone Market Hits $152.45M in 2025, 7.0% CAGR to $244.81M by 2032

Navigating the Worldwide Low Frequency Geophone Market: Strategic Intelligence for 2026 Decision-Making
The global landscape for seismic instrumentation is entering a critical phase of recalibration. As energy transition projects, advanced geophysical research, and industrial safety monitoring converge, the demand for reliable low frequency geophones has moved from a niche technical requirement to a strategic infrastructure priority. For executives, procurement leaders, and technology strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
Our newly published Worldwide Low Frequency Geophone Market research study provides a comprehensive, data-backed roadmap through the 2026 to 2032 forecast period. Designed for executive briefing and operational planning, this report bridges historical performance with forward-looking intelligence, enabling organizations to anticipate demand shifts, evaluate vendor ecosystems, and align technology roadmaps with emerging geophysical applications.
Market Trajectory: From Historical Foundations to Forward Momentum
The worldwide low frequency geophone sector has demonstrated consistent expansion over the past half-decade, reflecting both mature industrial adoption and emerging use cases tied to environmental monitoring and deep-earth exploration. Historical revenue tracking from 2020 through the 2025 base year reveals a steady upward curve, culminating in a market valuation of approximately 152.45 million USD. This foundation has set the stage for a projected growth trajectory that extends well into the next decade, with the market anticipated to reach 244.81 million USD by 2032.
Underlying this expansion is a compound annual growth rate of 7.0 percent, a metric that signals more than incremental demand. It reflects structural shifts in how organizations approach subsurface imaging, seismic hazard assessment, and long-term infrastructure monitoring. The forecast window from 2026 onward captures the inflection point where traditional oil and gas workflows increasingly intersect with carbon storage verification, induced seismicity tracking, and remote-deployed sensing networks. Organizations that recognize this dual-engine growth pattern will be better positioned to hedge against cyclical commodity exposure while capturing value from sustained scientific and industrial procurement.
The historical data also underscores a market that has matured beyond early-adopter experimentation. Revenue patterns from 2020 to 2025 demonstrate how supply chains, manufacturing tolerances, and frequency-response engineering have stabilized around consistent performance benchmarks. This stabilization is critical for 2026 planners, as it reduces procurement uncertainty and allows for more precise forecasting of multi-year instrumentation programs.
Segmentation Architecture and Demand Vectors
Low frequency geophones are not a monolithic product category. Their performance specifications, deployment environments, and procurement cycles vary significantly across frequency bands, geographic markets, and application domains. Our research dissects these dimensions to reveal how demand is actually distributed across the industrial landscape, providing a practical lens for both suppliers and end-users.
The frequency spectrum segmentation highlights how different operational requirements drive distinct purchasing patterns. Instruments operating in the 1Hz to 2Hz range continue to anchor a substantial portion of market activity, reflecting their widespread utility in traditional seismic acquisition and structural analysis. The 2Hz to 4.5Hz band represents a complementary demand stream, often selected for applications requiring a balance between sensitivity and environmental robustness. Below 1Hz instruments, while occupying a smaller absolute share, are gaining strategic relevance in specialized scientific deployments, deep-earth imaging, and monitoring scenarios where extended low-frequency response is non-negotiable. Understanding how these bands interact with procurement cycles, lead times, and integration requirements is essential for organizations designing multi-sensor arrays or evaluating vendor capabilities.
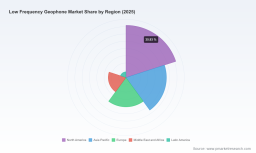
Geographic distribution further shapes market dynamics. Demand flows are influenced by regional exploration activity, research funding patterns, and industrial infrastructure development. North American markets continue to exhibit strong procurement volumes, supported by established energy sector workflows and advanced geophysical research institutions. The Asia Pacific region demonstrates substantial and growing activity, driven by expanding mineral exploration programs, engineering monitoring initiatives, and domestic manufacturing capacity. European markets maintain a steady demand profile aligned with scientific research, environmental regulation compliance, and precision instrumentation standards. Meanwhile, the Middle East and Africa, as well as Latin America, reflect more targeted but strategically important demand pockets tied to resource exploration and regional seismic monitoring networks. The interplay between these regional flows creates a complex procurement environment where supply chain flexibility, localization strategies, and certification alignment increasingly determine competitive advantage.
Application-driven demand further diversifies the market landscape. Oil and gas exploration remains a foundational demand pillar, but its influence is being reshaped by evolving reservoir characterization techniques and the integration of low-frequency sensors into broader acquisition systems. Earthquake and seismology research continues to drive steady procurement, particularly as institutional funding supports long-term monitoring networks and hazard assessment programs. Structural health monitoring represents a growing industrial application, where low frequency sensing is increasingly embedded into infrastructure safety protocols and predictive maintenance frameworks. Mining and mineral exploration adds another layer of demand, with operators leveraging improved low-frequency response to enhance subsurface resolution in complex geological settings. Each application vector carries distinct performance expectations, volume profiles, and replacement cycles, making application-level intelligence a critical input for both product strategy and sales planning.
Competitive Landscape and Strategic Positioning
The worldwide low frequency geophone market is characterized by a mix of established instrument manufacturers, specialized sensor providers, and regional equipment suppliers. Market concentration data indicates that the top three players collectively account for approximately 48.5 percent of revenue, while the top five firms extend their share to roughly 62.3 percent. This concentration pattern suggests a market where incumbency, technical certification, and integration capability matter significantly, but where mid-tier and regional players retain meaningful opportunities through customization, cost structure, and application-specific support.
Several companies define the current competitive architecture. Geospace Technologies Corporation, headquartered in Houston, Texas, maintains a prominent position through its portfolio of low-frequency seismometers and related sensors, including the GS-ONE LF, GS-1, and HS-1 models. Its product lineup is engineered for seismic exploration, structural analysis, geologic hazard assessment, and carbon storage monitoring, reflecting the broadening application base that defines the modern market. Sercel, based in Carquefou, France, brings a strong heritage in very low-frequency and long-period signal capture, with offerings such as the L-4 and L-22 seismometers and the SG-5 high-sensitivity sensor. Its emphasis on scientific studies, geophysical research, and oil and gas exploration underscores the crossover between academic-grade precision and industrial deployment.
In China, Seis Tech supplies very low frequency geophones, including 1Hz vertical and horizontal models, alongside high-sensitivity and triaxial variants. Its coverage spans petroleum and gas, mining, engineering, and passive seismic or earthquake monitoring, illustrating how regional manufacturers are expanding into both traditional and emerging application domains. Zhaofeng Sensor Equipment Co Ltd, also known as ZFGEO and based in Baoding City, manufactures and customizes high and low frequency geophone sensors, including 2Hz and 3Hz models, for oil and gas, mineral, and geotechnical exploration, with products tested across more than 65 countries. This international validation footprint is a meaningful differentiator in markets where field reliability and cross-border deployment experience influence procurement decisions.
Additional players contribute to a diverse supply ecosystem. Cable and Supplies, Inc., operating in the USA, provides low frequency geophones such as the 1Hz PS-1 seismometer and the 2Hz PS-2/260 and PS-2B models, alongside 2.5Hz and 2.7Hz velocity sensors. INOVA Geophysical focuses on precision seismic sensors, including the SN5A-5 high-sensitivity geophone designed for nodal and cable systems. Kinemetrics, Inc. supplies seismic sensors for monitoring and exploration applications, while Nanometrics, based in Canada, delivers high-precision geophones and seismometers for research and industrial low frequency use. Geometrics, also USA-based, offers seismographs with low frequency options extending down to 0.6Hz or DC, integrated with geophone systems for exploration workflows. PASI SRL, in Italy, manufactures geophones across various frequencies, including low frequency models such as 2Hz units for geophysical surveys.
Recent strategic movements highlight how competition is evolving beyond product catalogs. In July 2024, Geospace Technologies launched the GS-LF-X low-frequency geophone model targeting both marine seismic and onshore exploration applications, signaling a deliberate push into broader deployment environments. In April 2024, Geometrics announced a strategic partnership with Sensor Networks to integrate rugged, remote-deployed low-frequency geophones into distributed sensing arrays. This type of collaboration reflects a market trend where sensor performance is increasingly evaluated as part of a larger system architecture, rather than as a standalone component.
Industry Dynamics: Materials, Compliance, and Macro-Driven Demand
The operational reality of low frequency geophone manufacturing and deployment is shaped by a set of technical, regulatory, and macroeconomic forces that directly affect sourcing, qualification, and long-term reliability. At the component level, these instruments depend heavily on precision electromagnetic coils, magnets, and springs. Manufacturing processes must maintain frequency tolerance under tilt and temperature variations, which places a premium on material selection, assembly control, and quality assurance. For procurement teams, this means that supplier capability is not simply a matter of unit cost; it is tied to engineering rigor, tolerance consistency, and the ability to reproduce performance across production runs.
Worldwide Low Frequency Geophone Market
Worldwide Hydrophone Market
Regulatory and standards compliance further frames the competitive environment. Major suppliers maintain certifications such as ISO 9001:2015 for quality management, ISO 14001:2015 for environmental management, and ISO 45001:2018 for occupational health and safety. These certifications are more than administrative markers. They signal operational discipline, reduce qualification risk for large-scale procurement programs, and often serve as prerequisites for partnerships with government-funded research initiatives or regulated industrial projects. In markets where contract awards depend on documented process control and supply chain transparency, compliance readiness can be a decisive factor.
Macro trends are also reshaping demand fundamentals. The push toward carbon storage monitoring, induced seismicity tracking for CCS projects, and deep seismic exploration requiring extended low-frequency response is expanding the addressable use case pool beyond traditional exploration workflows. Low frequency geophones in the 1Hz to 5Hz range are increasingly viewed as enabling instruments for verification, monitoring, and risk management in projects where subsurface behavior must be observed over long time horizons. This shift has practical implications for product planning, service contracts, and deployment models, as end-users seek sensors that can support continuous or semi-continuous monitoring rather than one-time acquisition campaigns.
Strategic Value for 2026 Decision-Making
The 2026 decision environment demands more than high-level market awareness. Leaders need actionable intelligence that connects market size and growth rates to procurement timing, vendor evaluation, application planning, and risk management. This research study is structured to support that need by translating macro trends into operational context.
For technology and procurement leaders, the report provides a structured view of how frequency bands, application requirements, and regional demand patterns intersect. This helps organizations avoid over-indexing on a single segment or misreading the balance between exploration-driven and monitoring-driven procurement. For product and business development teams, the competitive landscape analysis offers a baseline for positioning, differentiation, and partnership strategy, especially as system-level integration and remote deployment become more prominent evaluation criteria. For executive planning, the forecast trajectory and concentration data provide a reality check on market maturity, competitive intensity, and the realistic scope for share capture in a market where incumbency and certification matter.
Equally important, the study frames the market in terms of transition risk and opportunity. Organizations that rely on low frequency geophones for conventional exploration must account for the growing relevance of environmental monitoring, carbon storage verification, and induced seismicity tracking. Suppliers and integrators that recognize this expansion can align product roadmaps, service offerings, and deployment models with the next wave of demand. Buyers who understand these dynamics can structure multi-year procurement with greater confidence, balancing cost efficiency against performance requirements and future-proofing their sensor networks.
What the Full Report Delivers
This introduction is designed to demonstrate the depth and applicability of the study while preserving the detailed segmentation, company-level benchmarking, and forecast breakdowns for the full report. The complete Worldwide Low Frequency Geophone Market research delivers a fully integrated view of the market across historical performance, segmentation splits, competitive profiles, and forward forecasts. It includes:
- A comprehensive revenue trajectory spanning the 2020 to 2025 historical period and the 2026 to 2032 forecast window, expressed in USD million, with a 7.0 percent CAGR framework that clarifies the pace and shape of market expansion.
- Detailed segmentation analysis across region, type, and application, enabling readers to understand how demand is distributed and where strategic focus may yield the strongest returns.
- In-depth company profiles for leading manufacturers and sensor providers, including headquarters location, product capabilities, and application coverage, along with recent developments that illustrate how the competitive field is evolving.
- Contextual analysis of industry dynamics, including component-level manufacturing considerations, compliance and certification patterns, and macro-driven demand shifts tied to carbon storage monitoring, induced seismicity tracking, and deep seismic exploration.
- Practical guidance for interpreting market concentration, evaluating supplier qualification criteria, and aligning procurement or product strategy with the shifting mix of exploration, research, monitoring, and industrial applications.
The full report is intended to serve as a working intelligence asset rather than a static overview. It is built to support scenario planning, vendor assessment, market entry evaluation, and strategic forecasting in a sector where technical performance, regulatory readiness, and application expansion are increasingly intertwined.
Conclusion
The worldwide low frequency geophone market is moving through a period of structural expansion, application diversification, and system-level integration. Historical growth has established a solid revenue base, while the forecast period points to continued momentum shaped by both traditional exploration needs and emerging monitoring responsibilities. For organizations operating in 2026, the strategic question is no longer whether this market matters, but how to interpret its segmentation, competitive concentration, and demand drivers with enough precision to act confidently.
This research study provides that interpretive framework. It connects market size, growth trajectory, segmentation logic, and competitive activity into a coherent decision-support structure, while leaving the granular breakdowns and detailed benchmarking for the complete report. For executives and analysts who need a reliable foundation for 2026 planning, the full study offers the depth required to move from market awareness to informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Low Frequency Geophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com