

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Hypersomnia Drug Market Hits $5.0B in 2025, Forecasted to Reach $10.06B by 2032 at 10.5% CAGR

Strategic Imperatives in the Worldwide Hypersomnia Drug Market: A 2026 Decision-Maker's Guide
The landscape of central nervous system therapeutics is undergoing a profound transformation, driven by heightened clinical recognition of hypersomnia disorders and a shifting competitive environment. As we navigate the forecast period from 2026 through 2032, the Worldwide Hypersomnia Drug Market represents a critical frontier for pharmaceutical strategy, investment capital, and healthcare access initiatives. Our latest comprehensive market research serves as an essential compass for executives aiming to navigate the complexities of this high-growth therapeutic area.
This article outlines the strategic context surrounding the hypersomnia market, synthesizing macroeconomic trajectories, competitive maneuvers, and regulatory dynamics. It is designed to demonstrate the depth of intelligence available in our full study, providing decision-makers with the context needed to appreciate the value of detailed segmentation and forward-looking analysis.
Worldwide Sedative-Hypnotic Drug Market
Macroeconomic Trajectory and Growth Catalysts
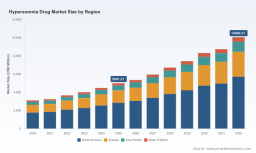
The hypersomnia drug market has demonstrated robust resilience and expansion over the historical period from 2020 to 2025. Analysis of revenue data reveals a consistent upward trend, with total market revenues climbing from approximately 3.1 billion USD in 2020 to over 5 billion USD in 2025. This historical performance underscores the increasing prevalence of diagnosed conditions such as narcolepsy and idiopathic hypersomnia, coupled with improved treatment adherence and diagnostic capabilities.
Looking ahead, the forecast period from 2026 to 2032 projects continued momentum. The market is expected to accelerate toward the 10 billion USD threshold by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 10.5 percent. Such a trajectory indicates more than mere population growth; it reflects a dynamic ecosystem where innovation in drug delivery, new chemical entities, and expanding indications are converging to broaden the total addressable market. However, realizing the full potential of this forecast requires nuanced understanding of regional variances, drug class utilization, and the impact of generic competition, all of which are detailed in our full report.
Thematic Forces Reshaping Market Dynamics
Several structural forces are redefining the competitive playbook for hypersomnia therapeutics. Understanding these dynamics is vital for strategic positioning in 2026 and beyond.
Worldwide Hypersomnia Drug Market
- Regulatory Complexity and Access Constraints : The classification of key oxybate therapies, such as sodium oxybate, under Schedule III controlled substances necessitates rigorous risk evaluation and mitigation strategies. The REMS program imposes specific distribution and handling requirements that influence prescribing patterns, reimbursement negotiations, and patient access logistics. Strategic planners must account for how these regulatory frameworks impact market penetration rates and commercial infrastructure requirements.
- Sodium Content and Formulation Innovation : A significant differentiator in the oxybate class is sodium content. Formulations with reduced sodium profiles offer distinct clinical advantages for patients with comorbidities related to cardiovascular health or dietary restrictions. The availability of mixed oxybate salts with significantly lower sodium content compared to traditional sodium oxybate has expanded the treatment landscape. This innovation not only addresses specific patient needs but also influences formulary positioning and prescriber preference, particularly where long-term safety profiles are scrutinized.
- Generic and Authorized Generic Entry : The erosion of exclusivity barriers for certain oxybate products has introduced pricing pressure and alternative access pathways. The emergence of authorized generics and ANDA-approved sodium oxybate oral solutions provides payers and healthcare systems with more affordable options for narcolepsy and related hypersomnia symptoms. This shift alters the competitive intensity within the branded segment and necessitates robust lifetime value modeling for innovators, while simultaneously creating opportunities for generic manufacturers to capture volume.
- Pipeline Diversification and Mechanism of Action : Beyond oxybates and traditional stimulants, the pipeline is rich with novel mechanisms. Histamine-3 receptor antagonists and orexin receptor agonists represent transformative approaches to wake promotion. The development of oral selective orexin 2 receptor agonists, in particular, marks a potential paradigm shift, offering non-scheduled alternatives with differentiated efficacy profiles. These candidates are advancing through clinical stages and attracting significant corporate interest, signaling a broadening of the therapeutic arsenal.
Competitive Landscape: Incumbents and Challengers
The competitive architecture of the hypersomnia market is characterized by a concentration of key players holding significant market share, alongside a wave of agile entrants and pipeline developers seeking to disrupt established norms. Our analysis identifies a core group of companies that are driving value creation and reshaping therapeutic standards.
Jazz Pharmaceuticals remains a dominant force, anchored by its portfolio of oxybate-based therapies. Its leadership is reinforced by the possession of FDA-approved treatments specifically indicated for idiopathic hypersomnia in adults, alongside therapies for narcolepsy. This dual-indication capability positions the company at the intersection of the two largest symptom clusters within the hypersomnia spectrum. The strategic focus on differentiated formulations and patient support programs continues to drive brand loyalty and market share retention.
Avadel Pharmaceuticals is executing a pivotal strategy centered on extended-release oxybate technology. With the completion of patient enrollment in a Phase 3 trial evaluating its extended-release sodium oxybate for idiopathic hypersomnia, the company is poised to potentially expand its label and capture additional patient populations. The anticipated data readout in the near term represents a binary event that could significantly alter the company's valuation and market positioning. Meanwhile, its commercialized product for narcolepsy provides a revenue base and operational foothold in the CNS space.
Harmony Biosciences and Bioprojet Pharma are leveraging the histamine-3 receptor antagonist mechanism. Pitolisant, as a non-stimulant wake-promoting agent, offers a distinct safety and tolerability profile compared to traditional stimulants. Its utility in managing excessive daytime sleepiness associated with narcolepsy and its potential application in broader hypersomnia symptom management make it a versatile asset in the treatment algorithm. As awareness of non-stimulant options grows, these companies are well-positioned to capture share among patients and providers seeking alternatives to controlled substances.
Teva and Amneal are central to the generic and volume-driven segment. Teva's supply of generic wake-promoting agents, including modafinil and armodafinil, ensures broad accessibility for off-label and approved uses related to excessive daytime sleepiness. Amneal's recent regulatory milestones, including approval for sodium oxybate oral solution referencing a branded product, highlight the intensifying competition in the oxybate space. These entries expand the availability of lower-cost alternatives, influencing pricing dynamics and access strategies across the market.
Alkermes, Inc. is pursuing a high-risk, high-reward strategy with its oral selective orexin 2 receptor agonist. The receipt of FDA Breakthrough Therapy Designation for narcolepsy type 1 underscores the clinical promise of this mechanism. With development activities extending to idiopathic hypersomnia, Alkermes is targeting a potential best-in-class profile that could redefine treatment standards if clinical and regulatory milestones are met successfully.
Takeda Pharmaceutical continues to advance its orexin receptor agonist pipeline, including multiple candidates in clinical development. As a global pharmaceutical giant, Takeda's involvement signals the strategic importance of the orexin pathway and brings substantial resources to the race for novel mechanisms. The progress of these candidates contributes to the overall optimism surrounding the future of hypersomnia treatment.
Tris Pharma has achieved regulatory traction with the FDA acceptance of its NDA for a once-nightly low-sodium oxybate formulation. This filing covers both narcolepsy and idiopathic hypersomnia indications, positioning the product to address a broad patient base with a convenient dosing regimen. The upcoming regulatory decision window represents a key catalyst for the company and a potential new entry point for competitive pressure in the oxybate category.
Zevra Therapeutics and other CNS-focused entities are also active participants, contributing to the diversity of approaches and the overall vibrancy of the innovation ecosystem. Their presence underscores the interest in idiopathic hypersomnia as a distinct therapeutic area with unmet needs that warrant dedicated development efforts.
Recent Corporate Activity and Market Signals
Recent M&A and clinical developments provide real-time indicators of market confidence and strategic priorities. The pharmaceutical industry's willingness to deploy significant capital in this space is evident. For instance, a major acquisition agreement involving a large-cap pharmaceutical company and a biotech firm with an orexin receptor 2 agonist pipeline highlights the premium placed on novel mechanisms targeting narcolepsy and idiopathic hypersomnia. Such transactions signal to the market that orexin-based therapies are viewed as high-value assets capable of commanding substantial returns, thereby encouraging further investment in related R&D programs.
Additionally, the completion of patient enrollment in pivotal trials, such as the Phase 3 study for extended-release sodium oxybate in idiopathic hypersomnia, removes a key execution risk for developers. The proximity of data readouts creates anticipation and potential volatility, requiring stakeholders to monitor these events closely as they may trigger shifts in market share expectations and competitive responses.
Regulatory filings and approvals continue to reshape the supply side. The acceptance of NDAs for once-nightly formulations and the approval of generic oxybate products reflect an environment of both innovation and commoditization occurring simultaneously. Companies must balance the opportunities presented by new indications and formulations against the realities of increasing competition and access pressures from lower-cost alternatives.
Strategic Questions for 2026 Decision-Makers
As organizations formulate their strategies for the current fiscal year and the ensuing forecast horizon, several critical questions demand answers that go beyond surface-level metrics:
- How will the interplay between branded differentiation and generic pressure evolve across different drug classes, and what pricing and contracting strategies are required to protect value?
- Which clinical and regulatory milestones in the orexin and histamine pathways will serve as inflection points for treatment algorithms, and how should commercial teams prepare for rapid adoption scenarios?
- How do regional reimbursement landscapes and access restrictions influence the relative attractiveness of specific indications and formulations, and where are the hidden pockets of growth?
- What is the realistic impact of sodium-reduction trends and once-nightly dosing convenience on patient adherence and market penetration, and how should this inform product development and marketing messaging?
- How should companies benchmark their positioning against the high concentration of market share held by leading incumbents, and what partnership or acquisition opportunities exist to accelerate pipeline progress?
Conclusion: The Value of Granular Intelligence
The Worldwide Hypersomnia Drug Market stands at a juncture of significant opportunity, driven by robust growth projections, a deepening therapeutic arsenal, and dynamic competitive interactions. A CAGR of 10.5 percent and a projected expansion toward the 10 billion USD mark by 2032 confirm the sector's status as a priority area for strategic investment. However, navigating this market successfully requires more than aggregate data. It demands a granular understanding of segmentation nuances, competitive positioning, regulatory tailwinds and headwinds, and the specific value drivers that differentiate one therapy from another.
Our comprehensive market research report delivers the precision intelligence required to act on these insights. From detailed segmentation analysis across regions, drug classes, and indications to deep-dive company profiles and scenario-based forecasting, the study equips stakeholders with the tools to make informed, confident decisions. To access the full spectrum of data, including precise market sizing for each segment, competitive share breakdowns, and actionable strategic recommendations, we invite you to explore the complete report.
Unlock the full intelligence behind the hypersomnia market's trajectory and secure your strategic advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Hypersomnia Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com