

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aluminum Exhibits Market Hits $4,210M in 2025, Projected to Reach $7,088.63M by 2032 at 7.73% CAGR

Strategic Intelligence for the Aluminum Exhibits Market: Navigating Growth and Complexity in 2026
The global aluminum exhibits market stands at a pivotal inflection point. As organizations across trade shows, events, and retail environments demand more modular, sustainable, and technologically integrated display solutions, the strategic importance of precise market intelligence has never been higher. This article serves as a preview of our latest comprehensive market research report, designed to equip executives, investors, and supply chain leaders with the contextual depth needed to make informed decisions throughout 2026 and beyond.
The underlying market dynamics reflect both robust expansion and intensifying structural complexity. Historical performance from 2020 to 2025 demonstrates a trajectory shaped by post-pandemic event recovery, accelerated adoption of lightweight aluminum frameworks, and the rapid digitalization of physical exhibition spaces. Looking forward, our forecast period spanning 2026 through 2032 maps a continued growth pathway underpinned by predictable demand drivers, though one that is simultaneously tested by raw material volatility, shifting trade regulations, and evolving competitive positioning. Understanding where the market is headed, and why, requires moving beyond headline numbers into the operational and strategic layers that actually drive commercial outcomes.
Macro Trajectory and the 2026 Decision Window
The market has expanded materially over the past half-decade, scaling from approximately 1,650 million USD in 2020 to an estimated 4,210 million USD by 2025. That progression reflects more than a simple rebound; it signals a structural recalibration in how exhibitors, event producers, and brand managers approach physical environments. Aluminum's inherent advantages, recyclability, modularity, strength-to-weight ratio, and compatibility with integrated lighting and digital media, have cemented its role as a foundational material in modern exhibit design.
Our forecast model projects the market to reach 4,426.72 million USD in 2026, with growth compounding at a 7.73 percent CAGR through the end of the forecast window. By 2032, the market is positioned to approach the 7,088.63 million USD threshold. These are not abstract projections. They represent a demand environment in which procurement teams must plan for capacity, pricing, and supply continuity; in which manufacturers must decide where to allocate R&D and production resources; and in which investors must distinguish between cyclical noise and durable secular growth.
The 2026 decision window is particularly consequential because multiple forces are converging simultaneously. Demand for reconfigurable and reusable exhibit packages continues to rise as organizations seek to reduce waste, lower total cost of ownership, and maintain brand consistency across multiple event locations. At the same time, the cost and availability of aluminum as a primary input have become critical variables in margin management and pricing strategy. Leaders who treat 2026 as a planning anchor rather than a reactive operating year will be better positioned to capture share while managing downside risk.
Structural Shifts Across Product Types and Applications
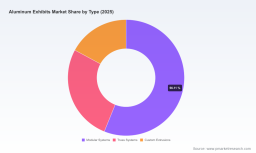
The market's growth is not uniform across all product types or end-use applications. Instead, it is being reshaped by clear preference patterns that favor flexibility, speed of deployment, and design precision. Modular systems, which enable rapid assembly, reconfiguration, and reuse across different event footprints, have captured a substantial share of commercial activity. Their appeal lies in their ability to reduce labor costs, shorten setup timelines, and support sustainability objectives by extending the usable life of exhibit assets.
Truss systems continue to serve a distinct but meaningful role, particularly where structural spans, overhead installations, and architectural visibility are priorities. Custom extrusions, meanwhile, cater to organizations that require highly tailored geometries, integrated functional elements, or specialized finishes that standard configurations cannot deliver. Together, these categories illustrate a market that is simultaneously standardizing at the modular level while still rewarding engineering-driven customization where brand differentiation or functional requirements demand it.
Application-side dynamics reinforce this divergence. Trade shows and exhibitions remain the dominant commercial engine, reflecting the ongoing centrality of in-person industry gatherings, product launches, and brand immersion experiences. Events and concerts contribute a notable secondary demand stream, particularly where temporary stage architectures, scenic structures, and branded environments rely on aluminum's portability and load-bearing capabilities. Retail and interior displays represent a growing adjacency, as brands extend exhibit-grade modular logic into permanent or semi-permanent storefront environments, pop-up retail, and experiential showrooms.
What matters for strategic planning is not simply which category is largest, but how these segments interact. Modular platforms increasingly serve as the backbone for multi-application deployments. A single engineered frame may support a trade show booth in one quarter, a concert staging element in another, and a retail display installation thereafter. This cross-application flexibility changes the economics of product development and procurement, placing a premium on systems that can adapt without sacrificing structural integrity or aesthetic consistency.
Aluminum Exhibits Market
Competitive Landscape and the Battle for Differentiation
The competitive environment reflects a blend of established manufacturers, specialized engineering firms, and extrusion specialists, many of which are pursuing differentiation through design capability, material innovation, and technology integration. Several companies have defined themselves through a clear strategic identity rather than competing solely on price.
Aluvision has positioned itself at the intersection of modular aluminum framing and immersive brand environments, with an emphasis on sustainable design and LED-integrated solutions. Its trajectory illustrates how exhibit manufacturers are increasingly expected to deliver more than structural components; they are being asked to support lighting, media integration, and environmentally responsible production practices within a single system.
Agam brings more than four decades of experience in engineered modular aluminum structures and extrusions, serving exhibit companies and agencies that require reliability, repeatability, and technical depth. Its recent industry analysis emphasizes a market-wide shift toward smarter and more efficient modular builds, signaling that performance optimization and material efficiency are becoming core purchasing criteria rather than secondary considerations.
Skyline Exhibits continues to operate across the full spectrum of custom modular trade show exhibits and displays, combining design, manufacturing, and management services with fast-ship kits and full-service deployment options. Its recognition in the 2026 MUSE Creative Awards underscores how creative execution and engineering discipline are increasingly evaluated together by buyers who view exhibits as both functional infrastructure and brand communication tools.
The broader supplier ecosystem includes organizations such as Exhibit and Display Truss, Abex, Extrude-A-Trim, 80/20 Inc., and Nova Display, each contributing distinct capabilities ranging from aluminum truss structures and lightweight reconfigurable booths to T-slot extrusion systems and modular floor stands or showcases. The presence of multiple specialized players indicates a market that rewards technical versatility and responsive service, especially for customers managing tight event schedules or complex installation constraints.
From a concentration standpoint, the market remains moderately fragmented, with the top three players accounting for roughly 32.4 percent of revenue and the top five approaching 45.6 percent. This structure suggests that while scale players hold meaningful influence, there is still substantial room for mid-sized and specialized firms to compete on engineering quality, regional responsiveness, customization depth, and integration capabilities. For procurement leaders, this fragmentation is strategically useful: it supports negotiation leverage, encourages supplier diversification, and allows organizations to match specific vendors to specific project requirements rather than relying on a single universal source.
External Pressures: Materials, Trade Policy, and Supply Dynamics
No strategic assessment of the aluminum exhibits market in 2026 would be complete without confronting the external forces that directly shape cost structures and supply availability. Raw material prices have become a central boardroom topic, and aluminum is no exception. Recent market conditions show aluminum prices moving higher through early 2026, with cash prices climbing above the 3,000 USD per tonne level and extending further as supply concerns and trade policy effects interacted with demand. By mid-May 2026, LME aluminum cash pricing reached approximately 3,564 USD per tonne, a notable year-over-year increase that underscores the importance of monitoring input costs at a granular level.
This pricing environment has direct implications for manufacturers, fabricators, and exhibit buyers. For producers, it reinforces the need for forward sourcing strategies, hedged procurement where appropriate, and design choices that optimize material yield. For exhibit purchasers, it highlights the value of reusable and modular systems that reduce repeated material exposure across multiple events. In practical terms, the organizations that succeed in this environment are those that treat aluminum cost not as a static line item, but as a variable to be managed through product architecture, inventory planning, and supplier relationships.
Trade policy adds another layer of complexity. In April 2026, U.S. Section 232 tariffs on aluminum and derivatives were revised, with rates in the range of 25 to 50 percent on full customs value for many imported aluminum articles, including extrusions that are directly relevant to exhibit manufacturing. Alongside this, an ongoing U.S. antidumping duty administrative review covering aluminum extrusions from China is examining the May 2024 through April 2025 period, with preliminary determinations addressing China-wide entity rates. These developments matter because they affect landed cost, sourcing strategy, and the relative attractiveness of domestic versus imported supply.
The strategic takeaway is not that trade risks are uniformly prohibitive, but that they require deliberate mapping. Companies with exposure to imported extrusions must evaluate tariff impact on product costing, assess alternative sourcing pathways, and consider whether near-term inventory or contract structures can buffer volatility. Companies with domestic production or flexible supply chains may find themselves better positioned to serve customers who prioritize reliability and regulatory predictability. In either case, the firms that incorporate trade dynamics into their planning early will have more options than those that discover exposure only after pricing or availability shifts.
What the Research Report Delivers for Decision-Makers
Our full market research report translates this landscape into an actionable decision framework. It is designed not as a static data reference, but as an operating companion for teams responsible for product strategy, procurement, sales planning, capital allocation, and competitive positioning. The report integrates historical analysis, forward-looking forecasts, segmentation logic, and competitive intelligence into a cohesive narrative that helps leaders answer practical questions about where demand is strengthening, where margins are under pressure, and how to align organizational priorities with market realities.
Worldwide Exhibition Stand Market
Readers can expect a detailed examination of market sizing and growth pathways across the forecast horizon, with explicit attention to the drivers behind the projected expansion and the variables that could accelerate or moderate it. The report addresses the structural role of modular systems, truss systems, and custom extrusions, and it maps how these product categories function across trade shows, events, concerts, retail displays, and related environments. Rather than presenting segmentation as an abstract breakdown, it frames each slice of the market in operational terms: what it demands from suppliers, what buying criteria dominate, and where the most meaningful value creation opportunities lie.
The competitive analysis goes beyond company descriptions to explore strategic positioning, capability differentiation, and the practical implications of recent industry moves. It contextualizes developments such as creative award recognition, the issuance of exhibit trend analyses emphasizing smarter modular builds, and exclusive distribution partnerships for LED-integrated aluminum systems. These events are not treated as isolated news items; they are interpreted as signals of how manufacturers are competing for attention, contracts, and channel advantage in a market where technology integration and design credibility increasingly influence purchasing decisions.
Material and regulatory context is woven throughout, ensuring that strategic recommendations are grounded in the real conditions shaping aluminum availability and cost. The report examines how raw material price movements affect production economics, how revised tariff frameworks alter sourcing trade-offs, and how ongoing trade reviews influence supply-chain confidence. This integrated approach allows decision-makers to connect market growth potential with the practical constraints that determine whether that potential can be captured profitably.
For executives and analysts, the report offers a structured basis for scenario planning. It supports questions such as how to prioritize regional supply flexibility, how to evaluate whether modular reuse programs can offset input cost volatility, how to position product portfolios in a market that rewards both standardization and customization, and how to interpret competitive moves as indicators of where the next wave of differentiation will emerge. In that sense, the research is meant to reduce uncertainty where it matters most: in the choices that shape capacity planning, vendor selection, pricing strategy, and long-term portfolio direction.
Strategic Takeaways for 2026 and Beyond
The aluminum exhibits market is expanding within a landscape that rewards clarity of strategy. Growth is real and measurable, but it is unfolding alongside material cost volatility, trade-policy evolution, and intensifying competition for design-led, technology-enabled exhibit solutions. Organizations that treat these forces as isolated externalities risk underestimating their impact on margins, timelines, and supplier reliability. Those that integrate them into planning will be better equipped to allocate resources, negotiate from a position of insight, and build exhibit systems that remain efficient across multiple deployments.
Several priorities stand out. First, modular and reconfigurable design is no longer a convenience feature; it is increasingly a core economic and sustainability requirement. Second, aluminum pricing and trade regulation should be incorporated into procurement and product strategy early, with explicit attention to sourcing options and landed-cost modeling. Third, competitive differentiation is shifting toward integrated capabilities, including lighting, media compatibility, rapid deployment, and engineering reliability, which means manufacturers and buyers alike must evaluate vendors on total system value rather than component price alone.
Our full report provides the deeper quantitative and qualitative intelligence needed to operationalize these priorities. It delivers the market sizing, growth trajectory, segmentation logic, competitive context, and external risk mapping required to support confident decision-making throughout 2026 and the wider forecast period. For teams seeking a clearer line of sight between market opportunity and execution strategy, the complete analysis offers the level of detail and structural insight that high-stakes planning demands.
For detailed analysis of this topic, please visit the official page: Aluminum Exhibits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com