

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Metal Cutting Gas Market to Hit $7B by 2032, Growing at 5.4% CAGR

Strategic Intelligence for the Decade Ahead: Inside the Worldwide Metal Cutting Gas Market 2026–2032
The global industrial landscape is undergoing a structural recalibration. From supply chain realignment to decarbonization mandates, manufacturing enterprises face a complex web of forces that directly influence production economics. Within this environment, the metal cutting gas market occupies a critical yet often underestimated position. As a foundational input for fabrication, maintenance, and assembly operations, the supply, pricing, and technological evolution of cutting gases increasingly determine operational resilience and cost efficiency across heavy industry. PW Consulting’s newly released Worldwide Metal Cutting Gas Market research provides a comprehensive strategic roadmap for executives navigating this competitive terrain through 2032. This analysis distills the report’s most consequential insights, emphasizing actionable intelligence for 2026 decision-making while preserving the granular data architecture that detailed procurement and investment planning require.
Market Trajectory and Macroeconomic Foundations
Historical performance and forward-looking projections establish a clear narrative of sustained growth tempered by cyclical volatility. Between 2020 and 2025, the worldwide market expanded from approximately 3,750 million USD to 4,850 million USD, reflecting robust industrial recovery, accelerated infrastructure deployment, and steady demand from fabrication-intensive sectors. The forecast window extending through 2032 indicates a compound annual growth rate of 5.4 percent, positioning the market to reach roughly 7,008 million USD by the terminal year. This trajectory signals more than incremental expansion; it reflects a structural shift in how metalworking enterprises source, optimize, and integrate cutting gases into broader operational workflows.
Historical Momentum and Forward Projections
The 2020–2025 period demonstrated remarkable resilience despite macroeconomic disruptions, logistics constraints, and fluctuating feedstock availability. Revenue progression consistently outpaced earlier baselines, underscoring the non-discretionary nature of metal cutting operations in automotive assembly, heavy equipment manufacturing, shipbuilding, and infrastructure development. Looking ahead, the forecast period anticipates acceleration driven by capacity expansions in emerging industrial corridors, modernization of legacy fabrication facilities, and increasing adoption of optimized gas blends that improve cutting efficiency while reducing consumable waste. Analysts tracking the sector note that procurement strategies are evolving from price-centric Purchasing models to integrated supply chain partnerships, where gas delivery reliability, safety compliance, and technical support carry equal weight alongside unit cost.
Structural Drivers Shaping Demand Economics
Several interlocking dynamics will define market behavior throughout the forecast window. First, the ongoing upgrading of metal fabrication capabilities in Asia Pacific and select European corridors continues to elevate baseline consumption. Second, the modernization of legacy cutting equipment toward higher-efficiency oxy-fuel and hybrid plasma configurations creates demand for specialized gas formulations that maximize flame temperature, reduce oxygen consumption, and minimize slag formation. Third, regulatory environments are tightening around hazardous air pollutants, transportation safety for compressed gases, and emissions standards in integrated steel and metal processing facilities. These regulations do not merely constrain operations; they reshape procurement specifications, incentivize cleaner-burning fuel blends, and increase the strategic value of suppliers capable of delivering compliant, technically supported gas solutions.
Metal Cutting Tools Market
Feedstock pricing remains a persistent variable. Recent market observations indicate divergent regional pricing patterns for acetylene, with European benchmarks reflecting upward pressure linked to calcium carbide supply dynamics, while North American pricing has tracked alongside varied downstream fabrication demand. Such divergences reinforce the necessity of region-specific sourcing strategies rather than one-size-fits-all procurement frameworks. Enterprises that map feedstock exposure, logistics constraints, and regional regulatory timelines into their gas purchasing architecture will secure a measurable competitive advantage.
Segmentation Intelligence and Application Realities
Effective strategy requires precise segmentation mapping. The Worldwide Metal Cutting Gas Market research decomposes the ecosystem across three critical axes: geographic distribution, gas type classification, and end-use application segments. Each layer reveals distinct demand drivers, competitive intensity, and growth vectors that general market summaries frequently obscure.
Geographic Dynamics and Regional Demand Patterns
Regional analysis within the report illuminates where industrial activity concentrates, where infrastructure investment accelerates, and where procurement frameworks diverge. The data architecture identifies Asia Pacific as the largest revenue contributor, reflecting massive fabrication output, expanding shipbuilding and offshore repair capacity, and sustained automotive and transportation manufacturing. Europe maintains a substantial share supported by mature industrial ecosystems, stringent safety and emissions standards, and ongoing equipment modernization cycles. North America rounds out the top tier, driven by heavy machinery production, defense-related fabrication, and resilient construction and infrastructure spending. Middle East and Africa, alongside Latin America, represent specialized but strategically important corridors where localized supply networks, import dependencies, and project-based demand create distinct sourcing requirements.
Importantly, the report avoids superficial regional generalizations. Instead, it maps regional demand against local feedstock availability, regulatory calendars, logistics infrastructure, and the presence of key supplier operations. This approach enables executives to evaluate market entry opportunities, assess supply chain vulnerability, and calibrate inventory strategies according to regional risk profiles rather than global averages.
Gas Type Classification and Technical Differentiation
The gas type segmentation captures a market far more diverse than legacy acetylene-centric assumptions suggest. Acetylene remains a dominant share contributor, valued for its high flame temperature and versatility across traditional oxy-fuel cutting applications. Propane follows as a widely deployed alternative, offering cost advantages and safety profile benefits for specific fabrication workflows. Propylene occupies a strategic middle ground, particularly where operators seek enhanced cutting performance with reduced oxygen consumption. Methane and natural gas segments reflect ongoing integration of utility-scale gas infrastructure into industrial fabrication environments, while specialty fuel blends represent a growing niche for precision applications requiring customized combustion characteristics.
Worldwide Metal Cutting Gas Market
Each gas type carries distinct handling requirements, storage considerations, equipment compatibility constraints, and regulatory implications. The report details how these technical differentiators influence procurement decisions, vendor selection, and in-house operational training. Executives evaluating supplier portfolios will find direct relevance in the segmentation analysis, particularly when matching gas chemistry to cutting process specifications and compliance mandates.
Application Segments and End-Market Alignment
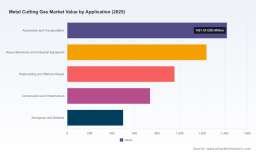
Understanding where cutting gases are consumed unlocks clearer forecasts of demand stability, cyclical exposure, and growth acceleration. Automotive and transportation applications represent a leading consumption segment, reflecting high-volume fabrication, body-in-white cutting, chassis component processing, and aftermarket maintenance operations. Heavy machinery and industrial equipment follow closely, encompassing earthmoving equipment, agricultural machinery, and specialized industrial component fabrication that demands robustness and consistent cut quality. Shipbuilding and offshore repair form a structurally significant segment, where project-based demand peaks align with vessel construction cycles, fleet maintenance schedules, and offshore platform rehabilitation programs.
Construction and infrastructure applications provide a steady baseline driven by structural steel processing, pipeline fabrication, and civil engineering projects. Aerospace and defense represent a technically demanding segment where precision, material compatibility, and stringent quality assurance protocols elevate the importance of gas consistency and supplier technical support. The report’s application segmentation enables stakeholders to map demand volatility, identify procurement cycles, and anticipate where equipment upgrades or process optimizations will trigger gas specification changes.
Competitive Architecture and Strategic Positioning
Market concentration data indicates that the three largest competitors collectively command approximately 38.4 percent of global revenue, while the top five firms extend their combined share to roughly 52.6 percent. This concentration profile suggests a market structure where global integrators hold substantial influence, yet meaningful regional and specialized players maintain viable competitive positions through localized distribution networks, application-specific expertise, and strong customer relationships. Understanding this architecture is essential for procurement leaders evaluating supplier diversification, for investors assessing market entry barriers, and for executives planning partnership or acquisition strategies.
Global Integrators and Their Operational Footprints
Linde plc stands as a major global supplier of industrial gases, including oxygen, acetylene, propane, and specialized mixtures tailored for oxy-fuel metal cutting, plasma cutting, and laser cutting applications across metal fabrication workflows. Its worldwide operational presence enables coordinated supply across multiple regions, while technical service capabilities support complex fabrication environments. Air Liquide S.A. operates as a leading producer and distributor of cutting gases such as oxygen, acetylene, and fuel gas blends, complemented by oxy-fuel cutting equipment and integrated solutions for worldwide metal fabrication and manufacturing. The company’s position reflects deep integration between gas supply, equipment provision, and application engineering.
Air Products and Chemicals, Inc. supplies oxy-fuel cutting gases, including propylene-based cutting solutions, alongside laser and plasma cutting gases and total solutions for metal cutting applications globally. Its portfolio emphasizes performance optimization and process integration. Messer SE & Co. KGaA operates as a specialized provider of industrial gases and solutions for metal industry applications, including cutting and welding gases for fabrication, with a strong presence across Europe, the Americas, and Asia. Its regional depth and technical specialization make it a significant competitor in markets where localized service and application knowledge drive purchasing decisions.
Regional Specialists and Fuel Gas Suppliers
Beyond the global integrators, a cohort of regional and fuel-focused suppliers shapes competitive dynamics through specialized product offerings and geographic proximity. TotalEnergies SE supplies fuel gases including propane and specialized cutting gas formulations for oxy-fuel metal cutting processes, leveraging broader energy sector infrastructure and fuel distribution capabilities. Indian Oil Corporation Ltd provides Indane NANOCUT and other LPG-based cutting gases optimized for high flame temperature and low oxygen consumption in metal cutting applications, addressing regional demand with formulations designed for operational efficiency. Bharat Petroleum Corporation Limited supplies industrial and cutting gases, including LPG variants for metal cutting and fabrication in Indian and export markets, supporting both domestic fabrication and cross-border supply requirements.
Brothers Gas operates as a regional supplier of industrial cutting gases and mixtures for oxy-fuel and other metal cutting processes across Middle East and international markets, filling a strategic role in regions where localized availability and rapid response logistics influence procurement decisions. NISSAN TANAKA CORPORATION functions as a manufacturer and supplier of gases and equipment focused on metal cutting and welding applications in Japan, combining gas supply with equipment integration for technically advanced fabrication environments. ESAB, part of the Colfax group, provides cutting gases alongside welding and cutting equipment and consumables for metal fabrication worldwide, positioning itself at the intersection of consumable supply and equipment solutions.
Competitive Differentiation and Procurement Implications
The competitive landscape rewards suppliers that deliver more than volume. Technical consultation, safety compliance support, delivery reliability, formulation customization, and equipment-gas compatibility expertise increasingly differentiate market participants. Procurement teams evaluating supplier partnerships should consider how each competitor’s operational footprint aligns with regional demand, how their product portfolio maps to cutting process requirements, and how their service infrastructure mitigates supply disruption risk. The report’s competitive analysis provides a structured framework for these evaluations, enabling data-driven supplier selection rather than relationship-led assumptions.
Operational, Regulatory, and Supply Chain Context
Market behavior does not occur in isolation. Regulatory frameworks, raw material dynamics, and transportation safety requirements continuously reshape operational parameters. Recent developments highlight the practical relevance of these forces. In the United States, the Environmental Protection Agency maintains national emission standards for hazardous air pollutants applicable to integrated iron and steel manufacturing facilities, covering sinter plants, blast furnaces, and basic oxygen process shops that influence related metal processing gas usage. These standards encourage fabricators and their gas suppliers to align specifications with emissions compliance, often favoring formulations and process configurations that reduce atmospheric impact.
Simultaneously, the U.S. Department of Transportation’s Pipeline and Hazardous Materials Safety Administration oversees hazardous materials transportation regulations for compressed gases including acetylene and oxygen used in metal cutting, with ongoing research into pipeline safety and leak detection standards. Transportation compliance affects delivery scheduling, packaging choices, storage design, and risk management protocols, making regulatory tracking an operational necessity rather than a peripheral concern.
On the trade policy front, Section 232 tariffs on steel and aluminum imports underwent restructuring in April 2026, shifting application to the full customs value of certain finished products containing metals. This adjustment can influence metal fabrication costs and, indirectly, gas demand by altering the cost structure of imported components and domestic substitution incentives. Enterprises with exposure to tariff-affected supply chains should reassess procurement sourcing, inventory positioning, and gas consumption forecasts as part of broader cost and supply chain planning.
Raw material pricing adds another layer of complexity. Acetylene pricing in Europe has reflected upward movement linked to calcium carbide feedstock costs, while North American acetylene pricing has tracked alongside downstream fabrication demand with periodic increases. These dynamics underscore the importance of feedstock monitoring, contract structuring, and alternative gas type evaluation when cost volatility emerges. Suppliers and buyers alike benefit from anticipating feedstock-driven pricing shifts rather than reacting after margins compress.
What the Report Delivers for 2026 Decision-Makers
PW Consulting’s Worldwide Metal Cutting Gas Market research translates macro trends, segmentation detail, competitive intelligence, and regulatory context into a decision-ready intelligence package. The report is designed for executives who require more than headline figures. It structures information to support strategic planning, procurement optimization, supplier evaluation, market entry assessment, and risk mitigation.
Scope, Methodology, and Analytical Depth
The analysis covers historical performance from 2020 through 2025 and projects market behavior across the 2026–2032 forecast window, all expressed in million USD with a clearly documented compound annual growth rate. This temporal span enables readers to understand how past disruptions, recovery patterns, and investment cycles inform future expectations. Methodological rigor ensures that projections are grounded in observable demand drivers, segmentation logic, and competitive behavior rather than generic extrapolation.
Actionable frameworks for procurement and strategy teams
Beyond forecasts, the report provides practical frameworks that procurement and strategy teams can apply immediately. These include segmentation mapping that clarifies where demand concentrates and how it evolves, competitive profiling that distinguishes global integrators from regional specialists and fuel-focused suppliers, and regulatory tracking that highlights compliance inflection points affecting gas selection, transportation, and storage. The research also incorporates application-level insights that help align gas specifications with cutting process requirements, equipment configurations, and quality assurance standards.
For executives evaluating capital allocation, the report supports scenario planning by outlining where growth is most probable, which segments face cyclical exposure, and how regulatory or feedstock shocks could alter cost structures. For supplier relationship managers, it provides a structured lens to assess vendor capability beyond price, focusing on reliability, technical support, compliance alignment, and regional coverage. For investors and market entrants, it delineates concentration dynamics, differentiation opportunities, and the practical barriers that shape competitive viability.
Connecting data to execution
A distinguishing feature of the research is its emphasis on execution relevance. Market size and growth rates matter, but their strategic value emerges when tied to actionable choices: which gas types align with specific cutting applications, which regions present the strongest demand trajectory relative to supply risk, which competitors offer complementary capabilities, and which regulatory timelines require proactive preparation. The report is organized to facilitate these connections, enabling readers to move from awareness to action without reconstructing the analytical logic themselves.
Conclusion: Making Informed Moves in a Shifting Market
The worldwide metal cutting gas market is not a static commodity environment. It is a technically nuanced, regionally diverse, and competitively layered ecosystem in which procurement decisions, supplier partnerships, regulatory preparedness, and feedstock awareness converge to shape operational performance. The 2026–2032 forecast window presents both opportunity and complexity. Growth is sustained, but its distribution across regions, gas types, and applications requires careful evaluation. Competition is concentrated at the top yet remains dynamic through regional specialists and fuel-focused suppliers. Regulatory and trade developments introduce variables that reward proactive planning.
PW Consulting’s comprehensive market research equips executives with the intelligence necessary to navigate this environment with confidence. By combining rigorous market sizing, detailed segmentation, competitive profiling, and operational context, the report delivers a strategic foundation for 2026 decision-making and beyond. To access the full dataset, regional breakdowns, application-level analysis, and complete competitive assessments, we invite stakeholders to visit the source page and obtain the complete Worldwide Metal Cutting Gas Market research. Detailed intelligence remains the most reliable basis for strategic action, and the complete report provides exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Cutting Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com