

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
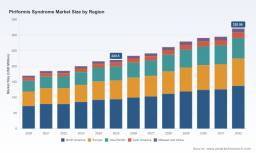
PW Consulting Forecasts Global Piriformis Syndrome Market to Reach $320.96M by 2032 at 5.51% CAGR

Navigating the Piriformis Syndrome Market: Strategic Imperatives for 2026 and Beyond
The piriformis syndrome market is entering a pivotal phase of maturation, shaped by advancing minimally invasive techniques, evolving reimbursement frameworks, and a growing emphasis on multimodal pain management. As healthcare systems worldwide continue to refine treatment pathways for this complex neuromuscular condition, stakeholders require granular, forward-looking intelligence to allocate capital, position product portfolios, and anticipate competitive shifts. This analysis introduces our latest Worldwide Piriformis Syndrome Market research, a comprehensive intelligence asset designed to equip executives, investors, and clinical strategists with the decision-grade insights needed to navigate the 2026 to 2032 horizon with confidence.
Market Trajectory and Strategic Context
Over the past half-decade, the global market for piriformis syndrome interventions has demonstrated steady, structurally supported expansion. Drawing on historical performance through the base year of 2025, our research traces a consistent upward trajectory that reflects both rising diagnostic awareness and the broader shift toward targeted, outcome-driven musculoskeletal care. Looking ahead, the market is projected to reach a substantial valuation by 2032, underpinned by a compound annual growth rate that signals durable, mid-single-digit expansion across the forecast window. This growth is not accidental; it is being engineered by converging clinical, regulatory, and technological forces that are reshaping how providers approach piriformis-related pain, nerve compression, and functional impairment.
For enterprise leaders, the strategic implications are clear. The expanding market envelope creates room for differentiated value propositions, but it also raises the bar for clinical evidence, reimbursement alignment, and patient-accessibility. Companies that treat this landscape as a static commodity opportunity will likely encounter margin pressure and share erosion. Conversely, organizations that embed clinical validation, delivery-model innovation, and payer-ready documentation into their go-to-market architectures will be positioned to capture premium positioning as treatment algorithms continue to evolve.
What This Research Delivers: A Blueprint for Decision-Making
Our Worldwide Piriformis Syndrome Market study is structured as an actionable intelligence platform rather than a high-level snapshot. It integrates historical baselines, forward-looking projections, and deep qualitative context across the full treatment continuum. The report provides a rigorous examination of how conservative management, minimally invasive procedures, and surgical interventions are competing for clinical adoption, reimbursement favor, and patient preference. It further dissects the distribution ecosystem, mapping how hospitals, specialized clinics, and retail pharmacy channels are shaping access, pricing dynamics, and service integration.
Worldwide Piriformis Syndrome Market
Beyond macro-volume projections, the research delivers operational granularity that executives can translate directly into planning. Key deliverables include:
- A detailed segmentation architecture that clarifies how treatment modalities are performing across clinical settings, patient segments, and delivery pathways
- Competitive benchmarking that evaluates product positioning, procedural differentiation, and commercial strategy across leading participants
- Regulatory and reimbursement intelligence that contextualizes coding guidance, coverage determinations, and the compliance considerations influencing procedure adoption
- Clinical and practice-pattern analysis that synthesizes the role of pharmacotherapy, injectables, neuromodulation devices, and therapy-based protocols within multidisciplinary care models
- Market concentration metrics that illuminate the competitive weight of dominant players and the structural room for entrants and niche innovators
The report is built to support scenario planning. Whether the question is how to prioritize R&D investment, where to expand clinical partnerships, or how to anticipate payer behavior in the next coverage cycle, the analysis is calibrated to translate epidemiological and procedural signals into executable strategy.
Competitive Landscape: Differentiation in a Fragmented Field
The piriformis syndrome market remains comparatively fragmented, with a diverse mix of device innovators, pharmaceutical suppliers, therapy-equipment manufacturers, and specialized procedural providers competing across overlapping value chains. Concentration is moderate rather than consolidated, creating both opportunity and complexity. Incumbents must defend share across multiple modalities, while new entrants can target underserved clinical niches or delivery gaps if they bring credible evidence and clear reimbursement pathways.
Among procedural specialists, Deuk Spine Institute has advanced a distinctive outpatient surgical approach with its patented Piriformis Release technique, emphasizing a minimally invasive, permanent intervention delivered through a small incision. The company’s recent promotion of this procedure highlights a broader industry movement toward outpatient, low-downtime solutions that align with cost-conscious care delivery and patient demand for faster recovery profiles. This shift reflects an important strategic theme: procedural durability and safety narratives are becoming critical commercial assets in a space where clinicians and payers increasingly weigh long-term outcomes against upfront intervention risk.
In the pharmaceutical and injectable segment, multiple global players contribute to conservative and interventional treatment protocols. Allergan, under AbbVie, provides onabotulinumtoxinA as an adjunct to physical therapy, positioning botulinum toxin within a broader spasm-relief and nerve-compression management framework. Bayer and Novartis support the conservative pharmacotherapy backbone through NSAIDs and muscle relaxants, while Sanofi and Teva diversify access through branded and generic pain-management options. Endo Pharmaceuticals adds further depth to the pain-management supply chain, reinforcing the centrality of pharmacological intervention in initial and adjunctive care pathways.
The non-invasive and device-adjacent segment is equally active. King Brand Healthcare Products markets specialized cold and heat therapy wraps tailored to piriformis symptom relief and muscle recovery, while Omron Healthcare supplies TENS technology relevant to non-pharmacological symptom management. Recent device-oriented activity, including the promotion of wearable TENS solutions by Hinge Health, underscores a growing appetite for home-accessible, low-risk modalities that can complement clinical care and extend the patient experience beyond the point of service.
From a strategic standpoint, the competitive picture suggests that future share gains will not come from any single product category alone. The winners are likely to be those who integrate across modalities, align with clinical workflows, and demonstrate value across the patient journey. Companies that operate in silos may find their addressable market constrained by treatment algorithms that increasingly favor combined, stepped-care approaches.
Clinical Evidence, Regulation, and Reimbursement as Strategic Variables
Market growth in this space is inseparable from the evolving evidence and policy environment. Clinical research continues to refine procedural selection and comparative effectiveness. Recent trial activity, including randomized comparisons of ultrasound-guided corticosteroid injection against extracorporeal shockwave therapy, signals an intensifying focus on objective efficacy data and modality optimization. Ongoing trial listings examining post-facilitation stretch, active release techniques, and shockwave-based interventions further indicate that the field is moving toward more rigorous, protocol-level differentiation rather than reliance on anecdotal adoption.
On the regulatory and reimbursement side, policy clarity is both an enabler and a constraint. CMS billing and coding guidance for piriformis muscle injections continues to shape procedural documentation standards, while also emphasizing that certain imaging-guided needle placement methods may not consistently demonstrate additional clinical benefit over landmark-based approaches. This creates a practical compliance consideration for providers and device or injector suppliers: procedural claims and documentation strategies must align with payer expectations around necessity, efficiency, and evidence of marginal value.
Reimbursement determinations are equally influential for injectables. Medicare Local Coverage Determinations have recognized botulinum toxins as reasonable and necessary for certain off-label applications under defined criteria, including refractory piriformis syndrome when appropriate conditions are met. For pharmaceutical participants, this kind of coverage architecture can materially affect adoption ceilings, prescribing behavior, and commercial forecasting. It also reinforces the importance of building payer-facing evidence packages that address not just clinical mechanism, but real-world appropriateness and patient selection logic.
At the same time, the broader treatment philosophy is shifting toward integrated conservative care. Physical therapy approaches encompassing myofascial release, hip abductor strengthening, and neuromuscular inhibition techniques are increasingly viewed as foundational elements, often combined with pharmacotherapy or targeted injections. Surgical intervention, including laparoscopic decompression or piriformis resection, remains generally reserved for severe refractory cases after conservative and interventional options have been exhausted. This stepwise, escalation-based model matters strategically because it influences where volume accumulates, which modalities gain earlier-line adoption, and which companies benefit from downstream procedural demand.
The regulatory environment for injectables is also relevant. Multiple FDA-approved botulinum toxin type A products carry established use in muscle-related conditions applicable to piriformis syndrome management. This approval landscape does not automatically translate into uniform market performance, but it does create a structured backdrop in which clinical differentiation, administration workflows, and reimbursement compatibility become decisive competitive factors.
Strategic Takeaways for 2026 Decision-Makers
As organizations plan their 2026 moves, several themes should dominate the strategic agenda:
Worldwide Tendinitis Treatment Market
- Evidence-led positioning will increasingly separate durable franchises from transient demand. Clinical studies, real-world outcomes, and payer-acceptable documentation are becoming central to adoption velocity.
- Convergence across conservative, interventional, and device-based care is accelerating. Portfolios that can support stepped-care pathways, rather than isolated touchpoints, will be better aligned with clinical reality and reimbursement dynamics.
- Outpatient and minimally invasive options are gaining commercial attention, not only for patient convenience but also for their alignment with cost-conscious delivery models and shorter recovery expectations.
- Reimbursement architecture remains a gatekeeper. Coding guidance, coverage determinations, and documentation expectations will continue to influence which procedures and products can scale efficiently.
- Market fragmentation creates space for specialization. In a moderately concentrated landscape, targeted clinical niches, distinctive service models, and differentiated access strategies can outperform undifferentiated competition.
The strategic question for leaders is not simply whether the piriformis syndrome market is growing, but how to participate in that growth with the right mix of clinical credibility, commercial execution, and payer readiness. Our research is designed to answer that question with the precision required for high-stakes planning.
Access the Full Intelligence Suite
The market figures, segmentation behavior, competitive dynamics, and regulatory signals highlighted here represent only the opening layer of a much larger analytical framework. The complete Worldwide Piriformis Syndrome Market research goes further, delivering detailed segmentation performance, company-level profiling, forward scenarios, and operational guidance tailored to investment, product development, market-entry, and portfolio- optimization decisions. For executives who need a precise map of where value is being created and how competitive pressure is likely to evolve through 2032, the full report is the essential next step. We invite you to access the complete intelligence suite and equip your organization with the strategic clarity required to act decisively in this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com