

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: WIPS Market to Hit $1.25B in 2025, 14.2% CAGR to $3.16B by 2032

Navigating the Invisible Perimeter: Strategic Imperatives in the Global Wireless Intrusion Prevention System Market
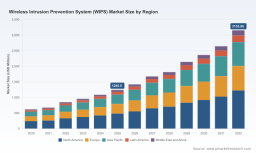
The modern enterprise network perimeter no longer exists as a clearly defined boundary. As organizations accelerate their adoption of hybrid work models, IoT ecosystems, and cloud-native architectures, the wireless layer has become the primary attack surface for sophisticated threat actors. The Worldwide Wireless Intrusion Prevention System (WIPS) Market reflects this fundamental shift in risk geography. Our recent comprehensive analysis indicates that the global market revenue for WIPS solutions reached approximately USD 1,245.5 million in the base year of 2025. Looking forward, the trajectory points toward a significant expansion, with projections estimating the market size to surpass USD 1,420.79 million in 2026 and continuing its ascent to over USD 3,155.06 million by 2032.
This growth is not merely incremental. The compound annual growth rate (CAGR) during the forecast period from 2026 to 2032 is estimated at 14.2 percent. For Chief Information Security Officers (CISOs), procurement leaders, and strategic planners, these figures represent more than just market velocity. They signal a critical inflection point where wireless security transitions from a passive compliance checklist item to an active, intelligence-driven component of the overall security posture. This article serves as an executive primer to our full market research study, outlining the strategic forces shaping the industry, the competitive maneuvers of key market participants, and the regulatory pressures driving adoption.
The Macro-Economic Context of Wireless Security Investment
The expansion of the WIPS market from a valuation of roughly USD 620.45 million in 2020 to the current baseline reflects a maturing recognition of wireless vulnerabilities. During the historical review period from 2020 to 2025, the market demonstrated consistent resilience even amidst broader technology spending fluctuations. The jump from 2024 to 2025 alone indicates a robust demand signal, moving from USD 1,088.3 million to the current 1,245.5 million benchmark.
This trajectory is underpinned by the convergence of several high-stakes dynamics. First, the proliferation of unauthorized and rogue access points remains a persistent threat in dense enterprise environments. Second, the expansion of Wi-Fi 6E and eventual Wi-Fi 7 deployments into the 6 GHz spectrum creates new vectors that require compatible monitoring tools. Third, the financial and reputational cost of a wireless breach continues to escalate, making prevention systems a necessary insurance policy rather than an optional upgrade.
Our forecast data suggests that by 2030, the market will approach USD 2,364.06 million, and by 2032, it will nearly triple the 2025 base size. This growth curve implies that organizations delaying investment in robust wireless intrusion prevention may find themselves technically debt-laden as peers secure their RF spectrums more aggressively.
Regulatory Catalysts and Compliance Pressures
One of the most compelling drivers identified in our research is the tightening regulatory environment. Compliance is no longer just about avoiding fines; it is about maintaining operational eligibility in sectors like finance, healthcare, and government contracting.
In the financial sector, PCI DSS version 4.0 became fully mandatory in April 2025. This update explicitly requires merchants and payment processors to deploy wireless intrusion detection and prevention mechanisms wherever cardholder data is processed. This regulatory mandate effectively forces a significant subset of the retail and hospitality industries to budget for WIPS solutions as a prerequisite for continued payment processing capabilities.
Simultaneously, the healthcare sector faces renewed scrutiny. The U.S. Department of Health and Human Services updated its HIPAA Security Rule guidance in 2025 to include specific recommendations for wireless network monitoring and unauthorized access point detection. Given the sensitivity of protected health information, hospitals and clinic networks are increasingly compelled to integrate WIPS into their broader HIPAA compliance frameworks.
On a broader scale, the European Union's NIS2 Directive, enforced across member states from late 2024, mandates continuous monitoring of network security for operators of essential services. This directive encompasses wireless network perimeters, meaning critical infrastructure providers across Europe must demonstrate active defense mechanisms against wireless intrusions. Furthermore, U.S. Federal agencies operating under FedRAMP and FISMA frameworks have increased their allocation toward wireless monitoring capabilities in IT security budgets, setting a precedent for government contractors to follow suit.
Technological Evolution and Spectrum Dynamics
The technical landscape of WIPS is evolving rapidly alongside regulatory demands. The Federal Communications Commission (FCC) authorization of low-power indoor-only use across the entire 6 GHz band has supported expanded Wi-Fi 6E deployments. While this opens bandwidth for high-speed connectivity, it also requires compatible WIPS solutions capable of monitoring these new spectrum bands for anomalies. Legacy systems designed primarily for the 2.4 GHz and 5 GHz bands may leave blind spots in modern networks.
Additionally, the integration of artificial intelligence and machine learning into wireless security platforms is changing how threats are detected. Traditional signature-based detection is being supplemented by behavioral analytics that can identify rogue devices or anomalous traffic patterns without prior knowledge of specific threat signatures. This shift reduces false positives and allows security teams to focus on genuine risks rather than chasing noise. Our full report details how these technological shifts are influencing vendor roadmaps and customer purchasing criteria.
Competitive Landscape: Key Players and Strategic Moves
The WIPS market is characterized by a mix of specialized security vendors and large networking infrastructure players who embed wireless security into their broader ecosystems. Market concentration data suggests that the top three players hold a significant portion of the market share, with the CR3 percent estimated at 42.15 percent. The top five players collectively command approximately 58.8 percent of the market revenue.
Cisco Systems Inc., headquartered in San Jose, California, remains a dominant force. Their Adaptive Wireless Intrusion Prevention System (aWIPS) is integrated with Catalyst wireless infrastructure and DNA Center. They focus on continuous RF spectrum monitoring, rogue AP detection, and threat containment across Layers 1-3. In April 2025, Cisco announced an expansion of their Meraki cloud management platform with enhanced AI-driven wireless anomaly detection, specifically aimed at strengthening cloud-based WIPS capabilities.
HPE Aruba Networking, based in Santa Clara, California, provides RFProtect WIDS/WIPS designed for monitoring unauthorized access points, clients, and abnormal traffic patterns. Their strategy involves centralized management via Aruba Central integrated into enterprise WLAN infrastructure. Recent technical documentation from early 2025 highlights continued integration and updates to RFProtect for real-time rogue AP and threat monitoring.
Fortinet, Inc., operating out of Sunnyvale, California, delivers WIPS capabilities through its Secure Wireless LAN solutions. They leverage FortiOS for integrated threat detection, prevention, and high-accuracy automation in wireless environments. This integration allows security teams to manage wireless threats alongside their broader Fortinet security fabric.
Worldwide Wireless Acess Point Controller Market
Other notable participants include Extreme Networks, which supplies WIPS functionality in its ExtremeWireless solutions using AirDefense capabilities for continuous protection and policy enforcement. WatchGuard Technologies, based in Seattle, offers cloud-managed WIPS with patented Marker Packet technology in its access points for 24/7 defense against rogue devices and malicious Wi-Fi attacks with low false positives.
Check Point Software Technologies from Tel Aviv integrates wireless threat detection into its Infinity security platform, extending perimeter and network security to wireless environments. NetScout Systems, Inc., based in Westford, Massachusetts, provides wireless intrusion prevention as part of its broader network performance and security portfolio. IBM Corporation offers WIPS-related capabilities through its network security and threat management solutions. Ruckus Networks (CommScope), located in Claremont, North Carolina, includes WIDS/WIPS features in its wireless controllers and access points for rogue device protection and DoS mitigation. Arista Networks, also in Santa Clara, provides WIPS techniques via CloudVision CUE for automated classification of Wi-Fi devices.
Strategic developments in 2024 and 2025 also highlight the importance of government-grade security certifications. In March 2024, the National Security Agency (NSA) released the WIDS/WIPS Annex 2.0.0 for the Commercial Solutions for Classified (CSfC) program. This release supports secure wireless monitoring in government environments, setting a benchmark for security efficacy that influences both public sector and high-security commercial deployments.
Market Structure: Components and Deployment Trends
Understanding how organizations procure WIPS solutions is critical for strategic planning. The market is segmented by components including hardware, software, and services. Our analysis indicates that hardware components continue to hold a substantial share of the revenue mix, reflecting the physical nature of many wireless access points and sensors required for comprehensive coverage. However, the software segment is gaining traction as virtualization and cloud management become preferred methods for deployment and policy orchestration. Services also represent a significant portion of the market, encompassing installation, tuning, and managed security services.
Deployment models are shifting toward cloud-based solutions. Our data shows that cloud-based deployment captures a larger revenue share compared to on-premise solutions. This trend aligns with the broader industry movement toward SaaS and cloud-native security operations. Cloud-based WIPS allows for centralized visibility across distributed enterprise locations, remote offices, and branch networks without the need for on-site maintenance of security appliances. On-premise deployments remain relevant for organizations with strict data sovereignty requirements or specific latency constraints, but the growth momentum favors scalable cloud architectures.
Regional dynamics also play a crucial role in market distribution. North America maintains a leading position in market revenue, driven by high adoption rates in enterprise and government sectors. Europe follows with significant demand fueled by NIS2 compliance and established enterprise infrastructure. The Asia Pacific region represents a high-growth area as digital transformation initiatives accelerate across key economies. Latin America and the Middle East and Africa are emerging markets where infrastructure development and security awareness are beginning to drive demand, though at different maturity levels compared to North America and Europe.
Strategic Implications for Decision Makers
For enterprise leaders evaluating their security roadmap for 2026 and beyond, the WIPS market data offers several key takeaways. First, the 14.2 percent CAGR suggests that the market is expanding faster than general IT security spending in many categories. This implies that wireless security is becoming a priority investment area. Organizations that have treated wireless security as an afterthought to wired network security must recalibrate their budgets.
Second, the concentration of market share among the top five vendors indicates a mature competitive landscape. While this provides stability, it also means that differentiation often comes down to integration capabilities, AI-driven analytics, and ease of management. Procurement teams should evaluate not just the immediate detection capabilities but the long-term roadmap for spectrum monitoring as Wi-Fi 7 and beyond emerge.
Third, the regulatory tailwinds are strong and likely to persist. With PCI DSS, HIPAA, and NIS2 creating mandatory requirements for wireless monitoring, compliance teams should work closely with security architects to ensure that WIPS deployments meet specific regulatory language regarding detection and prevention. Non-compliance risks are not just theoretical; they are operational blockers.
Finally, the shift toward cloud-based management and AI-driven anomaly detection suggests that operational overhead can be reduced while improving detection accuracy. Leaders should seek solutions that minimize false positives, as alert fatigue remains a major challenge in security operations centers. The ability to automate threat containment, such as isolating rogue devices without manual intervention, is becoming a standard expectation rather than a luxury feature.
Worldwide Wireless Intrusion Prevention System (WIPS) Market
Conclusion: The Value of Granular Intelligence
The global Wireless Intrusion Prevention System market is at a pivotal stage. Driven by regulatory mandates, technological advancements in spectrum usage, and the increasing sophistication of wireless threats, the market is poised for sustained growth through 2032. The transition from passive monitoring to active prevention is now the standard, and the integration of wireless security into broader network and security fabrics is essential for resilient operations.
While this overview provides a strategic snapshot of market size, growth rates, competitive players, and regulatory drivers, it only scratches the surface of the available intelligence. Understanding which segments offer the highest ROI, the specific adoption rates across industry verticals, and the detailed pricing dynamics requires deeper analysis. Our full Worldwide Wireless Intrusion Prevention System Market research report contains comprehensive segmentation data, granular regional breakdowns, and detailed company profiles that go beyond these high-level trends. For organizations seeking to build a precise procurement strategy or understand their competitive positioning in this evolving landscape, accessing the complete dataset is essential. The invisible perimeter is expanding, and so too must the depth of your strategic insight.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com