

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Androgen Replacement Therapy Market to Hit $3,591M by 2032 at 5.8% CAGR

Strategic Intelligence for the Next Wave: Inside the Worldwide Androgen Replacement Therapy Market Outlook 2026-2032
As the global healthcare landscape shifts toward precision endocrinology and expanded therapeutic indications, the androgen replacement therapy (ART) sector stands at a pivotal inflection point. The recent publication of our Worldwide Androgen Replacement Therapy Market research delivers a comprehensive, forward-looking intelligence framework designed specifically to inform enterprise strategy, capital allocation, and commercial execution throughout the 2026-2032 forecast horizon. Drawing on rigorous historical analysis spanning 2020 through base year 2025, the study translates granular market mechanics into actionable decision support for pharmaceutical leaders, investors, and therapeutic development teams.
This introduction outlines the strategic architecture of the full report, demonstrates how macro-level trajectory and structural concentration patterns should reshape executive planning, and previews the operational intelligence embedded across every analytical module. Readers are invited to explore the complete dataset, proprietary sizing tables, and company-level competitive assessments by visiting the source page, where the full intelligence package is available for immediate download.
Macro Trajectory: Reading the Growth Curve Beyond Simple CAGR
The worldwide androgen replacement therapy market has demonstrated resilient expansion across the historical window, with measured revenues progressing from approximately USD 1,850 million in 2020 to a base-year valuation of USD 2,420 million in 2025. Looking ahead, the forecast sequence projects a steady upward trajectory, culminating in a 2032 valuation approaching USD 3,591 million. This evolution reflects a compound annual growth rate of 5.8 percent, a figure that masks significant nuance when examined through the lens of commercial cadence, formulation transitions, and shifting prescribing behaviors.
For executive teams, the strategic implication of this growth profile is not merely revenue forecasting but rather the identification of inflection windows where competitive positioning, regulatory alignment, and product lifecycle timing converge. The forecast period captures a critical bridge between established hypogonadism management and emerging therapeutic applications, making it essential for organizations to calibrate pipeline investments, manufacturing capacity, and go-to-market resources without prematurely locking into static assumptions.
Worldwide Androgen Replacement Therapy Market
The historical volatility observed across recent years underscores the importance of scenario-based planning. Fluctuations in commercial uptake, supply chain recalibration, and evolving safety communication cycles have collectively reshaped demand patterns. The full research deconstructs these movements with transparent methodology, enabling strategists to differentiate between temporary pricing noise and durable structural shifts that warrant long-term capital deployment.
Segment Architecture: Navigating Formulation, Indication, and Regional Dynamics
Understanding how value distributes across therapeutic modalities, clinical indications, and geographic territories is central to effective portfolio strategy. The research examines the androgen replacement ecosystem through three structural lenses: product typology, clinical application, and regional footprint. Each dimension carries distinct commercial characteristics, competitive intensity, and pricing behavior that directly influence market entry timing, asset prioritization, and lifecycle management.
Formulation Pathways and Delivery Innovation
The product landscape spans gel-based systems, injectable platforms, transdermal patches, oral capsules, and implantable or ancillary delivery formats. The research maps the commercial footprint of each category, evaluating formulation advantages, adherence considerations, manufacturing complexity, and reimbursement positioning. Gel-based and injectable modalities continue to anchor a substantial share of total revenue, yet the strategic narrative is increasingly defined by the maturation of oral platforms and the iterative refinement of long-acting delivery systems.
Strategists should note that formulation preference is not uniform across prescriber segments or payer environments. The report dissects how clinical workflows, pharmacy distribution models, and patient convenience factors interact to shape category momentum, providing a practical framework for assessing where incremental innovation or line-extension strategies can generate outsized commercial returns.
Clinical Indications and Therapeutic Breadth
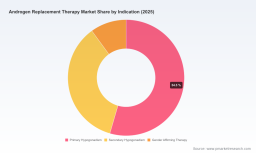
Demand for androgen replacement therapy is anchored primarily in the management of primary and secondary hypogonadism, with an additional segment represented by gender-affirming therapeutic applications. The research quantifies the relative scale of these indication clusters while evaluating how prescribing guidelines, clinical evidence maturity, and payer classification influence adoption velocity. Companies evaluating expansion opportunities must understand not only where current revenue concentrates, but also how clinical narrative shifts and expert consensus evolution can reposition certain formulations within broader endocrine care pathways.
A critical strategic question concerns the boundary between established labeled indications and evolving clinical practice. The report explores how regulatory framing, real-world evidence generation, and specialty society guidance collectively determine which patient populations are accessible under current commercial models, and where near-term label evolution could unlock incremental demand.
Geographic Distribution and Regional Commercial Profiles
The worldwide market reflects a multi-regional architecture with pronounced variation in prescriber density, pricing environment, generic penetration, and reimbursement structure. North American commercial dynamics continue to exert substantial influence on global revenue composition, while European markets operate under distinct procurement and HTA frameworks that shape volume and margin expectations. Asia Pacific, Latin America, and the Middle East and Africa regions present heterogeneous opportunity sets, each requiring tailored market-access strategies, supply chain configurations, and brand-building approaches.
Rather than presenting static regional snapshots, the full study maps how regional growth drivers diverge over the forecast window. This includes analysis of local manufacturing presence, import dependencies, pricing regulation intensity, and the pace at which generic competition compresses branded share. For multinational operators, this regional granularity is essential for prioritizing in-licensing opportunities, localization investments, and partnership structures.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The androgen replacement therapy market exhibits meaningful concentration among established specialty and generic manufacturers, with the top three participants accounting for approximately 52.4 percent of total revenue and the top five reaching roughly 68.15 percent. This structural concentration indicates that scale advantages, regulatory experience, and entrenched prescriber relationships continue to matter, while also leaving room for focused innovators to capture share through differentiated delivery technologies, oral platform maturation, or niche indication alignment.
Hormone Replacement Therapy (HRT) Market
The research profiles a diverse set of organizations shaping the competitive field. Life science and specialty pharmaceutical leaders including AbbVie Inc., Bayer AG, Endo International plc, Pfizer Inc., Eli Lilly and Company, Novartis AG, and Viatris Inc. maintain significant footprint across branded, specialty, and legacy testosterone portfolios. Their strategic postures differ by geographic emphasis, formulation focus, and reliance on in-house manufacturing versus partnered distribution models.
At the same time, companies such as Lipocine Inc. and Clarus Therapeutics have advanced oral testosterone undecanoate platforms, reflecting broader industry interest in patient-friendly delivery options and oral formulation credibility. The report assesses how these assets interact with existing gel and injectable categories, where clinical differentiation is most defensible, and how payer and prescriber acceptance evolves as oral options gain visibility.
Generic and value-oriented manufacturers including Perrigo Company plc, Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd, Teva Pharmaceutical Industries Ltd., and Acerus Pharmaceuticals Corporation represent an additional competitive layer. Their presence influences price erosion patterns, formulary positioning, and the speed at which branded differentiation must be sustained. The study evaluates generic entry timing, bioequivalence pathways, and regional availability as key variables that determine the competitive runway for branded assets in each market.
Regulatory and Clinical Dynamics Shaping the 2026-2032 Window
Regulatory signaling and evolving clinical guidance are not peripheral concerns for this market; they are central drivers of demand expansion, label scope, and commercial risk. The research integrates a series of important regulatory developments that directly affect how companies should plan indications, safety communications, and lifecycle investment.
In February 2025, the FDA updated class-wide labeling for approved testosterone products to incorporate TRAVERSE trial data, removing certain cardiovascular warnings while adding blood pressure-related information. This revision altered the safety narrative that had historically constrained prescribing behavior and influenced payer discussions. The full report evaluates how this labeling adjustment interacts with physician confidence, patient selection criteria, and downstream demand patterns across both branded and generic segments.
During December 2025, the FDA convened an expert panel on testosterone replacement therapy for men to review evidence and clinical use considerations. Panel deliberations of this nature frequently precede label evolution, guideline updates, and shifts in medical education emphasis. The research situates this panel within the broader trend of evidence refinement and explores what changes in expert consensus could mean for indication expansion conversations, marketing claims, and clinical adoption.
A notable development emerged in April 2026, when the FDA encouraged sponsors of approved testosterone replacement therapy products to pursue supplemental new drug applications for a potential new indication addressing low libido in men with idiopathic hypogonadism. The agency also signaled a timeframe for interested holders to initiate contact regarding supplemental applications. This regulatory signal, if acted upon and substantiated through robust clinical programs, could meaningfully broaden the addressable patient population beyond classical structural or genetic hypogonadism cases. The report analyzes the strategic significance of this encouragement, the evidentiary bar that remains, and the commercial implications for companies positioned to move quickly on supplemental development or label-extension planning.
The broader reimbursement context reinforces the importance of indication clarity. Current FDA-approved TRT products are indicated for hypogonadism associated with known structural or genetic causes, while broader idiopathic cases remain outside standard labeled indications or under review for potential expansion. Understanding this boundary is essential for forecasting realistic demand, aligning payer engagement strategies, and prioritizing clinical programs that can support future label evolution without overpromising near-term uptake.
Operational and Supply-Side Realities Driving Market Execution
Commercial strategy in the androgen replacement therapy market cannot be decoupled from upstream supply considerations. The testosterone active pharmaceutical ingredient segment has been valued at approximately USD 1,865 million in 2024, with continued growth projected as demand in hormone replacement therapy and related endocrine applications expands. This upstream dynamic shapes cost of goods exposure, manufacturing capacity planning, and the resilience of supply chains against regional disruptions.
The research addresses how API availability, formulation technology, and manufacturing scale intersect with each product category’s competitiveness. For oral platforms, absorption profiles, formulation stability, and dosing consistency are commercially decisive. For gels and injectables, manufacturing consistency, packaging integrity, and cold-chain or storage requirements influence both cost structure and market access. For implants and ancillary formats, procedural adoption patterns and clinician training needs create distinct go-to-market requirements.
Strategists evaluating capacity expansion, contract manufacturing partnerships, or regional production localization will find detailed discussion of where supply constraints are most likely to emerge and how different product types absorb input cost volatility. This operational lens is critical for organizations seeking to protect margins while scaling commercial presence across multiple territories.
What the Full Report Delivers: A Practical Intelligence Blueprint
This research is structured to translate market complexity into executable intelligence. Beyond the headline sizing and growth trajectory, the full study provides a multi-layered analytical toolkit designed for cross-functional use by corporate strategy, business development, commercial planning, and investment teams.
Key operational elements embedded in the report include:
- Comprehensive historical and forecast sizing with transparent methodology, enabling users to validate assumptions and stress-test internal models against external benchmarks.
- Segment-level analysis across product type, indication, and region that clarifies where value is created, where competition is intensifying, and where whitespace remains for differentiated positioning.
- Competitive profiling of major participants, including commercial footprint summaries, formulation emphasis, and strategic posture that help benchmark relative advantage and identify partnership or acquisition targets.
- Regulatory and clinical timeline mapping that connects FDA labeling updates, expert panel activity, and potential supplemental indication pathways to near-term and mid-term commercial implications.
- Market concentration and share structure analysis that informs pricing strategy, formulary positioning, and the durability of branded differentiation against generic and value-tier competition.
- Practical guidance on how macroeconomic demand drivers, reimbursement dynamics, API supply conditions, and prescriber behavior interact to shape realistic execution scenarios across the 2026-2032 window.
The study is designed to support scenario planning rather than static forecasting. Readers can use the framework to model how different regulatory outcomes, label-extension successes, generic entry timing, and regional reimbursement shifts would alter revenue potential, competitive exposure, and resource prioritization.
Strategic Imperatives for 2026 Enterprise Decision-Making
As organizations enter 2026, the androgen replacement therapy market requires a more dynamic planning posture than historical category maturity might suggest. The convergence of updated safety labeling, expert panel deliberation, and regulatory encouragement for potential new indication pathways creates a period in which early strategic positioning can meaningfully influence share capture and lifecycle optionality.
Several strategic priorities emerge from the macro and structural evidence reviewed in the report:
- Assess which formulation categories align with your organization’s manufacturing strengths and commercial reach, then prioritize investments where adherence advantages, prescriber preference, and payer acceptance reinforce one another.
- Monitor the regulatory trajectory around idiopathic hypogonadism and low libido as a potential indication expansion vector, evaluating whether your pipeline, clinical evidence base, and regulatory capabilities can support timely supplemental activity if the pathway matures.
- Model generic penetration and price erosion across regional markets with realistic timing assumptions, ensuring that branded differentiation strategies are calibrated to the pace at which value-tier competitors reshape formulary dynamics.
- Integrate API supply and manufacturing resilience into commercial planning, particularly where regional demand growth may outpace local capacity or where formulation complexity introduces cost volatility.
- Align medical affairs and payer engagement strategies with the current labeled indication boundary, while preparing evidence-generation and education programs that can support label evolution without relying on assumptions that exceed current regulatory framing.
Conclusion: Turning Market Intelligence into Confident Action
The Worldwide Androgen Replacement Therapy Market research is built for decision-makers who need more than a top-line growth estimate. It offers a structured, evidence-grounded view of how formulation shifts, indication dynamics, regional heterogeneity, regulatory evolution, and competitive concentration interact to shape the commercial landscape through 2032. By connecting historical performance to forward-looking scenario analysis, the study equips organizations to allocate resources with greater precision and to anticipate inflection points rather than react to them.
To explore the complete market sizing tables, region- and segment-level analysis, company competitive profiles, regulatory timeline mapping, and scenario-ready forecasting detail, request the full report through the source page linked below. The complete intelligence package is intended for teams seeking to convert market complexity into executable strategy throughout the 2026-2032 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Androgen Replacement Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com