

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Fabrication Outsourcing Set for $120.66 Billion by 2032

Navigating the Metal Fabrication Outsourcing Landscape: Strategic Intelligence for 2026 and Beyond
The global industrial ecosystem is undergoing a structural transformation. As manufacturers confront rising complexity in supply chains, shifting geopolitical trade dynamics, and the imperative to scale production without bloating fixed assets, metal fabrication outsourcing has evolved from a tactical cost-saving measure into a core strategic capability. PW Consulting's latest Worldwide Metal Fabrication Outsourcing Services Market report offers decision-makers a rigorously validated, forward-looking intelligence framework designed specifically for 2026 planning cycles. This executive summary outlines the strategic architecture of the study, demonstrates how macro and micro market signals intersect, and explains why organizational leaders should treat outsourced fabrication not as a procurement line item, but as a competitive lever.
The report is built on an analytical foundation that tracks historical performance from 2020 through 2025 and projects market trajectories across a seven-year forecast horizon extending to 2032. By anchoring forecasts in verified historical baselines and stress-testing growth assumptions against multiple macroeconomic scenarios, the study delivers the precision required for capital allocation, partnership structuring, and regional capacity planning. The overarching market trajectory reflects sustained expansion, with the sector demonstrating a compound annual growth rate of 5.29 percent across the forecast window. This growth is not linear or isolated; it is shaped by divergent regional maturity curves, evolving service-type demand, and industry-specific procurement behaviors that the full report unpacks in granular detail. Decision-makers who rely on aggregate headlines alone risk misaligning sourcing strategies with the underlying demand architecture. This publication closes that gap.
Why 2026 Demands a Fresh Strategic Lens
The 2026 operating environment presents a confluence of forces that directly reshape how enterprises evaluate, contract, and manage external metal fabrication partners. Raw material benchmarks continue to fluctuate, skilled labor availability remains constrained in key production corridors, and capital allocation priorities are being reallocated toward automation, prefabrication, and digital supply chain integration. These dynamics do not operate in isolation. They interact with broader macro trends, including supply chain diversification, regionalization of manufacturing footprints, and the accelerating energy transition, which collectively influence where capacity is built, which capabilities are outsourced, and how risk is distributed across vendor networks.
The report contextualizes these forces through a structured dynamics framework that separates transient market noise from structural shifts. For instance, pricing signals in ferrous commodities and metallurgical inputs create short-term margin volatility for fabrication service providers, but the longer-term implication lies in how suppliers hedge input risk, adjust pricing models, and invest in yield optimization. Similarly, persistent shortages of skilled welders, machinists, and sheet metal technicians are accelerating adoption of robotic welding cells, automated nesting systems, and digital work-instruction platforms. Enterprises evaluating outsourcing partners must therefore assess not only unit pricing, but also a vendor's automation maturity, workforce retention strategy, and ability to maintain throughput when labor markets tighten.
Reshoring and supply chain diversification further complicate sourcing calculus. Organizations that previously optimized for single-region cost advantages are now recalibrating around resilience, tariff exposure, lead-time predictability, and alignment with local content requirements. The study maps how these considerations influence outsourcing decisions across different industrial verticals and geography clusters, enabling leaders to model trade-off scenarios rather than react to policy or cost shocks after contracts are signed.
Decoding the Market Architecture: Structure Without Noise
A central value of this research lies in its disciplined segmentation logic. Rather than presenting oversimplified top-line figures, the report decomposes the market along three interdependent axes: geographic distribution, service-type capability, and end-use industry demand. This tripartite structure allows executives to diagnose where growth is genuinely converging and where apparent opportunities may be overstated by aggregated reporting.
Geographically, the study examines how demand clusters across major regional corridors, distinguishing between mature markets with stable outsourcing penetration and high-growth regions where capacity expansion, infrastructure investment, and industrial policy are reshaping vendor landscapes. The analysis highlights how regional cost structures, logistics constraints, and local regulatory environments influence the attractiveness of different sourcing models. Instead of isolating single-region percentages, the report frames regional performance in relative terms, helping strategists identify which corridors offer scale, which offer speed, and which offer specialized capability that may justify premium engagement.
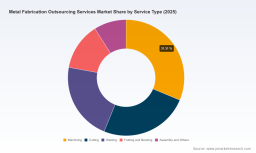
On the service-type dimension, the research categorizes outsourced fabrication activity into distinct operational modalities, including machining, cutting, welding, folding and bending, and assembly-plus-other support functions. This breakdown matters because each service type carries different capital intensity, cycle-time profiles, quality-control requirements, and automation potential. A procurement team focused solely on total contract value may overlook the fact that a partner's competitive advantage in precision machining does not automatically translate into cost leadership in structural welding or complex assembly integration. By separating these modalities, the report equips leaders to match service-type strengths with project requirements and to structure multi-vendor ecosystems where each partner plays to a defined capability core.
The end-use industry lens further sharpens strategic relevance. Demand from automotive, aerospace and defense, construction and infrastructure, industrial machinery, energy and power, and other sectors follows distinct procurement rhythms, qualification standards, and volume profiles. High-tolerance aerospace and defense work, for example, places a premium on certified processes, traceability, and engineering collaboration, while construction and infrastructure engagements may prioritize scale, structural component handling, and schedule reliability. Automotive and industrial machinery buyers often balance repeatable precision with cost pressure and changing program cycles. The study's industry-level analysis enables leaders to anticipate where outsourcing demand will intensify, which performance criteria will matter most, and how vendor positioning differs by vertical.
Competitive Landscape: Capability, Positioning, and Strategic Signaling
Market growth is being shaped by a diverse set of participants that range from specialized regional fabricators to global industrial groups and digital manufacturing platforms. The report profiles leading organizations and evaluates how their service portfolios, geographic reach, and recent strategic moves inform broader competitive dynamics. Rather than treating competitors as a static roster, the analysis interprets company activity as signals about where the market is heading and which capabilities are becoming table stakes.
Firms such as Mayville Engineering Company, O'Neal Manufacturing Services, and BTD Manufacturing illustrate the continued importance of domestically anchored, application-focused fabricators that serve heavy equipment, construction, mining, agriculture, and recreational vehicle end markets. Their service emphasis on design support, prototyping, sheet metal fabrication, structural components, and value-added assembly reflects a market where engineering collaboration and sector-specific know-how remain differentiation drivers. Recent capability expansions, including targeted acquisitions and new business wins in metal enclosures and precision components, indicate that scale and service breadth are increasingly intertwined. The research examines how such moves affect pricing power, delivery reliability, and the ability to absorb volatile program demand without sacrificing quality.
Worldwide Metal Fabrication Outsourcing Services Market
Worldwide Intellectual Property Outsourcing Services Market
Global industrial players bring a different strategic posture. Organizations including ThyssenKrupp AG, Caterpillar Inc., Liebherr Group, Nucor Corporation, and XCMG Group operate extensive manufacturing and fabrication networks that span multiple geographies and industrial applications. Their outsourcing-related activities often intersect with internal production optimization, component supply strategies, and large-scale structural or precision fabrication requirements. For buyers, these players can offer integration advantages, program resilience, and access to broad engineering resources. For competitors, they represent both benchmark capabilities and potential channel partners or capacity constraints. The report assesses how such multinational profiles influence regional pricing dynamics, qualification expectations, and the strategic calculus of companies deciding whether to source from specialized independents or broader industrial integrators.
The competitive picture also includes digital-first and on-demand models. Protolabs and Xometry demonstrate how rapid-turn custom sheet metal fabrication, CNC machining, welding access, and marketplace-based supplier routing are reshaping expectations around speed, minimum order flexibility, and transparent quoting. These platforms do not replace traditional fabrication relationships, but they recalibrate baseline expectations for responsiveness and access. The study explores how digital procurement channels interact with traditional outsourcing contracts, where they create incremental value, and where their limitations in complex, high-tolerance, or large-scale projects still require hands-on supplier management.
Market concentration metrics provide additional context. With a relatively fragmented competitive structure at the top, no single vendor or small group of vendors dominates the overall market, which means buyers retain meaningful leverage to curate multi-source strategies and tailor partnerships to specific program needs. At the same time, the presence of capable specialists and large integrated players creates a dynamic environment where consolidation, capability acquisition, and service-line repositioning are likely to continue. The report interprets concentration data not as a static snapshot, but as a starting point for evaluating partnership risk, negotiation posture, and long-term sourcing architecture.
Inside the Report: Practical Intelligence for Operating Decisions
This research is designed for immediate operational application. Beyond macro-level forecasting, the report delivers structured analytical modules that support sourcing strategy, capability evaluation, risk assessment, and investment prioritization. The study integrates historical performance data, forward projections, service-type and industry-level demand mapping, regional dynamics, competitive profiling, and a set of qualitative market drivers that shape negotiation and contracting behavior.
Practitioners will find actionable frameworks for identifying which outsourcing capabilities are becoming commoditized and which remain differentiated by engineering rigor, certification depth, scale, or automation maturity. The analysis helps leaders determine where to consolidate spend for leverage, where to diversify for resilience, and where to pursue long-term partnerships that include joint process improvement or capacity planning. It also provides the context needed to interpret vendor proposals critically, especially when pricing, lead times, and capability claims diverge across suppliers.
A distinctive feature of the report is its integration of market dynamics with real-world operational considerations. Input cost trajectories, labor availability, automation adoption, energy-transition-driven investment, and supply chain restructuring are each evaluated for their implications on vendor behavior and buyer decision-making. By connecting these drivers to sourcing outcomes, the study enables executives to move beyond static price comparisons and evaluate total value, including reliability, quality consistency, engineering support, and the ability to adapt as program specifications evolve.
Translating Intelligence into 2026 Action
For organizations preparing for 2026, the strategic question is no longer whether to outsource metal fabrication, but how to structure outsourcing relationships so they reinforce broader business objectives. The report supports that transition by converting market intelligence into decision-ready guidance across several priority areas.
- Align outsourcing strategy with supply chain reconfiguration plans, including regional diversification, tariff exposure management, and lead-time reliability targets.
- Evaluate vendor capabilities against project-specific service-type requirements, recognizing that machining, cutting, welding, forming, and assembly each carry distinct operational risk and quality profiles.
- Incorporate automation maturity and workforce stability into supplier selection criteria, especially where skilled labor constraints could affect throughput or consistency.
- Use industry-level demand insights to anticipate qualification requirements, volume patterns, and engineering collaboration expectations in sectors such as automotive, aerospace and defense, construction and infrastructure, industrial machinery, and energy and power.
- Identify where digital and on-demand models can complement traditional partnerships for rapid prototyping, low-volume production, or intermittent demand spikes without compromising the integrity of core supply agreements.
- Monitor competitive and structural signals, including capability acquisitions, service-line expansions, and concentration trends, to anticipate shifts in pricing dynamics and vendor availability.
The study also provides the analytical discipline needed to separate short-term cost movements from durable structural advantages. A vendor offering aggressive unit pricing may not be the best long-term partner if its process controls, engineering support, or automation roadmap do not align with future program demands. Conversely, a partner with stronger capability depth may justify a premium when total cost of ownership, schedule certainty, and reduced rework are factored in. The report helps leaders make those trade-offs explicit.
Positioning for the Next Phase of Market Evolution
The worldwide metal fabrication outsourcing services market is advancing through a period of capability redefinition. Growth is being shaped not only by demand expansion, but also by how efficiently organizations can access specialized fabrication capacity, integrate external partners into product development cycles, and adapt to changing input costs, labor conditions, and geopolitical realities. The firms that succeed in this environment will be those that treat outsourcing as a design variable in their broader operating model rather than a reactive procurement fix.
PW Consulting's Worldwide Metal Fabrication Outsourcing Services Market report provides the evidentiary foundation required to make that shift with confidence. It combines rigorous forecasting, multi-axis segmentation, competitive intelligence, and market-dynamics analysis into a single strategic reference. The result is a resource that supports informed negotiation, smarter vendor selection, and more resilient sourcing architecture as enterprises move through 2026 and beyond.
To access the complete dataset, detailed segmentation breakdowns, full company profiles, and the underlying analytical models that support these conclusions, request the full report through the PW Consulting research portal. The executive view presented here is intended to establish strategic context and demonstrate the depth of the analysis; the complete study delivers the granular intelligence necessary for precise planning, benchmarking, and execution.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fabrication Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com