

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plexiform Neurofibromas Market Reaches $720M in 2025, 17.95% CAGR to $2.28B by 2032

Strategic Intelligence for the Plexiform Neurofibromas Treatment Market: Navigating the 2026 to 2032 Opportunity Horizon
Executive Overview
Plexiform neurofibromas represent one of the most complex and clinically challenging manifestations of neurofibromatosis type 1, a genetic disorder that affects more than a quarter million individuals across major global markets. For decades, surgical resection remained the primary intervention, yet the infiltrative nature of these tumors often rendered complete removal impossible without significant morbidity. The therapeutic paradigm has shifted decisively in recent years, driven by the emergence of targeted small molecule inhibitors that address the underlying RAS-MAPK pathway dysregulation. This transformation has created a high-growth market segment that demands rigorous strategic analysis, precise forecasting, and a clear understanding of competitive positioning.
This market research study provides a comprehensive evaluation of the worldwide plexiform neurofibromas treatment market, offering decision-makers the granular intelligence required to allocate resources, shape pipeline strategies, and anticipate regulatory shifts. The analysis spans historical performance from 2020 through the base year of 2025 and extends a detailed forecast horizon to 2032, capturing the inflection points that define this rapidly evolving landscape.
Macro Market Dynamics and Growth Trajectory
The global market for plexiform neurofibromas treatments has undergone a profound expansion over the past half-decade. Historical revenue data reveals a trajectory that begins at 42.15 million USD in 2020, accelerates sharply to 109.83 million USD in 2021, and continues its upward momentum through successive valuation milestones reaching 210.27 million USD in 2022 and 404.65 million USD in 2023. By the base year of 2025, the market had scaled to 720.0 million USD, reflecting the compounding effect of regulatory approvals, expanded labeling, and increasing clinical adoption of targeted therapies.
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Looking forward, the forecast period from 2026 to 2032 projects sustained and robust growth. The market is expected to reach 896.65 million USD in 2026, climbing steadily through intermediate forecast years to 1,289.4 million USD in 2028, then accelerating further toward 1,584.17 million USD by 2029. The compound annual growth rate across the full forecast window is calculated at 17.95 percent, underscoring the structural momentum behind this therapeutic category. The end-state valuation for 2032 is projected at 2,284.32 million USD. These figures illustrate a market that is not merely growing but fundamentally maturing as addressable patient populations expand and reimbursement frameworks adapt to support high-cost targeted interventions.
Throughout this narrative, all monetary values are expressed in United States dollars and measured in millions. Readers seeking the precise year-by-year breakdowns, sensitivity analyses, and scenario modeling that underpin these trajectories will find the complete dataset within the full report, where every assumption and methodological choice is transparently documented.
Segmentation Architecture and Addressable Patient Pools
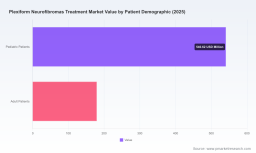
Understanding how revenue distributes across therapeutic modalities, patient demographics, and geographic regions is essential for strategic planning. The analysis segments the market along three critical dimensions that reflect both clinical reality and commercial opportunity. By therapy type, targeted molecular inhibitors dominate the revenue landscape, with surgical intervention and chemotherapy-based approaches comprising the remaining share. By patient demographic, pediatric populations represent a substantial portion of the addressable market, while adult patients form a dynamically growing cohort as diagnostic awareness improves and expanded indications gain regulatory traction. Regional analysis further delineates market density across North America, Europe, Asia Pacific, and Rest of World, highlighting variations in treatment access, clinical infrastructure, and pricing environments.
These segmentation splits are not merely descriptive; they reveal where investment, partnership, and commercialization efforts should be concentrated. The detailed percentage allocations, absolute values for each category, and the interplay between demographic shifts and regional adoption curves constitute the analytical core of the study. Accessing the complete segmentation tables and cross-referenced breakdowns will allow stakeholders to pinpoint the highest-probability growth pockets and calibrate their market entry or expansion strategies accordingly.
Worldwide Plexiform Neurofibromas Treatment Market
Competitive Landscape and Key Player Profiles
The plexiform neurofibromas treatment market is characterized by a highly concentrated competitive structure. Market concentration metrics indicate that the top three firms command 88.4 percent of total revenue, while the top five entities collectively represent 94.15 percent. This oligopolistic dynamic reflects the regulatory and clinical barriers associated with developing targeted inhibitors for rare neurofibromatosis indications, as well as the significant clinical data requirements imposed by health authorities worldwide.
Two companies stand at the forefront of this market and are profiled in depth within the research. AstraZeneca Pharmaceuticals LP, operating in collaboration with Merck & Co., Inc., markets Koselugo, known generically as selumetinib, an oral MEK inhibitor approved for pediatric patients one year of age and older as well as adults with neurofibromatosis type 1 who present with symptomatic, inoperable plexiform neurofibromas. SpringWorks Therapeutics, Inc. markets Gomekli, or mirdametinib, an oral MEK1/2 inhibitor approved for adult and pediatric patients two years and older with symptomatic plexiform neurofibromas that are not amenable to complete resection. Both products have secured pivotal regulatory milestones that reshaped treatment standards and established the MEK inhibition pathway as the cornerstone of modern pharmacotherapy for this indication.
Beyond these market leaders, the competitive field includes emerging candidates and development-stage assets that may influence future share dynamics. The report includes detailed competitive profiling that examines product positioning, clinical differentiation, geographic rollout strategies, and anticipated head-to-head competition. Stakeholders evaluating partnership opportunities, licensing deals, or market entry timing will benefit from the structured comparison of strategic capabilities and pipeline trajectories provided in the full analysis.
Regulatory and Reimbursement Dynamics Shaping 2026
The period surrounding 2026 has been defined by a series of high-impact regulatory actions that directly expand the patient populations eligible for targeted treatment. In January 2026, the FDA expanded its approval of Koselugo granules and capsules to include pediatric patients one year of age and older with neurofibromatosis type 1 and symptomatic, inoperable plexiform neurofibromas. Concurrently, the European Commission approved the therapy for children aged one to less than seven years, as well as for patients experiencing swallowing difficulties, broadening the addressable demographic across key international markets. In November 2025, the FDA had already approved Koselugo for adults with neurofibromatosis type 1 and symptomatic, inoperable plexiform neurofibromas based on the KOMET Phase III trial, setting the stage for continued adult market penetration.
Further extending global reach, AstraZeneca announced in March 2026 that Koselugo received regulatory approval in Canada for adult patients meeting the same clinical criteria, supported by KOMET Phase III data that demonstrated a 20 percent objective response rate. These sequential approvals illustrate a deliberate regulatory strategy that incrementally widens labeling, enhances payer confidence, and accelerates real-world utilization.
On the competing side, SpringWorks Therapeutics achieved FDA approval in February 2025 for Gomekli in adult and pediatric patients two years and older with symptomatic plexiform neurofibromas not amenable to complete resection, based on the ReNeu Phase IIb trial. The presence of two approved targeted therapies specifically indicated for symptomatic, inoperable neurofibromatosis type 1-associated plexiform neurofibromas in their respective approved age groups has established a new standard of care and intensified the focus on differentiation through tolerability, dosing convenience, and long-term safety data.
Additional industry dynamics continue to reshape the environment. The FDA granted Fast Track designation to PAS-004, a next-generation macrocyclic MEK inhibitor developed by Pasithea Therapeutics, for the treatment of neurofibromatosis type 1-associated plexiform neurofibromas causing significant morbidity. Fast Track status signals regulatory receptivity to innovation in this space and may accelerate development timelines for next-wave entrants. Together, these regulatory and reimbursement developments create a market environment where label expansion, patient identification, and access optimization are decisive factors in capturing growth.
Real-World Clinical Considerations and Market Access Realities
While regulatory approvals unlock theoretical market potential, commercial realization depends on execution across clinical, reimbursement, and service delivery dimensions. Targeted therapies for plexiform neurofibromas require careful patient selection, monitoring for adverse events, and coordination among pediatric neurologists, oncologists, genetic counselors, and surgical specialists. The complexity of the care pathway influences how quickly new indications translate into prescribing behavior, particularly in regions where multidisciplinary tumor boards and specialized neurofibromatosis centers are limited.
Reimbursement frameworks are equally critical. Payers evaluate the cost-effectiveness of oral targeted inhibitors relative to the historical burden of repeated surgical procedures, surveillance imaging, and quality-of-life deterioration associated with tumor progression. As health technology assessment bodies gather real-world evidence and long-term outcome data, pricing negotiations, managed entry agreements, and formulary positioning will determine the pace at which targeted therapies achieve broad utilization. Market participants that invest early in robust health economics and outcomes research, patient support programs, and clinician education are better positioned to secure favorable access and sustain share.
The report delves into these operational realities with granular attention to regional access policies, pricing structures, and the clinical adoption curve. The precise data underpinning these assessments, including scenario-based market access modeling and detailed indication-level uptake estimates, are reserved for the complete study, where they can be directly applied to pricing strategy and launch planning.
Strategic Implications for Decision-Makers in 2026
Companies operating in or evaluating this market face a set of interconnected strategic questions. First, how should pipeline investments be prioritized given the dominance of MEK inhibition and the emergence of next-generation macrocyclic candidates? Second, where should commercialization resources be allocated to maximize return on launch investments across regions with varying regulatory maturity and reimbursement readiness? Third, what partnership structures, whether co-promotion, licensing, or combination development, offer the fastest route to expanded patient reach without overextending internal capability?
The answers depend on a clear view of market size evolution, segment-specific growth rates, competitive vulnerabilities, and the regulatory calendar. The forecast growth to 2,284.32 million USD by 2032 is not simply a top-line number; it reflects the cumulative effect of expanded pediatric and adult indications, deeper penetration in concentrated markets, and the gradual adoption of targeted therapy in regions where access has historically been constrained. Companies that align their strategy with these structural drivers, rather than relying on static market snapshots, will be better equipped to capture disproportionate value.
The study provides decision-makers with the framework to evaluate entering via asset acquisition, expanding through geographic rollout, or defending position through differentiated clinical data and service capabilities. Each path requires specific intelligence about competitor intentions, payer behavior, and the timing of label expansions. The detailed scenario analyses, competitive response simulations, and indication-level revenue projections available in the complete report translate high-level trends into actionable strategic choices.
Why Access the Full Study Now
Partial visibility into a market of this magnitude and complexity carries real risk. Aggregate figures and headline growth rates can mask important divergences between therapy types, demographic cohorts, and regional markets. Competitive concentration may appear stable on the surface while underlying regulatory approvals and pipeline developments are actively reshaping future share distribution. Without the full dataset, strategic plans risk being miscalibrated to the true shape of opportunity.
The complete worldwide plexiform neurofibromas treatment market research report offers a full suite of analytical tools: year-by-year market size and forecast tables from 2020 through 2032, detailed segmentation splits with absolute and relative values, regional and demographic growth drivers, competitive profiles that connect product strategy with regulatory milestones, and assessment of industry context factors such as Fast Track designations and reimbursement eligibility. Every projection is supported by documented assumptions, methodological transparency, and scenario flexibility that allow readers to test sensitivities relevant to their own portfolios.
Accessing the full study equips executives, strategy teams, and investment decision-makers with the precise intelligence needed to time market moves, prioritize territories, benchmark competitive threats, and build defensible growth plans for the 2026 to 2032 window. The detailed segmentation data, company-specific revenue estimates, and projection models that underpin the narrative presented here are available in the complete report, where they can be immediately integrated into strategic planning workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Plexiform Neurofibromas Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com