

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Customs Brokerage Hits $16.25B in 2025, Forecast 6.4% CAGR to 2032

Navigating the New Trade Frontier: Strategic Intelligence for the Customs Brokerage Services Market 2026–2032
The Strategic Imperative for 2026 Decision-Makers
Global trade flows are undergoing a structural transformation. Between 2020 and 2025, the worldwide customs brokerage services sector expanded from a revenue base of approximately 11,850 million USD to 16,250 million USD, reflecting an annualized growth trajectory that accelerated sharply in the post-pandemic recovery window. As we enter 2026, the market is projected to cross 17,238 million USD, and our forecast model maps a sustained compound annual growth rate of 6.4 percent through 2032, culminating in a market size exceeding 25,086 million USD. For executives navigating tariff realignments, regionalization of supply chains, and automated compliance mandates, these aggregate figures are only the starting point. What separates strategic leaders from reactive adopters is the ability to decode where growth concentrates, which service models capture margin, and how regulatory modernization reshapes operating economics. This intelligence brief introduces our newly published Worldwide Customs Brokerage Services Market study—a decision-grade reference designed to convert macroeconomic momentum into actionable competitive advantage.
Market Architecture: Scale, Segmentation Logic, and Concentration Signals
The customs brokerage landscape is no longer a commoditized clearance utility. It is a value-adding intermediary layer that sits at the intersection of logistics execution, regulatory interpretation, and digital trade infrastructure. Historical data from 2020 through 2025 demonstrates consistent expansion, but the composition of that expansion reveals strategic asymmetry. Revenue generation is distributed across geographical corridors, service capabilities, and end-user verticals, each carrying distinct risk-return profiles. Rather than treating the market as a monolithic pool, effective strategy requires understanding how distinct demand clusters behave under shifting trade policy, freight volatility, and technology adoption cycles.
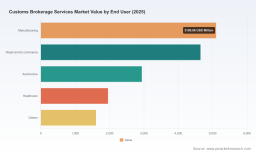
Geographically, the market spans mature trade hubs and high-velocity emerging corridors, with aggregate regional contributions reflecting both historical trade density and evolving nearshoring dynamics. In terms of service models, the largest revenue cluster continues to be anchored by transactional customs clearance, while advisory and compliance services and trade management software represent structurally higher-margin, stickier engagement models. End-user demand is diversified across manufacturing, retail and e-commerce, automotive, healthcare, and other sectors, each exposing brokers to different customs code complexities, valuation rules, and documentation cadences.
Importantly, the competitive field remains relatively fragmented at the top. Our concentration analysis indicates a top-three share of approximately 18.45 percent and a top-five share of roughly 27.3 percent. This fragmentation is strategically meaningful: it signals room for differentiation through specialization, technology-enabled service design, and regional depth, while also warning that scale alone does not guarantee pricing power. In a market where compliance intensity is rising and client expectations are shifting toward integrated visibility, share acquisition increasingly depends on capability stacking rather than volume alone.
Recent Dynamics: Regulatory Modernization, Compliance Economics, and Technology Adoption
The operating environment for customs brokerage firms has entered a phase of accelerated regulatory and technological recalibration. Two forces are particularly consequential for 2026 planning. First, regulatory modernization is reshaping both cost structures and process expectations. U.S. Customs and Border Protection has continued to advance the Customs Automated Payment and Entry system, with recent evaluations expanding refund scenarios and system capabilities for brokers and importers. Alongside this, the National Customs Brokers & Forwarders Association of America has highlighted new CBP procedures for updating Trade Account Owner information on existing ACE Portal accounts, signaling a compliance administration layer that requires proactive preparation. In parallel, CBP modernized customs broker regulations under 19 CFR 111 to optimize resource allocation and update compliance requirements, reinforcing a trajectory in which documentation accuracy, system readiness, and audit responsiveness are becoming core differentiators.
Second, compliance economics are becoming more visible and more demanding. Industry operating cost analysis indicates that customs brokerage firms allocate roughly 1,500 USD per month for regulatory compliance costs covering licensing and ongoing filings. On top of that, CBP set the 2026 annual customs broker permit user fee at 185.38 USD per national permit, with payment due by January 30, 2026. These are not marginal line items; they influence margin planning, service pricing, and the relative attractiveness of compliance automation. At the same time, brokers are increasingly adopting AI-powered compliance software and automated document verification to manage regulatory complexity, reduce manual exception handling, and improve throughput. The firms that treat technology as a compliance multiplier—not merely a back-office efficiency tool—are positioned to convert regulatory pressure into service differentiation.
Policy signals extend beyond the United States. The OECD Services Trade Restrictiveness Index for logistics customs brokerage services recorded notable policy changes in 2025, including increases in Ireland and the United States. For multinational operators and cross-border traders, this underscores the importance of monitoring regulatory restrictiveness as a variable that can alter route selection, entity structure, and service delivery models. In short, customs brokerage is no longer a static clearance function; it is a dynamic compliance-and-technology battlefield.
Competitive Landscape: Integrators, Specialists, and the Consolidation Undercurrent
The market is populated by a diverse set of incumbents, ranging from global logistics integrators to dedicated brokerage specialists. The strategic tension is clear: scale players leverage multimodal networks, global forwarding footprints, and platform ecosystems to bundle brokerage into broader supply chain offerings, while focused brokers compete on depth of customs expertise, client intimacy, and specialized trade compliance advisory. Both models can win, but they require different operating playbooks.
Worldwide International Freight Forwarding Services Market
Among the scale-oriented integrators, several global logistics and transportation enterprises embed customs brokerage within broader service portfolios. UPS Supply Chain Solutions delivers brokerage as part of integrated supply chain solutions, including entry filing, compliance management, and global clearance across air, ocean, and ground shipments. FedEx Trade Networks emphasizes efficient clearance, documentation, and regulatory compliance for international shipments through a dedicated brokerage arm. DHL Global Forwarding positions worldwide brokerage and clearance within its global forwarding network, leaning on compliance discipline, digital tools, and end-to-end trade management. Kuehne + Nagel, DB Schenker, GEODIS, DSV, and A.P. Moller – Maersk similarly integrate brokerage capabilities into freight forwarding, ocean logistics, and supply chain optimization portfolios, using network breadth to serve multinational clients with complex routing and multimodal requirements. C.H. Robinson Worldwide supports customs brokerage through its Navisphere platform, backed by more than 800 cross-border specialists and over 100 licensed customs brokers, illustrating how digital visibility and brokerage expertise can be paired at scale.
At the same time, dedicated brokerage providers continue to demonstrate the value of specialization. Expeditors International of Washington represents customs brokerage as a core offering, with licensed brokerage operations handling import/export clearance, compliance, and related trade services worldwide, forming a substantial share of its revenue base. Livingston International operates as a leading North American dedicated customs brokerage provider, serving tens of thousands of clients with brokerage, global trade management, compliance consulting, and freight solutions. GHY International specializes exclusively in customs brokerage and global trade services for North American companies engaged in international trade, drawing on more than a century of focused expertise. A.N. Deringer emphasizes compliance-oriented brokerage services, with active engagement in CBP system developments such as CAPE for refunds and entry processing.
The competitive logic here is not simply size versus specialization; it is integration depth versus jurisdictional fluency. Integrators gain advantage when clients want a single point of accountability across transport modes and trade lanes. Specialists gain advantage when clearance complexity, audit exposure, and compliance advisory requirements make domain expertise the primary purchasing criterion. Our study maps how these competing value propositions perform across regions and end-user segments, allowing leadership teams to benchmark their positioning against the operational models that are gaining traction in 2026.
Worldwide Customs Brokerage Services Market
Market Consolidation and M&A As a Strategic Signal
Recent deal activity reinforces the view that technology integration and capability expansion are reshaping industry structure. In April 2026, Zonos acquired Evolve Trade Services to embed customs brokerage capabilities directly into its cross-border operating system. This type of transaction reflects a broader pattern: platforms seeking to turn brokerage from an external dependency into an integrated control point within the buyer journey and fulfillment workflow. For both brokers and traders, the implication is significant. As clearance capabilities become embedded in e-commerce enablement, pricing, and landed-cost computation tools, the brokerage value proposition will increasingly be judged on speed, data continuity, and system interoperability—not just per-entry service quality.
This consolidation undercurrent matters for more than valuation narratives. It influences partner selection, outsourcing strategy, and the design of internal trade compliance functions. Organizations that rely on fragmented service providers may find themselves exposed to coordination friction, while those that consolidate trade services around platforms with integrated brokerage may gain visibility at the expense of flexibility. Understanding which model prevails in which segment is essential for procurement, operations, and trade compliance leaders.
What the Study Delivers: Practical Intelligence for Execution
The Worldwide Customs Brokerage Services Market study is structured to give strategy, operations, and trade compliance teams a usable map of the market rather than a static snapshot. The analysis is anchored in historical performance from 2020 through 2025 and extends a detailed forecast through 2032, enabling scenario planning around growth traction, service demand, and regional opportunity. Beyond aggregate sizing, the study breaks down the market across the dimensions that most influence strategic choice: regional corridors, service-type economics, and end-user demand profiles. This multi-axis view helps organizations identify where to invest, where to differentiate, and where to defend.
Equally important, the report situates market data within the operational realities that shape execution. It examines how regulatory modernization, compliance costs, permit economics, and system modernization affect brokerage operating models. It also traces technology adoption patterns, including the role of AI-enabled compliance software and automated document verification, as well as the increasing importance of digital trade management platforms. By connecting market sizing to operating conditions and competitive behavior, the study supports practical decisions on pricing, service design, partnership strategy, geographic coverage, and technology investment.
The competitive analysis component goes beyond company descriptions to interpret how major players are competing: through network integration, platform-enabled visibility, specialized compliance advisory, and targeted acquisitions. Combined with recent developments such as CAPE system updates, ACE Portal account administration changes, and the 2026 broker permit fee schedule, the study converts regulatory and industry events into decision-relevant context. For executives who need to align trade strategy with supply chain resilience, cost discipline, and compliance risk, that context is not optional; it is the basis for credible planning.
Why This Intelligence Matters for 2026 and Beyond
The 6.4 percent CAGR projected through 2032 indicates that customs brokerage services will remain an important and growing interface between global commerce and regulatory systems. But growth alone does not create advantage. Advantage is created by anticipating how service demand will shift across segments, how compliance automation will reshape cost structures, and how integration versus specialization will determine competitive outcomes in each geography and end-market. The firms and trading organizations that treat customs brokerage as a strategic capability—rather than a transactional necessity—will be better positioned to manage tariff exposure, clearance delays, audit risk, and cross-border uncertainty.
This study is designed to support that shift. It provides the macro framework, segment logic, competitive context, and regulatory signals required to build a forward-looking trade services strategy. To access the full segmentation detail, regional and service-type analysis, end-user breakdowns, and complete competitive profiles, we invite decision-makers to review the complete report at the source page. The full intelligence package is built to translate market momentum into concrete choices across service design, geographic focus, technology investment, and partnership strategy for the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Customs Brokerage Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com