

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2'-FL Market to Hit $812.74M by 2032 with 14.5% CAGR

Strategic Intelligence Brief: The Worldwide 2'-Fucosyllactose (2'-FL) Market Trajectory Through 2032
The global landscape for human milk oligosaccharides has entered a definitive phase of commercial maturation. As scientific consensus solidifies around the functional benefits of 2'-Fucosyllactose (2'-FL), the ingredient has transitioned from a niche innovation to a foundational component in early-life nutrition and functional wellness. Our latest comprehensive study, the Worldwide 2'-Fucosyllactose Market Report, provides the analytical rigor required to navigate this high-growth environment. This briefing outlines the strategic contours of the market, emphasizing the decision-making leverage available to stakeholders who align their portfolios with verified data rather than conjecture.
Macro Market Trajectory and Growth Velocity
The economic signal coming out of the 2'-FL sector is unambiguous. Following a period of infrastructure build-out and regulatory clearance, the market has demonstrated consistent value acceleration. Historical data captured in our analysis shows a clear upward curve from the base year through the current period, reflecting both volume uptake and premium pricing dynamics in advanced applications. Looking forward, the forecast period extending to 2032 projects a robust compound annual growth rate of 14.5 percent.
This trajectory is not merely incremental; it represents a structural expansion of the addressable market. By the end of the forecast horizon, the global revenue pool is expected to scale significantly beyond the 2025 baseline. For strategic planners, this implies that the window for establishing market presence is narrowing. The growth curve suggests that demand generation will increasingly be driven by reformulated standard-of-care products rather than novel introductions, shifting the competitive battlefield toward supply reliability, cost efficiency, and regulatory fluency. Companies that secure their positioning now will be better insulated against the margin compression that typically accompanies late-stage category expansion.
Worldwide 2'-Fucosyllactose (2'-FL) Market
Production Architectures and Segmentation Realities
The supply side of the 2'-FL market is defined by a divergence in production methodologies, each carrying distinct implications for cost structure, scalability, and purity profiles. The market is currently anchored by fermentation-based production, which has captured the majority of commercial volume due to its alignment with natural-origin labeling trends and its scalability through engineered microbial strains. Chemical synthesis, while representing a smaller share of the total output, maintains strategic relevance in specific high-purity or specialized research contexts.
Lactose serves as the primary substrate for most microbial fermentation processes, with engineered strains providing the necessary fucosyltransferase activity to drive conversion. This technical foundation means that supply chain resilience is increasingly tied to the stability of lactose sourcing and the proprietary efficiency of fermentation yields. The segmentation between production types is not just a technical distinction; it is a commercial differentiator that influences customer procurement criteria, particularly in regions where origin labeling and clean-label positioning carry significant price premiums.
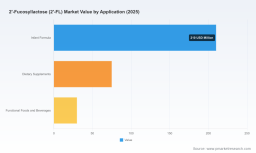
From an application perspective, the demand profile remains heavily weighted toward infant formula, which continues to absorb the vast majority of commercial volumes as manufacturers integrate 2'-FL into both standard and premium formulations. However, the diversification into dietary supplements and functional foods and beverages is gaining traction, signaling a broader utility narrative that extends beyond early-life nutrition. This expansion is critical for companies seeking to balance volume concentration risks. The ability to pivot supply toward supplement and functional food channels as infant formula margins evolve will be a key determinant of long-term portfolio resilience.
Geographical Demand and Regional Imperatives
The spatial distribution of 2'-FL demand reflects the varying maturity of regulatory frameworks and consumer awareness across key territories. North America and Europe collectively represent the largest demand centers, driven by established approval pathways, high procurement standards, and a consumer base that is already educated on the benefits of HMO supplementation. These mature markets demand consistent quality, comprehensive documentation, and supply continuity that only well-capitalized producers can reliably deliver.
Asia Pacific presents a different strategic calculus. While its current absolute volume is smaller than the Western centers, the region is characterized by rapid regulatory evolution and aggressive formulation activity in key national markets. The entry of new production capacities and the progressive clearance of additional strains are unlocking demand that was previously constrained by compliance uncertainty. Latin America and the Middle East and Africa, while representing smaller shares of the current global volume, are emerging as watchpoints for future growth. In these regions, the pace of adoption will likely be dictated by the speed of local regulatory harmonization and the degree to which regional manufacturers can access globally approved supply streams without prohibitive import barriers.
For multinational brands and ingredient suppliers, the geographical segmentation underscores the need for a tiered market entry strategy. Pouring equal resources into every territory is inefficient. The data suggests that prioritization should follow the gradient of regulatory readiness and formulation activity, with heavier investment in regions where approvals are fully active and consumer pull is demonstrable, while maintaining a surveillance posture in territories where approvals are in progress.
Competitive Landscape and the Consolidation Imperative
The 2'-FL market is not a level playing field. Market concentration metrics indicate a moderately consolidated environment, where a core group of global players controls a substantial portion of the supply and intellectual property landscape. This concentration is a function of the capital intensity required to build compliant fermentation facilities, the time lag associated with regulatory approvals across multiple jurisdictions, and the patent thickets that protect key production strains and formulation technologies.
Leading figures in this landscape include dsm-firmenich, which offers its GLYCARE 2FL line across multiple grades tailored for infant formula, baby and kids nutrition, and digestive health applications. Their portfolio includes specialized variants designed to meet specific allergen and religious compliance requirements, reflecting a market where granularity in product specifications translates directly into customer retention. Novonesis, formerly Chr. Hansen, brings extensive commercialization history and a broad patent estate to its MyOli 2'-FL offering, frequently positioning the ingredient in combination with probiotic solutions to deliver synergistic gut health narratives.
In Europe, the partnership between Wacker Chemie AG and BENEO exemplifies the strategic alignment of production and commercialization expertise. Wacker's microbial fermentation capabilities, combined with BENEO's distribution and formulation knowledge, enable a streamlined path to market for purified 2'-FL powder in infant nutrition applications. This type of alliance is indicative of a broader trend where production specialization and commercial reach are being deliberately decoupled and then re-linked through partnership structures to accelerate time-to-revenue.
In the Asia-Pacific sphere, Kyowa Hakko Bio, a Kirin Holdings company, has established a production footprint in Thailand and has been methodically securing regional approvals, including clearance from India's FSSAI as a food ingredient. Their approach highlights the importance of staging regulatory wins in high-population markets to build a foundation for volume growth. Meanwhile, IFF has leveraged its global regulatory affairs infrastructure to secure approvals in stringent markets including China, where its 2'-FL HMO has been cleared for use in infant formula, follow-up formula, and special medical purposes. FrieslandCampina Ingredients continues to advance its Aequival trademarked 2'-FL, with regulatory progress such as MARA approval in China for its production strain, signaling a concerted push into the high-value Chinese infant nutrition market.
The strategic implication of this landscape is clear. New entrants or smaller players cannot compete on breadth alone. They must either specialize in a high-margin niche, secure a distinctive production advantage, or align with a partnered commercialization channel. For buyers, the concentration of supply among proven, compliant manufacturers reduces procurement risk but also limits negotiating leverage. Diversifying supplier relationships while maintaining quality thresholds is therefore a prudent risk management practice.
Human Milk Oligosaccharides (HMO) Market
Regulatory Fluidity as a Strategic Variable
Regulation remains the single most powerful variable shaping the pace and geography of 2'-FL adoption. The period covered by our report has been marked by a series of approvals and clarifications that are progressively removing the compliance fog that previously slowed adoption. In China, the National Health Commission has approved additional production strains for 2'-fucosyllactose, with application scope and usage levels aligning with established announcements, effectively widening the pool of eligible suppliers and formulations.
In Europe and the United Kingdom, approvals have been granted for dsm-firmenich HMO ingredients, including mixtures containing 2'-FL, with effective dates spanning mid-2024. These approvals not only validate the safety profile of specific product grades but also set precedents that smooth the path for related formulations. The recent global launch of 2'-FL produced via precision fermentation in Europe, commercialized by BENEO following partnership with Wacker Chemie AG, demonstrates how regulatory clearance and commercial execution can converge to create new supply momentum in a key region.
In Asia, Kyowa Hakko Bio's receipt of FSSAI approval in India marks a milestone as the first HMO from the company cleared in the Indian market, opening a demographic base with significant growth potential. Additional regulatory progress, including dsm-firmenich's approval of GLYCARE 2FL in Indonesia for flavored liquid milk drinks for children above three years, illustrates how approvals are gradually expanding beyond infant formula into broader pediatric nutrition categories. The expanding regulatory perimeter is effectively enlarging the total addressable market, but it is doing so in a staggered, jurisdiction-specific manner that demands continuous regulatory intelligence rather than one-time due diligence.
Operationalizing the Report for 2026 Decision-Making
The value of this market study lies in its translation of macro trends into operational decisions. The report is structured to provide actionable intelligence across multiple business functions. It details the current and projected market size across the forecast period, giving finance and strategy teams a reliable basis for capacity planning, investment sizing, and revenue modeling. The segmentation analysis disaggregates demand by region, type, and application in a manner that allows product managers to identify where their offerings fit within the broader value chain and where white space or overexposure may exist.
Beyond quantitative baselines, the report captures the qualitative dynamics that numbers alone cannot convey. It maps the competitive profiles of core market participants, analyzing their headquarters, product architectures, patent positions, and recent developments to build a forward-looking view of competitive intent. Recent milestones, such as the European precision fermentation launch, Indian FSSAI approval, and Indonesia regulatory clearance, are contextualized to show how discrete events alter the supply-demand balance in specific territories.
The regulatory section aggregates the most consequential approval events and policy signals, providing a reference point for compliance teams and regulatory affairs managers. It distinguishes between approvals that expand the ingredient's use in mainstream food applications and those that are restricted to research-grade contexts, preventing costly misclassification of product intent. The raw material and production process context clarifies the technical dependencies that underpin supply reliability, enabling procurement leaders to assess vulnerabilities in the lactose supply chain and fermentation yield variability.
For M&A and business development teams, the concentration metrics and company profiles serve as a screening tool for potential partnerships, licensing opportunities, or acquisition targets. The report's architecture allows readers to filter information by relevance to their role, whether they are formulating a new product, negotiating a supply agreement, evaluating a market entry, or stress-testing a long-range financial model. The goal is to convert information into decision velocity, reducing the lag between signal detection and strategic action.
Strategic Horizons and Closing Perspective
As the 2'-FL market moves deeper into its growth curve, the differentiators that will separate winners from laggards are becoming increasingly clear. Regulatory fluency will remain paramount, as the ability to navigate and anticipate approval trajectories across jurisdictions will dictate which volumes can be commercialized and when. Production efficiency and strain intellectual property will determine who can compete on cost without sacrificing quality. Commercial execution, including formulation support, customer education, and supply chain resilience, will be the mechanism through which technical superiority is converted into market share.
The market data points to a future where 2'-FL is no longer a differentiating novelty but a standard expectation in premium early-life nutrition, with its footprint steadily expanding into adjacent wellness categories. Companies that treat this ingredient as a strategic platform rather than a commodity input will be best positioned to capture the value embedded in the forecast growth. The comprehensive intelligence contained in our Worldwide 2'-Fucosyllactose Market Report is designed to support that strategic posture, providing the depth, clarity, and forward-looking context needed to make informed decisions throughout the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Worldwide 2'-Fucosyllactose (2'-FL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com