

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lennox-Gastaut Syndrome Drug Market to Reach $2,248.33M by 2032 at 4.52% CAGR

Strategic Intelligence for the Lennox-Gastaut Syndrome Drug Market: Navigating the 2026 Landscape
The Lennox-Gastaut Syndrome (LGS) drug market represents a complex intersection of neurology, rare disease therapeutics, and evolving reimbursement frameworks. For pharmaceutical executives, investors, and healthcare strategists, understanding the trajectory of this specialized market is no longer optional. As we move through 2026, the convergence of novel treatment approvals, generic erosion, and real-world evidence generation demands a sophisticated approach to portfolio planning and market entry. PW Consulting’s latest Worldwide Lennox-Gastaut Syndrome Drug Market research delivers the analytical rigor required to make informed decisions in this high-stakes environment.
This report is designed as a strategic compass. It base-year analysis in 2025 provides a stabilized foundation, while the forecast window extending through 2032 maps the critical inflection points that will shape commercial outcomes. Rather than offering static snapshots, the research integrates historical performance from 2020 through 2025 with forward-looking modeling, enabling stakeholders to stress-test assumptions against multiple scenarios. The core objective is clear: equip decision-makers with actionable intelligence that transcends surface-level market sizing and dives into the structural forces driving revenue realization, competitive positioning, and access barriers.
Market Trajectory and the Imperative for Forward-Looking Analysis
The global landscape for LGS therapeutics has demonstrated consistent expansion over the past five years, with total market revenue advancing from a baseline in the mid-1,200 million USD range in 2020 to approximately 1,650 million USD by 2025. This growth reflects a compound annual growth rate of roughly 4.52 percent across the forecast horizon through 2032. While the headline trajectory signals stability, the underlying mechanics warrant deeper scrutiny. Revenue distribution is not uniform across therapeutic categories, distribution pathways, or geographic territories. Each segment carries distinct pricing dynamics, clinical adoption curves, and payer negotiation leverage that collectively determine which players capture sustainable market share.
Projecting forward, the market is anticipated to cross the 1,777 million USD threshold in 2026 and continues its upward march toward the 2,248 million USD range by the end of the forecast period. Such figures, however, are only as valuable as the segmentation logic that underpins them. Executive teams must understand how drug class preferences shift as newer branded agents compete with established generic portfolios, how distribution channel dominance evolves with pharmacy consolidation and digital health integration, and how regional healthcare infrastructure influences formulary placement and patient access. Our research deconstructs these layers without oversimplifying the trade-offs involved.
Infantile Spasms Therapeutics Market
Crucially, the research deliberately withholds granular percentage splits and precise regional or class-level dollar amounts within this preview. These operational details are embedded within the full dataset and analytical modules, accessible to subscribers who require the precision necessary for budget allocation, market entry modeling, and competitive response planning. The strategic narrative here establishes why the segmentation architecture matters, while the complete intelligence remains reserved for those ready to deploy it.
Competitive Architecture and the Evolving Treatment Paradigm
The LGS therapeutics space is defined by a concentrated yet active competitive field. Industry analysis indicates that the top three players account for approximately 52.4 percent of total market concentration, with the top five capturing roughly 68.9 percent. This level of consolidation suggests that while scale advantages exist, there remains meaningful room for specialized entrants and differentiated product strategies. The roster of key participants reflects the breadth of mechanisms now employed in adjunctive LGS management.
Jazz Pharmaceuticals continues to anchor its position through Epidiolex, a cannabidiol oral solution approved for patients one year and older. The product’s trajectory remains tied to controlled cultivation and extraction processes, alongside ongoing efforts to refine patient selection through genetic and phenotypic insights. UCB S.A. leverages Fintepla (fenfluramine), an oral solution targeting patients two years and older, building on its acquisition of Zogenix and expanding its real-world evidence footprint. Lundbeck A/S, through its historical development of Onfi (clobazam), operates in a space increasingly influenced by generic competition, necessitating brand differentiation and formulation innovation. Eisai Co., Ltd. maintains Banzel (rufinamide) as a targeted adjunctive option for patients one year and older, while GlaxoSmithKline (GSK) continues to market Lamictal (lamotrigine) for generalized seizures associated with LGS in patients two years and older.
Additional players structure the competitive mosaic in complementary ways. AbbVie Inc. provides valproate/valproic acid formulations widely utilized in seizure management, often extending into LGS care pathways. Janssen Pharmaceuticals, part of Johnson & Johnson, offers topiramate and related formulations as adjunctive therapies. Meda Pharmaceuticals, now integrated within Viatris, carries associations with Felbatol (felbamate), a third-line option reserved for specific clinical scenarios due to its safety profile. Aquestive Therapeutics and Cosette Pharmaceuticals have positioned themselves around the Sympazan (clobazam) oral film, with rights transitions and formulation delivery innovations shaping their commercial narratives.
This competitive density is further complicated by recent structural developments. The FDA has established specific approvals for eight anti-seizure medications used as adjunctive treatment for LGS-related seizures, including clonazepam, felbamate, lamotrigine, topiramate, rufinamide, clobazam, cannabidiol, and fenfluramine. This regulatory clarity has standardized certain treatment expectations but has also intensified scrutiny around cost differentials. Newer branded agents carry significantly higher price points compared to older generic alternatives such as topiramate, valproate, and lamotrigine, which often cost less than ten percent of the newer options. Such disparities directly influence payer policies, formulary tiering, and patient access negotiations.
Recent activity underscores how quickly the landscape can shift. In early 2026, Alembic Pharmaceuticals secured USFDA final approval for lamotrigine orally disintegrating tablets across various strengths, expanding generic availability for adjunctive LGS therapy. Around the same period, real-world evidence presented at the AES Annual Meeting highlighted persistence patterns and discontinuation drivers for fenfluramine in post-2022 LGS patients, providing clinicians and payers with nuanced data to inform treatment sequencing. Meanwhile, Jazz Pharmaceuticals and GW presented analyses at the AAN 2026 meeting focusing on genetic determinants within developmental and epileptic encephalopathies, aiming to sharpen the clinical positioning of cannabidiol in broader epilepsy contexts. These developments illustrate the interplay between regulatory milestones, clinical evidence generation, and competitive recalibration.
Segmentation Logic: Drug Classes, Distribution Pathways, and Strategic Positioning
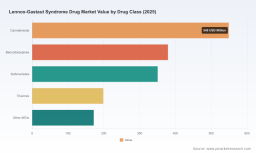
Effective market strategy for LGS therapeutics depends on understanding how revenue concentrates across drug classes and distribution channels. Cannabinoids, benzodiazepines, sulfonamides, triazines, and other anti-epileptic drug categories each command distinct clinical roles, prescribing habits, and pricing structures. The cannabidiol and fenfluramine segments, for instance, represent newer branded avenues that have reshaped expectations around seizure control, yet their premium positioning demands robust pharmacoeconomic justification. Conversely, benzodiazepine-based therapies and older anti-epileptic drugs benefit from established clinical familiarity and lower cost profiles, though they face mounting pressure from generic proliferation and evolving safety considerations, such as the boxed warnings associated with felbamate and its restricted third- or fourth-line status.
Distribution dynamics further complicate the commercial equation. Hospital pharmacies, retail pharmacies, and online pharmacies each serve different patient populations, care coordination models, and reimbursement pathways. Hospital-based dispensing often aligns with initial diagnosis, complex titration, and specialty oversight, while retail and online channels influence long-term adherence, refill convenience, and patient out-of-pocket exposure. The balance of channel share is not static; it responds to pharmacy network consolidation, mail-order adoption, specialty pharmacy program design, and payer-mandated utilization management. Readers of the full report will find detailed channel modeling that accounts for these variables without relying on blunt regional or application-level breakdowns that oversimplify localized realities. Instead, the analysis prioritizes structural drivers that remain relevant across markets and forecasts.
Reimbursement Pressures, Access Barriers, and the Strategic Response
The economics of LGS treatment cannot be divorced from reimbursement architecture. As noted in clinical and payer reviews, newer branded anti-seizure medications carry substantially higher costs relative to legacy generic options, creating friction in access pathways and prompting payers to implement strict prior authorization, step therapy, and quantity limits. These mechanisms directly affect prescription persistence, brand switching, and the real-world durability of treatment regimens. For manufacturers, the challenge is twofold: demonstrate differentiated clinical value that justifies premium pricing while navigating a reimbursement environment that increasingly demands head-to-head evidence, patient-reported outcomes, and health economics modeling.
The report integrates reimbursement dynamics into its forecasting models, examining how cost differentials influence formulary placement, patient assistance program utilization, and regional access variability. Felbamate’s safety profile further illustrates the delicate balance between therapeutic necessity and risk management, as its usage remains constrained to later-line scenarios with mandatory monitoring. For strategic planners, understanding these constraints is essential for forecasting realistic adoption curves and identifying adjacent opportunities, such as companion diagnostics, adherence-enabling formulations, and value-based contracting frameworks.
What the Full Report Delivers: Operational Depth for 2026 Decision-Making
Beyond the macro trends and competitive snapshots outlined here, the full Worldwide Lennox-Gastaut Syndrome Drug Market research provides a comprehensive operational toolkit. The study maps historical revenue performance across multiple years, establishes baseline assumptions for the 2026-2032 forecast period, and isolates the variables most sensitive to market shift. It examines how drug class preferences evolve as clinical evidence matures and generics enter the market, how distribution channels adapt to payer mandates and patient preference shifts, and how regional healthcare ecosystems influence prescribing norms and access timelines.
The report also addresses frequently asked strategic questions, including the regulatory milestones that have shaped LGS-specific approvals, the supply chain and scheduling considerations tied to specialized cannabinoid manufacturing, and the competitive implications of recent generic clearances. By synthesizing company profiles, recent clinical and regulatory developments, and structural market drivers, the research equips stakeholders to evaluate market entry timing, portfolio prioritization, partnership opportunities, and risk mitigation strategies with greater confidence.
Worldwide Lennox-Gastaut Syndrome Drug Market
Importantly, this preview is intentionally designed as a strategic trailer. Core segmentation figures, precise regional revenue distributions, and detailed channel-level breakdowns are preserved within the full dataset, accessible to teams that require the granularity necessary for financial modeling, Go-to-Market planning, and competitive response design. The objective is not to withhold insight but to ensure that the depth of analysis matches the complexity of the decisions at hand.
Conclusion: Positioning for the Long Game in a Specialized Neurology Market
The Lennox-Gastaut Syndrome drug market is not a volume-driven commodity space; it is a specialized therapeutic arena where clinical differentiation, payer negotiation, real-world evidence, and formulation innovation converge to determine long-term commercial viability. With a projected compound annual growth rate of approximately 4.52 percent and total market revenue advancing toward the 2,248 million USD range by 2032, the opportunity is meaningful, but so is the execution risk. Companies that rely on surface-level market sizing will miss the structural dynamics that dictate formulary wins, persistence outcomes, and sustainable pricing strategies.
PW Consulting’s in-depth research provides the analytical foundation needed to navigate that complexity. By blending historical performance analysis with forward-looking segmentation logic, competitive profiling, and reimbursement-aware modeling, the report enables 2026 decision-makers to move beyond speculation and into precision planning. For executives ready to align strategy with the realities of LGS therapeutics, the full research offers the intelligence required to act with clarity, confidence, and competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Lennox-Gastaut Syndrome Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com