

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Fuel Level Sensor Market Hits $950M in 2025, Projected CAGR 3.2% to 2032

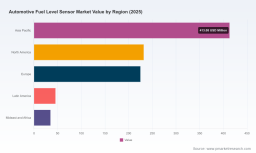
Strategic Intelligence Brief: Global Automotive Fuel Level Sensor Market Outlook 2026–2032
As automotive systems grow increasingly integrated and regulatory frameworks tighten around emission efficiency, the humble fuel level sensor has evolved from a passive indicator into a critical component of vehicle telemetry, safety compliance, and fuel management architecture. PW Consulting's latest Worldwide Automotive Fuel Level Sensor Market study delivers a comprehensive, decision-grade analysis of a market that is navigating structural shifts in powertrain preferences, supply chain volatility, and technological differentiation across passenger and commercial vehicle platforms. For executives, product planners, and investment committees operating in 2026, this report functions as a tactical compass: it maps revenue trajectories, competitive positioning, segment dynamics, and regulatory inflection points without obscuring the realities that will shape sourcing strategies, capacity allocation, and partnership models.
Why 2026 Marks a Strategic Inflection Point
The automotive sensor landscape is no longer defined by incremental component upgrades alone. Fuel level sensing now intersects with multi-fuel compatibility requirements, hybrid architecture optimization, advanced cockpit integration, and stricter safety benchmarks that demand precise, real-time fluid monitoring. The study anchors its forward-looking analysis in a historical baseline spanning 2020 through 2025 and extends a structured forecast window through 2032. This temporal framework is essential for 2026 decision-making because it captures the maturation of capacitive and ultrasonic sensing modalities, the recalibration of traditional resistive approaches, and the downstream impact of electrification trends on internal combustion engine (ICE) fuel system components. Readers gain a clear view of how revenue scales across the forecast horizon and where demand elasticity may diverge between regional manufacturing footprints, vehicle classes, and sensor technologies.
Market Sizing and Trajectory: What Leaders Need to See Now
At the macro level, the report quantifies a market that has demonstrated resilience through semiconductor supply disruptions, platform transitions, and shifting OEM sourcing patterns. Historical revenue data traces a market that rebounded from pandemic-era constraints, reached a recent baseline above nine hundred fifty million USD in 2025, and is positioned for measured expansion through the end of the decade. The forecast period reflects a compound annual growth rate that underscores steady, rather than speculative, growth—an important distinction for capacity planning and long-cycle procurement commitments. Rather than presenting raw figures as isolated statistics, the narrative connects size evolution to underlying drivers: plastic tank adoption, sensor accuracy requirements, safety regulation compliance, and the gradual but persistent demand pull from commercial vehicle fleets that continue to rely on ICE and hybrid architectures.
The study deliberately avoids fragmenting the narrative into exhaustive segment-by-segment disclosures within this introductory scope, preserving the analytical integrity of the full report. Instead, it frames the scale of the market in terms of strategic implications. Leaders evaluating supplier portfolios, regional footprint decisions, or technology roadmaps can use the top-line trajectory to calibrate investment pacing, anticipate volume shifts, and align engineering development with realistic demand curves. By embedding the sizing context within competitive and regulatory analysis, the report ensures that executives do not misinterpret growth signals or underestimate structural headwinds tied to electrification adoption and component consolidation.
Revenue Baseline and Forecast Horizon
The historical series provides a defensible reference point for validating internal forecasts, stress-testing assumptions, and identifying anomalies in regional or application-level performance. The forward projection extends through 2032, giving stakeholders a multi-year planning window that aligns with typical automotive development cycles and platform refresh timelines. This structure supports scenario planning around volume sensitivity, supplier nomination windows, and the timing of next-generation sensor introductions. For organizations that must justify capital deployment or reallocate engineering resources in 2026, the report offers a credible growth narrative that is neither overly optimistic nor prematurely dismissive of ICE-related component demand.
Competitive Landscape: Structure, Concentration, and Motion
The study maps a market characterized by meaningful concentration and active competitive repositioning. A relatively compact group of established multinational suppliers accounts for a substantial share of revenue, reflecting the industry's reliance on qualified OEM relationships, long validation cycles, and integrated module architectures. This concentration matters for 2026 because it shapes pricing leverage, qualification bottlenecks, and the ability of smaller or specialized players to break into high-value programs. At the same time, recent announcements reveal that incumbents are not resting on legacy positions; they are expanding sensor portfolios, pursuing platform nominations, and formalizing joint development agreements that tie sensor performance directly to next-generation vehicle programs.
Worldwide Automotive Fuel Level Sensor Market
Incumbents and Strategic Positioning
Robert Bosch GmbH continues to anchor its relevance through capacitive, float-based, and ultrasonic fuel level sensors embedded in OEM fuel tank modules for both passenger and commercial vehicles. Continental AG reinforces its global footprint by supplying fuel sender units and level sensors with integrated temperature sensing, supporting major OEMs across multiple platforms. Denso Corporation maintains strong ties with Asian automakers through reed switch and capacitive solutions tailored for ICE and hybrid applications, while BorgWarner Inc. leverages its legacy Delphi Technologies capabilities to address multi-fuel compatibility requirements in North American and European markets. Visteon Corporation extends sensor functionality into integrated cockpit environments, embedding fuel level detection within smart display clusters for key global customers. Sensata Technologies is broadening its fluid property sensor portfolio, including fuel level detection, with explicit relevance to heavy-duty trucks and passenger vehicles. CTS Corporation specializes in electronic fuel level sensors using variable resistor technology for OEMs such as GM and Cummins, underscoring the continued role of resistive approaches in specific commercial and OEM contexts. TE Connectivity provides ruggedized float and non-contact options suitable for off-road and marine-adapted automotive applications, while Gill Sensors & Controls emphasizes non-intrusive ultrasonic and capacitive measurement for motorsport and commercial vehicles. Methode Electronics rounds out the competitive field with Hall effect-based sensors designed for electric fuel pump modules in light-duty trucks.
This competitive set illustrates a market where technology differentiation is not purely about sensing method; it is equally about integration depth, platform alignment, and the ability to meet multi-fuel, temperature, and safety requirements within tight packaging constraints. For procurement teams and engineering leaders, understanding which players are extending into adjacent sensor functions, which are winning platform nominations, and which are validating next-generation designs with OEMs can materially affect sourcing strategy and risk exposure.
Recent Developments That Reshape 2026 Planning
Several recent events demonstrate how competitive momentum is being created in near-real time. Sensata Technologies launched next-generation Fluid Property Sensors that incorporate fuel level detection for automotive applications, signaling a broader move toward multifunctional sensing rather than single-parameter indicators. Continental AG was nominated by Volkswagen Group for next-generation fuel sender units in MQB platform vehicles, a development that reinforces the importance of platform-level supplier selection and the long lead time implications of such nominations. CTS Corporation completed validation testing for electronic fuel level sensors on Cummins engines, highlighting the commercial vehicle validation pathway and the continued relevance of electronic sensor architectures in heavy-duty applications. Denso Corporation signed a joint development agreement with Toyota for advanced capacitive fuel sensors in hybrid models, an indication that sensor innovation remains tightly coupled with hybrid platform evolution rather than being displaced by electrification.
For executives assessing competitive risk, these developments are not isolated announcements; they are indicators of where qualification momentum, technology roadmaps, and OEM trust are converging. The report synthesizes these moves into a structured competitive assessment that helps readers identify which suppliers are expanding their addressable scope, which are locking in platform positions, and where potential supply gaps or qualification bottlenecks may emerge in the 2026 to 2032 window.
Segmentation and Technology Dynamics: The Analytical Core
One of the report's central strengths is its treatment of segmentation as an operational decision tool rather than a static taxonomy. The market is analyzed across geography, sensor type, and vehicle application, but the narrative frames these dimensions in terms of engineering trade-offs, sourcing implications, and regulatory responses. Technology differentiation is particularly important in this market because sensor choice affects accuracy, packaging, fuel compatibility, and compliance with emerging emission and safety requirements.
The study addresses the ongoing prominence of capacitive sensors, whose accuracy in plastic fuel tanks has made them a preferred choice in many modern platforms. At the same time, it examines ultrasonic alternatives and their calibration challenges, especially in foaming fuel environments, where measurement stability can become a design constraint. Resistive sensors remain relevant in specific OEM and commercial applications, particularly where variable resistor technology aligns with established validation pathways and cost structures. By presenting these technology dynamics within the context of real application demands, the report enables product teams to evaluate not just which sensor type is gaining share, but why, under what conditions, and with what implications for reliability, certification, and lifecycle support.
Application-Level Demand Patterns
The application dimension is explored through the lens of differing vehicle requirements rather than isolated volume counts. Passenger vehicles and commercial vehicles impose distinct performance expectations, durability standards, and integration priorities. Commercial vehicle fleets, in particular, continue to create sustained demand for fuel level monitoring in heavy-duty and light-duty contexts, often with additional requirements for multi-fuel compatibility, harsh-environment durability, and integration with telematics or fleet management systems. Passenger vehicle demand, meanwhile, is shaped by platform consolidation, cockpit integration trends, and the evolving balance between ICE, hybrid, and increasingly electrified architectures. The report connects these application-level considerations to sourcing logic and product planning, giving leaders a practical framework for interpreting demand shifts without reducing them to simplistic volume comparisons.
Regulatory, Supply, and Macro Forces Reshaping the Market
Fuel level sensing does not operate in a vacuum. The study integrates regulatory and supply-side forces that alter both design priorities and demand durability. Euro 7 emission standards require precise fuel level monitoring to optimize combustion efficiency in ICE vehicles beginning in 2025, reinforcing the sensor's role in emissions compliance rather than mere driver indication. Alongside this, safety regulations such as FMVSS 301 mandate fuel system integrity that includes level sensors capable of withstanding rear impact without leakage, adding a structural compliance dimension to sensor selection and packaging.
Supply chain volatility remains a relevant planning factor. Semiconductor shortages previously drove significant increases in lead times for automotive sensor ICs used in fuel level detection, and while conditions have evolved, the episode underscored the dependency of sensor programs on semiconductor availability and the importance of qualification lead times. This history informs the report's discussion of sourcing resilience, buffer strategies, and the risk of over-concentration in component supply paths. On the macro side, the trajectory of global EV adoption is projected to reduce ICE fuel system component demand on an annual basis through 2030. Rather than treating this as a linear decline narrative, the report examines how hybrid platforms, commercial vehicle ICE persistence, and multi-fuel transition requirements can sustain pockets of demand even as the broader powertrain mix shifts. This nuanced treatment is essential for avoiding strategic overreaction or premature disinvestment in sensor capabilities that remain relevant across multiple vehicle programs.
What the Report Delivers for 2026 Decision-Makers
Beyond market sizing and competitive mapping, the study is designed as an operational reference. It provides actionable frameworks for interpreting qualification cycles, supplier nomination patterns, technology trade-offs, and regulatory-driven design constraints. Readers gain a structured view of how sensor selection intersects with platform architecture, emission compliance, safety mandates, and fleet durability expectations. The report also supports scenario-based thinking: leaders can assess how changes in OEM platform strategy, regional manufacturing location, or fuel system architecture might alter demand patterns and supplier relevance over the forecast period.
For product planners, the analysis clarifies where capacitive, ultrasonic, and resistive approaches are likely to remain advantageous and where integration requirements may favor multifunctional or cockpit-linked sensor solutions. For procurement and supply chain leaders, it highlights the implications of market concentration, qualification lead times, and semiconductor dependency on sourcing resilience. For competitive intelligence teams, it provides a foundation for tracking supplier momentum through platform nominations, validation milestones, and joint development activity rather than relying on headline product launches alone.
How to Use This Study in Practice
The report is built to support decisions that must be made with incomplete visibility. It gives executives a defensible basis for capacity commitments, supplier evaluations, technology investment priorities, and regional sourcing reviews. It also helps organizations distinguish between cyclical fluctuations and structural changes in demand behavior. By connecting historical performance to forecast dynamics and competitive movement, the study enables more disciplined strategic planning in a market where small shifts in platform selection or regulation can have outsized effects on component requirements.
Conclusion: Strategic Clarity for a Market in Transition
The Worldwide Automotive Fuel Level Sensor Market study from PW Consulting offers more than a top-line growth narrative. It delivers a structured, regulation-aware, and competition-sensitive examination of a component market that remains strategically important even as powertrain portfolios evolve. For 2026 decision-makers, the report functions as both a diagnostic tool and a planning resource: it identifies where demand is anchored, where technology and regulatory forces are reshaping product requirements, and where competitive momentum is being established through platform nominations, validation progress, and joint development commitments.
Worldwide Automotive Camera Sensor Market
To access the full segmentation analysis, detailed regional and application trajectories, supplier profiles, and forecast scenarios, readers are encouraged to explore the complete report on the PW Consulting web portal. The complete intelligence package provides the granular data and proprietary breakdowns necessary to translate this strategic overview into precise sourcing, engineering, and investment decisions across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Fuel Level Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com