

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cutaneous Mastocytosis Drugs Market to Reach $170.57M by 2032, 5.15% CAGR

Worldwide Medications for Cutaneous Mastocytosis Market: Strategic Intelligence for 2026 Decision-Making
The global landscape for medications targeting cutaneous mastocytosis is undergoing a structural transformation. As a rare disease segment with complex symptomatic and targeted therapeutic requirements, the market demands precise intelligence for stakeholders navigating clinical, regulatory, and commercial uncertainties. PW Consulting's latest Worldwide Medications for Cutaneous Mastocytosis Market research provides a comprehensive 2026-ready analytical framework, synthesizing historical performance, forward-looking forecasts, and competitive dynamics into actionable strategic guidance.
Built on a robust historical dataset spanning 2020 through 2025 and extending forecast projections to 2032, this study equips pharmaceutical executives, investors, and healthcare strategists with the evidence base required to allocate capital, shape pipeline priorities, and respond to shifting treatment paradigms. The following analysis outlines the strategic value embedded in this research and demonstrates why comprehensive market intelligence is indispensable for 2026 enterprise decision-making.
Executive Market Overview: Trajectory and Scale
The worldwide medications for cutaneous mastocytosis market has demonstrated consistent expansion over the past half-decade. Valued at approximately 89.24 million USD in 2020, the market advanced to 120.0 million USD by 2025, reflecting a compound annual growth rate of 5.15 percent over the historical evaluation window. This growth trajectory is projected to continue through the 2026-2032 forecast period, with the market expected to reach 170.57 million USD by 2032.
The steady upward curve is underpinned by multiple converging factors: widening diagnostic capabilities for mast cell disorders, the introduction of targeted KIT inhibitors that address cutaneous manifestations alongside systemic disease, and the maturation of reimbursement pathways for symptomatic management agents. Notably, the transition from purely supportive care to targeted molecular interventions has expanded the addressable patient population and introduced new pricing and access dynamics that warrant careful strategic consideration.
Our forecast model incorporates base-year calibration from 2025 actuals and extends through 2032, offering decision-makers a multi-horizon view that balances near-term commercial planning with long-term portfolio strategy. All figures are denominated in USD millions, providing a standardized metric for cross-market comparison and investment appraisal.
Strategic Segments: Therapeutic Class, Treatment Setting, and Regional Distribution
Understanding how revenue flows across therapeutic categories, care environments, and geographies is essential for identifying growth vectors and competitive white space. The research dissects the market along three primary segmentation dimensions, each carrying distinct implications for product positioning and market access strategy.
Therapeutic Class Composition
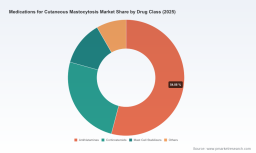
The market is anchored by antihistamines, which represent the largest share of revenue as the longstanding standard of care for mediator-related symptoms in cutaneous mastocytosis. Corticosteroids and mast cell stabilizers form substantial secondary pillars, addressing inflammatory control and symptom prophylaxis respectively. An others category captures emerging and adjunctive agents, including targeted kinase inhibitors that are progressively gaining recognition for their role in managing cutaneous involvement in systemic disease. The interplay between established symptomatic therapies and newer targeted options creates a dynamic competitive environment where treatment algorithms are continuously refined.
Worldwide Schnitzler Syndrome Treatment Market
Treatment Setting Dynamics
Revenue distribution across care settings reveals where therapeutic deployment is concentrated. Specialty clinics represent a prominent channel, reflecting the specialized diagnostic and management expertise required for mast cell disorders. Hospitals constitute a significant portion of the market, driven by the management of more complex or advanced presentations. Homecare settings capture a meaningful share, consistent with the chronic, symptom-driven nature of cutaneous mastocytosis and the reliance on oral and topical maintenance therapies. The balance among these settings influences distribution strategies, pricing negotiations, and patient support program design.
Regional Market Architecture
Geographically, the market exhibits pronounced variation in maturity, access conditions, and growth potential. North America represents the largest regional revenue contributor, supported by established diagnostic infrastructure, robust reimbursement frameworks, and the early adoption of targeted therapies. Europe follows as a substantial market, shaped by diverse national health technology assessment processes and guideline-driven treatment approaches. The Asia Pacific region reflects emerging opportunity, where improving disease awareness and expanding healthcare capacity are gradually broadening treatment access. The rest of world segment encompasses additional heterogeneous markets with varying levels of development. The research provides granular regional analysis designed to inform market entry prioritization, partnership targeting, and localization strategies, though specific regional proportions and dollar allocations are detailed in the full report.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is defined by a mix of innovative specialty pharmaceutical companies and established generic manufacturers, each pursuing distinct value propositions within the cutaneous mastocytosis treatment ecosystem.
Blueprint Medicines Corporation, now integrated within Sanofi, has established a leadership position through the development and commercialization of AYVAKIT (avapritinib), a selective KIT D816V inhibitor approved for indolent systemic mastocytosis and advanced systemic mastocytosis. Its demonstrated ability to improve cutaneous involvement in mastocytosis patients positions it as a differentiated targeted therapy that bridges systemic and cutaneous disease management. The company's continued advancement in mast cell disorders, leveraging expertise from avapritinib development, underscores a strategic commitment to this rare disease space.
Novartis AG markets Rydapt (midostaurin), a multikinase inhibitor approved for advanced systemic mastocytosis, while also providing symptomatic treatments including H1 and H2 antihistamines and mast cell stabilizers used in cutaneous mastocytosis management. This dual portfolio approach—combining targeted therapy for advanced disease with supportive symptomatic agents—reflects a comprehensive strategy to address the full spectrum of patient needs.
Viatris Inc. supplies generic cromolyn sodium oral solution, a mast cell stabilizer indicated for symptom management in mastocytosis, including cutaneous forms. By ensuring reliable access to an established generic therapy, Viatris plays a critical role in the broader treatment infrastructure, particularly where cost containment and long-term maintenance therapy are paramount considerations.
Teva Pharmaceutical Industries Ltd. provides generic formulations of antihistamines, including H1 and H2 blockers, alongside other symptomatic medications commonly used for mediator-related symptoms in cutaneous mastocytosis. Teva's offerings reinforce the foundational role of antihistamine therapy in daily symptom control and contribute to a competitive generic landscape that shapes pricing dynamics and patient access.
Market Dynamics and Recent Industry Developments
Regulatory Milestones and Targeted Therapy Adoption
A pivotal regulatory development shaping the market is the FDA approval of avapritinib (AYVAKIT) in May 2023 for adults with indolent systemic mastocytosis, marking the first targeted therapy approved for this indication with demonstrated improvement in cutaneous symptoms. This milestone has catalyzed renewed clinical and commercial interest in targeted approaches that address both systemic and cutaneous manifestations. Parallel regulatory approvals, including midostaurin for advanced systemic mastocytosis across FDA and EMA pathways, further expand the targeted therapy landscape and influence treatment sequencing decisions.
Guideline Evolution and Standard of Care Refinement
Clinical guidance continues to evolve, reinforcing the integration of both symptomatic and targeted interventions. The publication of French guidelines for the management of nonadvanced mastocytosis in adults, covering cutaneous mastocytosis and indolent systemic mastocytosis with symptom-directed therapies, exemplifies the growing emphasis on structured, evidence-based management pathways. Such guideline developments influence prescribing behavior, formulary inclusion, and payer expectations across multiple markets.
Reimbursement Pathways and Access Considerations
Symptomatic treatments for cutaneous mastocytosis, including H1 and H2 antihistamines and cromolyn sodium, benefit from established reimbursement pathways in major markets for mediator-release symptoms. This established access infrastructure supports consistent utilization of foundational therapies while creating a baseline against which newer targeted agents must demonstrate differentiated value. The interplay between mature reimbursement routes for symptomatic care and evolving coverage determinations for targeted therapies represents a critical dynamic for market access strategists.
Supply Chain and Operational Realities
Operational challenges persist, particularly concerning supply chain constraints for specialized pharmaceutical ingredients and active compounds. These constraints create operational complexities for manufacturers of mastocytosis treatments and can influence product availability, cost structures, and lead times. Forward-looking supply chain resilience planning is therefore an integral component of commercial strategy in this segment.
Report Scope and Operational Contents
This research is designed as a practical decision-support tool, offering detailed analysis across multiple dimensions that directly inform corporate strategy, investment thesis development, and competitive positioning.
-
Comprehensive market sizing and forecasting from 2020 through 2032, with base-year calibration and scenario-aware projections that enable robust planning under varying demand and access conditions.
-
In-depth segmentation analysis by drug class, treatment setting, and region, illuminating revenue concentration, growth rates, and shifting utilization patterns that guide resource allocation and portfolio optimization.
-
Competitive profiling of key market participants, including corporate positioning, product portfolios, recent corporate updates, and strategic maneuvers that shape competitive intensity and market share dynamics.
-
Regulatory and clinical landscape mapping, capturing FDA and EMA approval milestones, guideline releases, and clinical discussion trends that influence treatment algorithms and adoption pathways.
-
Reimbursement and access environment assessment, detailing established pathways for symptomatic therapies and the evolving coverage landscape for targeted agents, with implications for pricing strategy and market penetration.
Worldwide Medications for Cutaneous Mastocytosis Market -
Supply chain and operational risk analysis, identifying constraints related to specialized ingredients and active compounds and their potential impact on manufacturing, availability, and cost management.
-
Strategic recommendations and scenario frameworks that translate analytical findings into actionable guidance for market entry, partnership evaluation, pipeline prioritization, and competitive response.
Strategic Imperatives for 2026 Decision-Making
As the market transitions further into a hybrid treatment paradigm—where symptomatic management coexists with increasingly targeted interventions—enterprise leaders face a set of pressing strategic questions. Which therapeutic categories offer the most resilient revenue profiles? How will targeted therapies reshape prescribing hierarchies and payer expectations? Where do regional access conditions create the most favorable conditions for market expansion or partnership? How should organizations anticipate and mitigate supply chain vulnerabilities?
Addressing these questions requires more than high-level trend observation. It demands granular segment analysis, competitive benchmarking, regulatory horizon scanning, and scenario-based forecasting. The research delivers this depth, enabling stakeholders to move from reactive monitoring to proactive strategy formulation.
For pharmaceutical companies evaluating portfolio enhancements, the analysis clarifies where targeted therapies are gaining traction and how symptomatic agents continue to anchor routine care. For investors, the forecast trajectory and concentration metrics provide a structured basis for assessing market maturity and growth durability. For market access and pricing teams, the reimbursement environment mapping offers context for designing value propositions that align with existing coverage frameworks while positioning for emerging targeted therapy benchmarks.
Market Concentration and Competitive Structure
The competitive architecture of the market reflects a moderately concentrated structure, with the top three firms accounting for approximately 35.5 percent of market revenue and the top five firms representing roughly 48.2 percent. This distribution indicates that while leading innovators and established generic suppliers command meaningful share, substantial opportunity remains for additional participants, particularly in segments where differentiation, access strategy, or regional presence can drive competitive advantage. Understanding this concentration profile is vital for assessing barriers to entry, partnership potential, and the likely intensity of competitive responses to new product introductions or market expansion initiatives.
Conclusion: Why Comprehensive Intelligence Matters Now
The worldwide medications for cutaneous mastocytosis market is at an inflection point where clinical innovation, regulatory progress, and evolving care standards are converging to reshape treatment pathways and commercial opportunities. For organizations operating in or entering this space, the margin between informed strategy and speculative positioning is widening. Comprehensive, forward-looking market intelligence is no longer a supplementary asset—it is a foundational input for capital allocation, product strategy, and competitive execution.
PW Consulting's Worldwide Medications for Cutaneous Mastocytosis Market research offers the analytical rigor, segment granularity, and strategic context required to navigate this complex environment with confidence. The full report extends well beyond the macro trajectory and competitive overview presented here, delivering detailed segmentation data, regional breakouts, company-level profiling, and scenario-based guidance that empower precise, evidence-based decision-making.
To access the complete dataset, detailed segmentation splits, and the full competitive and regulatory analysis, we invite you to explore the source webpage and secure the comprehensive intelligence your organization needs to lead in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Medications for Cutaneous Mastocytosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com