

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Luxury Car Coachbuilding Market to Hit $2.12B by 2032, 9.15% CAGR

Navigating the Apex: Strategic Intelligence for the Global Luxury Car Coachbuilding Market in 2026
In the rarefied air of ultra-luxury mobility, the distance between a bespoke commission and a defunct investment is measured in microns of craftsmanship and milliseconds of strategic foresight. As we enter 2026, the worldwide luxury car coachbuilding market is undergoing a structural transformation that defies the traditional volatility of bespoke manufacturing. Our latest research initiative, the Worldwide Luxury Car Coachbuilding Market study, delivers a definitive financial and operational map for executive decision-making over the next seven-year horizon. This article outlines the foundational intelligence embedded in the report and demonstrates why precise, granular intelligence is now a prerequisite for capital allocation, portfolio management, and long-term client relationship strategy.
A Measurable Trajectory: From Established Benchmarks to a High-Growth Forecast Window
The luxury coachbuilding sector has transitioned from a niche artisanal pursuit into a quantitatively robust industrial segment. Drawing on historical data spanning 2020 through 2025 and projecting forward through 2032, our baseline analysis establishes clear momentum. The market has demonstrated consistent upward pressure across the base period, culminating in a 2025 baseline that signals sustained demand velocity. Looking ahead, the forecast window of 2026 through 2032 projects compound annual growth that positions the segment as one of the highest-yielding niches within the broader automotive aftermarket and bespoke mobility ecosystem.
What sets this trajectory apart is not merely the headline growth rate, but the underlying composition of that expansion. Revenue generation is increasingly anchored by capital-intensive one-off commissions, while simultaneously being reinforced by recurring customization cycles and performance retrofitting programs. The market evolution reflects a dual-engine dynamic: legacy coachbuilders leveraging heritage to command premium pricing, and newer specialty firms scaling limited-production bodywork that bridges classic iconography with modern propulsion architectures. For enterprise leaders, the margin implications of this bifurcation are significant, and the full breakdown of revenue weighting by segment type, regional concentration, and propulsion platform is reserved for the complete dataset within the published report.
Sector Architecture and Structural Dynamics
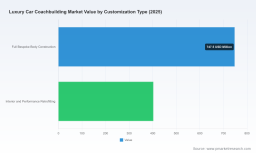
The contemporary coachbuilding marketplace operates across highly specialized production typologies. Demand is primarily bifurcated between full bespoke body construction and extensive interior and performance retrofitting programs. The former represents the apex of capital deployment, where hull design, panel fabrication, and final assembly occur under proprietary workflows that often span multi-year client engagements. The latter captures a broader addressable base of affluent owners seeking to elevate existing luxury and supercar platforms through structural, acoustic, and performance modifications. Both streams are subject to distinct supply chain constraints, lead-time economics, and regulatory considerations that directly influence margin structure and operational scalability.
Propulsion architecture is equally decisive in shaping commissioning behavior. Traditional internal combustion platforms continue to anchor a substantial portion of bespoke body projects, particularly within heritage segments where engineering compatibility, aesthetic continuity, and collector sentiment remain paramount. At the same time, electric and hybrid propulsion systems are gaining traction as feasibility improves and client preferences shift toward sustainable craftsmanship. This transition is not purely technological; it is fundamentally reshaping sourcing logic, weight-distribution engineering, and thermal management strategies within coachbuilt envelopes. The complete revenue attribution across propulsion categories and customization types is available in the final report, but the strategic takeaway is clear: propulsion choices now dictate material selection, production sequencing, and long-term residual valuation.
Material Economics and Design Freedom
Material selection has emerged as a core strategic variable rather than a simple manufacturing consideration. Aluminum continues to occupy a central role in luxury coachbuilding due to its workability for hand-formed panels and its alignment with traditional British and Italian fabrication philosophies. Its dominant position in the material mix reflects decades of process maturity, tooling familiarity, and client acceptance. Yet the material landscape is being actively redrawn by composite technologies. Carbon fiber has become the fastest-growing material segment, driven by its strength-to-weight advantages, structural versatility, and the increasing ability to produce highly individualized geometries that would be cost-prohibitive with conventional metal forming.
A critical enabler of this shift has been the sustained decline in aerospace-grade carbon fiber costs over recent years, which has meaningfully improved economic viability for limited-series automotive applications. At the same time, tightening global emission standards and rising consumer expectations around sustainable luxury are reinforcing the adoption of lightweight composites and aluminum in coachbuilt bodies. These factors jointly influence production cost, platform efficiency, and certification complexity. Industry participants that fail to integrate material strategy into their commercial planning risk margin compression and reduced competitive flexibility, particularly as suppliers recalibrate capacity and pricing in response to cross-sector demand.
Competitive Landscape: Heritage, Hypercraft, and Aggressive Transformation
The competitive environment is defined by a concentrated set of established players, a rotating cast of specialist ateliers, and a handful of performance-oriented transformation firms. Market concentration underscores the structural advantages of incumbency, brand equity, and deep client relationships, while also highlighting the room for differentiated positioning among firms that compete on speed, design language, or technical specialization. The top-tier players exert meaningful influence over pricing norms, lead-time expectations, and the overall prestige architecture of the segment.
Rolls-Royce Motor Cars operates a dedicated Coachbuild division producing one-off and highly bespoke vehicles, most recently formalizing its approach with a new Coachbuild Collection launched in 2026. This program unites limited-production coachbuilt models with multi-year client experiences, with the inaugural vehicle, Project Nightingale, developed in close collaboration with select clients and revealed as a limited-run coachbuilt EV. Bentley Mulliner continues to extend traditional craftsmanship through extensive customization and coachbuilt models, while Aston Martin Lagonda supports bespoke commissions through its Q Division on luxury GT and supercar platforms. Ferrari N.V. further diversifies the landscape through its Special Projects division, which handles unique bodywork commissions on Ferrari chassis.
Italian design and engineering houses remain foundational to the market's creative and technical identity. Pininfarina S.p.A. provides design, engineering, and limited-series coachbuilt bodies, including collaborations and the Automobili Pininfarina Battista hypercar line, while Carrozzeria Touring Superleggera specializes in lightweight aluminum and composite bodies for modern re-body projects and limited production vehicles. Zagato Milano is recognized for distinctive double-bubble coachbuilt designs and limited-series collaborations, including recent twin-tail concepts, and Italdesign Giugiaro continues to deliver coachbuilding and prototype development services for luxury vehicles. Ares Design Modena focuses on complete coachbuilt re-body projects on modern supercar platforms, and Radford Motor Company has revived its British coachbuilding heritage to target limited-edition supercars with bespoke bodywork. Niels van Roij Design operates as a bespoke studio creating unique one-off bodies and homages on classic and modern bases.
On the performance and transformation side, the competitive dynamic broadens further. Mansory Design & Holding GmbH and Brabus GmbH compete in aggressive carbon fiber body kits and full conversions for luxury and supercars, while Pagani Automobili and Koenigsegg Automotive AB bring in-house coachbuilding expertise and proprietary structural technologies to hypercar production. Collectively, this ecosystem reflects a spectrum of value propositions, from heritage-led one-off commissions to technically aggressive body transformations. The complete competitive assessment, including positioning analysis and strategic interdependencies, is mapped in full within the published research.
Luxury Yacht Market
Institutional Developments Shaping 2026 Decision-Making
Recent program announcements and product developments are already recalibrating how leading firms structure client engagement and production pipelines. The launch of Rolls-Royce's Coachbuild Collection in early 2026, paired with the unveiling of Project Nightingale as a limited-run coachbuilt EV, illustrates a shift toward curated, long-duration client relationships rather than transactional commissions. This model has direct implications for forecasting accuracy, capacity reservation, and cross-functional coordination between design, engineering, and client experience teams.
At the same time, broader regulatory and sustainability pressures are influencing procurement and engineering decisions across the segment. Increasing global emission standards and demand for sustainable luxury are encouraging greater use of lightweight composites and aluminum to improve vehicle efficiency. These dynamics create both opportunities and constraints: firms that integrate compliance, material performance, and design differentiation into a unified strategy are better positioned to sustain premium pricing, while those that treat regulatory adaptation as a downstream concern may encounter production bottlenecks and cost volatility.
Why This Research Matters for 2026 Enterprise Strategy
For executives, investors, and operational leaders, this study is designed to remove ambiguity from capital-intensive decisions in a market where intuition alone is insufficient. The report translates complex market behavior into actionable intelligence across several operational dimensions: revenue concentration patterns, structural segmentation drivers, propulsion-related shifts, material cost trajectories, and competitive positioning across regional and specialist clusters. It also evaluates how recent program launches, evolving client engagement models, and regulatory headwinds are reshaping entry criteria, production economics, and long-term valuation assumptions.
Because the market is highly concentrated and differentiated by craft, brand legacy, and technical capability, generic industry narratives often obscure the real variables that determine commercial success. The full report provides the calibrated detail required to assess which sub-segments are expanding fastest, where revenue is accumulating, and how specific companies are leveraging design language, material economics, and client program structures to defend or extend their advantage. The headline numbers establish direction; the embedded segmentation and company-level analysis enable precise execution planning.
Worldwide Luxury Car Coachbuilding Market
Conclusion: Turning Market Complexity into Competitive Advantage
The worldwide luxury car coachbuilding market in 2026 is not simply growing; it is reorganizing around new production philosophies, material realities, and client experience models. Organizations that understand the interplay between bespoke body construction, retrofitting demand, propulsion transition, and material economics will be better equipped to allocate resources, manage risk, and create defensible positioning in an increasingly selective marketplace. Our Worldwide Luxury Car Coachbuilding Market report provides the evidence base and strategic framing necessary to make those decisions with confidence. To access the complete segmentation breakdown, competitive benchmarking, and forecast detail required for precise planning, we invite decision-makers to consult the full study directly.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Car Coachbuilding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com