

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Military Two-Person Rotorcraft Market to Hit $9.45B in 2025, CAGR 4.35% Through 2032

Unlocking Tactical Agility and Procurement Efficiency in the Military Two-Person Rotorcraft Market
Strategic decision-making in military aviation requires a granular understanding of how crew configurations influence platform versatility, cost structures, and operational deployment strategies. The role of two-person rotorcraft in modern defense architectures has evolved significantly, moving beyond basic utility roles to become critical assets in reconnaissance, light attack, and specialized training missions. Our latest comprehensive analysis, Worldwide Military Two-person Rotorcraft Market, provides the intelligence framework necessary for stakeholders to navigate the complex procurement landscapes of 2026 and the subsequent forecast period through 2032.
As defense budgets recalibrate and operational doctrines shift towards networked warfare and multi-domain integration, understanding the precise trajectory of this niche segment is vital for OEMs, suppliers, and procurement agencies. This article outlines the market dynamics, the strategic value of the underlying data, and the competitive forces shaping the industry, serving as an executive summary of our full research release.
Market Trajectory and Growth Drivers
The market for military two-person rotorcraft is characterized by steady expansion, underpinned by fleet modernization programs, the need for cost-effective training solutions, and the versatility of two-crew configurations in asymmetric warfare environments. Drawing on the latest forecast data, the global market size for these specialized rotorcraft systems was valued at approximately 9,450 million USD in 2025. This valuation reflects a consistent upward momentum from historical baselines observed between 2020 and 2025, signaling a robust demand environment for platforms optimized for pilot and co-pilot or pilot and weapons systems officer configurations.
Looking forward, the analysis projects this growth to continue with a CAGR of 4.35% over the forecast period extending to 2032. By the end of the forecast horizon, revenue is expected to approach 12.7 billion USD. This trajectory suggests that despite procurement cycles and geopolitical fluctuations, the fundamental requirement for two-person tactical air mobility remains resilient. Key drivers include the replacement of aging fleets with modern, tech-enabled equivalents, the integration of advanced avionics that require dedicated crew coordination, and the ongoing demand for light attack and armed scout roles where the two-person cockpit layout offers an optimal balance between operational workload and platform cost.
Worldwide Military Two-person Rotorcraft Market
Segmentation Architecture and Intra-Markety Dynamics
To derive actionable intelligence from the market data, our report deconstructs the revenue streams across multiple classification matrices. Understanding these segments allows operators to identify where value is created and where procurement opportunities lie. While the overarching market shows healthy growth, the distribution of revenue varies significantly depending on the classification criteria applied.
The analysis examines market bifurcation by region, type, and weight class. In terms of rotorcraft type, the data highlights distinct prioritization patterns. Attack rotorcraft continue to command a substantial share of the revenue mix, driven by nations modernizing their air assault and close air support capabilities. Reconnaissance and surveillance platforms constitute a second major pillar, reflecting the increasing emphasis on intelligence, surveillance, target acquisition, and reconnaissance (ISTAR) missions that leverage the agility of two-person crews. Training and utility roles, while representing a smaller fraction of the total revenue, remain essential for sustaining pilot pipelines and supporting logistical operations, particularly in resource-constrained environments.
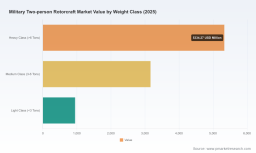
When analyzing the market through the lens of weight class, the report distinguishes between heavy, medium, and light categories. Heavy-class rotorcraft, defined as platforms exceeding 6 tons, represent the dominant segment by revenue, largely due to the higher unit costs and the strategic importance of medium-lift and heavy-lift assets in major defense programs. Medium-class platforms in the 3-to-6-ton range serve as versatile workhorses for multi-role missions, while light-class aircraft under 3 tons address niche requirements for agility, training, and support in forward areas. This segmentation provides critical insight for manufacturing and supply chain planning, as demand signals differ markedly across these weight thresholds.
The report also incorporates geographic segmentation to highlight regional procurement trends without exposing granular regional sensitivities in this overview. Procurement activity is distributed across key defense markets, with North America maintaining a leading position in market value, followed by significant contributions from Asia-Pacific and European theaters. The Middle East and Africa, alongside Latin America, represent emerging or specialized demand centers where two-person rotorcraft are increasingly viewed as force multipliers for localized security challenges and border operations. This geographic dispersion underscores the global relevance of the market and the necessity for OEMs to maintain flexible support and delivery networks.
Competitive Landscape: Strategic Positioning of Key Players
The market is defined by a concentrated group of prime contractors and specialized manufacturers, with the top three players accounting for a significant portion of market value, and the top five firms consolidating a substantial majority of the industry revenue. This concentration highlights the strategic importance of competitive positioning, long-term offset agreements, and technology partnerships in securing defense contracts.
Airbus Helicopters maintains a formidable presence across multiple segments, offering a portfolio that spans light armed scouts, multi-role platforms, and training variants. The H125M addresses the need for single-engine armed scout and light attack capabilities with two-person crew configurations suited for training and tactical transport. The H145M provides a light twin multi-role solution capable of rapid role conversion, including two-crew operations for reconnaissance and light attack. Additionally, the H135M/EC635 supports military training and multi-role missions with two-person crew capability. Recent activity reinforces this positioning: in December 2025, Germany exercised an option for 20 additional H145M light combat helicopters, increasing the total order to 82 units for the German Army and Luftwaffe special forces. Furthermore, Spain placed an order for 50 H145M helicopters as part of a broader 100-helicopter package, and in February 2026, Airbus Helicopters unveiled next-generation rotorcraft concepts, including conventional and high-speed compound designs, in collaboration with RTX and MBDA for the NATO Next Generation Rotorcraft Capabilities study.
Bell Textron continues to reinforce its footprint in the light utility and training segment with platforms like the Bell 505 Jet Ranger X. This light single-engine utility and trainer is actively utilized for military training with two-person crew operations, particularly in forward areas where operational simplicity and efficiency are paramount. Leonardo Helicopters contributes a complementary offering through the AW119/TH-119 single-engine military trainer and utility variant with two-person crew configuration, as well as AW109 variants that deliver light twin multi-role military and utility capabilities with two-crew operations. These platforms address the niche but critical requirement for cost-effective training and multi-role flexibility.
In the attack rotorcraft segment, Russian Helicopters, part of Rostec, produces the Ka-52 Alligator, a coaxial two-seat side-by-side attack helicopter, and the Mi-28 Havoc, a tandem two-seat anti-armor attack helicopter, both designed for intensive military operations. Boeing remains a cornerstone of the heavy attack rotorcraft market with the AH-64 Apache, a tandem two-seat dedicated attack helicopter featuring distinct pilot and gunner crew roles. The presence of these manufacturers illustrates a spectrum of design philosophies and operational doctrines, each shaping the market through differentiated value propositions.
Strategic Implications for Procurement, Supply Chain, and Investment
The report integrates broader industry context to equip decision-makers with a holistic view of the forces influencing the two-person rotorcraft market. Raw material dynamics are increasingly shaping production timelines and cost structures. The aerospace titanium market, valued at 3.1 billion USD in 2025, is projected to reach 3.4 billion USD in 2026, with a CAGR of 8.6% to 2035. This growth is driven by the demand for lightweight, high-strength components in military rotorcraft airframes and rotors, directly impacting the cost base and engineering priorities for two-person platforms that rely on weight optimization for performance.
At the same time, composite-material bottlenecks have been identified as a long-term challenge extending beyond four years for military helicopter production scaling. These constraints are linked to skilled-pilot shortages and supply chain friction for carbon fiber and advanced composites, creating potential risks for delivery schedules and requiring proactive supplier diversification and inventory strategies. The interplay between material availability and production scaling is a critical input for financial modeling and capacity planning.
On the regulatory and geopolitical front, the NATO Next Generation Rotorcraft Capabilities program has advanced with concept study contracts awarded in 2024 to Airbus Helicopters, Leonardo, and Sikorsky for medium-lift replacements targeting operations between 2035 and 2040. This initiative signals a long-term commitment to evolving two-person rotorcraft capabilities and aligns with broader alliance modernization efforts. European military demand has also driven Airbus Helicopters' military order share to 28% in 2025, bolstered by key commitments from Germany and Spain amid ongoing fleet modernization. Such developments highlight how regional procurement momentum can amplify market concentration and influence global supply chains.
What the Report Delivers: Actionable Intelligence for 2026 and Beyond
Our Worldwide Military Two-person Rotorcraft Market research is designed to translate market data into operational and strategic advantage. The report provides a comprehensive dataset encompassing historical performance from 2020 to 2025 and a detailed forecast through 2032. All financial metrics are presented in USD, with revenue figures expressed in millions, enabling precise benchmarking and scenario analysis.
The analysis includes detailed segmentation across type and weight class, giving readers visibility into the revenue composition and growth patterns of attack, reconnaissance and surveillance, and training and utility segments, as well as heavy, medium, and light weight categories. Regional segmentation breaks down market value by geography, helping identify priority markets and procurement hotspots. Market concentration metrics illustrate the competitive intensity and the share held by leading firms, supporting risk assessment and partnership strategy.
Anti Submarine Warfare Helicopter Market
Beyond numerical data, the report profiles key companies, outlining their product portfolios, headquarters, and recent developments. This includes coverage of contract option exercises, major contract awards, and concept unveilings that signal future competitive dynamics. The integration of raw material trends, regulatory programs, and geopolitical drivers ensures that the analysis is grounded in the operational realities affecting production, cost, and demand. For procurement professionals, the report supports timeline planning and capability matching; for OEMs, it informs product roadmaps and regional go-to-market strategies; for investors and financiers, it provides the market sizing and growth logic required to evaluate exposure and opportunity.
The full research suite goes further by dissecting the interplay between crew configuration requirements, platform versatility, and mission profiles, enabling a nuanced assessment of where two-person rotorcraft deliver the greatest strategic value. Readers gain access to the underlying assumptions driving the forecast, the segmentation methodology, and the cross-referenced industry signals that shape the market outlook.
Conclusion: Why This Research Matters for Your Next Decision
In a market where crew configuration, weight class, and mission profile intersect with supply chain constraints and geopolitical priorities, having access to a rigorous, forward-looking analysis is essential. The Worldwide Military Two-person Rotorcraft Market report delivers the depth and structure required to make informed decisions in 2026 and beyond. By synthesizing historical performance, forecast trajectories, segmentation insights, and competitive intelligence, the research equips stakeholders to anticipate demand shifts, evaluate supplier capabilities, and align investment and procurement strategies with evolving operational needs.
To access the complete dataset, regional and segment-level revenue breakdowns, competitive profiling, and detailed methodology, please refer to the full report. The insights presented here offer a strategic entry point, but the comprehensive analysis provides the granular detail necessary for precise planning, risk mitigation, and long-term positioning in this dynamic segment of military rotorcraft.
For detailed analysis of this topic, please visit the official page: Worldwide Military Two-person Rotorcraft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com