

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Caustic Calcined Magnesia Market Hits $840.5M in 2025, 4.85% CAGR to 2032

Navigating the Global Caustic Calcined Magnesia Market Outlook 2026–2032
The worldwide caustic calcined magnesia market stands at a pivotal inflection point as it enters 2026. Shaped by shifting raw material economics, tightening environmental regulations, and evolving industrial demand patterns, the sector presents both strategic opportunities and complex operational variables for manufacturers, distributors, and end-users. This industry analysis draws from our newly published Worldwide Caustic Calcined Magnesia Market research, offering executive-level guidance on how to navigate the next seven-year forecast horizon with precision.
Over the historical review period of 2020 through 2025, the global market demonstrated resilient growth, expanding from approximately 665.4 million USD in 2020 to 840.5 million USD in 2025. This upward trajectory reflects sustained consumption across agricultural, industrial, construction, and environmental applications, underpinned by steady population growth, infrastructure development, and increasingly stringent water and wastewater management standards. Looking forward to 2032, the market is projected to reach 1,170.9 million USD, translating to a compound annual growth rate of 4.85 percent during the 2026 to 2032 forecast period. These figures establish a baseline for strategic capital allocation, capacity planning, and geographic portfolio optimization.
Importantly, the revenue trajectory is not a linear projection but a function of intersecting regulatory, logistical, and competitive forces. Executives evaluating entry points, expansion strategies, or supplier diversification must rely on granular segmentation and scenario-based modeling. Our research provides exactly that: a structured, data-backed framework to interpret where growth concentrates, which demand channels accelerate fastest, and how leading producers are repositioning their operations to capture margin resilience.
Core Report Architecture and Actionable Intelligence
The Worldwide Caustic Calcined Magnesia Market study is engineered to support cross-functional decision-making across procurement, strategy, operations, and investor relations. The report begins with a comprehensive market sizing exercise that reconciles historical shipment data, production economics, and forward-looking demand indicators. Rather than presenting a single headline number, the analysis decomposes total market value across multiple structural dimensions, enabling readers to isolate the variables most relevant to their specific business context.
Worldwide Caustic Calcined Magnesia Market
Key modular components include:
- A detailed segmentation framework covering regional consumption patterns, grade-level positioning, and application-channel distribution, each mapped against historical baselines and 2026–2032 forecast trajectories.
- An end-use demand assessment that traces volume and value drivers across fertilizer and animal feed formulations, chemical processing workflows, magnesia cement manufacturing, wastewater treatment operations, and pulp and paper processing.
- A competitive benchmarking matrix that evaluates market share concentration, operational scale, supply chain footprints, and strategic positioning among the most influential global producers.
- A regulatory and compliance landscape review that captures evolving impurity thresholds, hazardous classification guidelines, occupational exposure limits, and regional trade measures affecting import-export economics.
- A raw material and logistics overlay that tracks magnesite pricing volatility, freight rate fluctuations, and supply-constraint dynamics that directly influence production costs and delivery reliability.
Each section integrates scenario analysis, allowing readers to stress-test projections against plausible shifts in feedstock costs, policy enforcement timelines, or regional demand disruption. This structure is designed to support both top-line growth planning and bottom-line cost containment strategies, ensuring that the insights remain actionable regardless of whether the audience operates on the supply side or within the demand base.
Market Dynamics: Raw Material Economics, Regulatory Evolution, and Logistics Pressure
The operating environment for caustic calcined magnesia is increasingly defined by the interaction between upstream feedstock conditions and downstream compliance requirements. Global magnesite prices rose approximately 12 percent to a range of 180 to 220 USD per metric ton FOB in the fourth quarter of 2024, driven largely by supply constraints originating in China. This movement underscores the importance of monitoring ore availability, processing capacity utilization, and substitution thresholds, as even modest input cost swings can compress margins for producers operating on fixed-price contracts.
On the regulatory front, the European Union tightened impurity limits for magnesia products effective in 2024, requiring less than 0.1 percent heavy metals in caustic calcined magnesia intended for chemical applications under updated REACH requirements. This development has practical implications for product qualification timelines, supplier audits, and formulation adjustments in markets where purity specifications increasingly dictate procurement decisions. At the same time, caustic calcined magnesia remains classified as non-hazardous under the UN GHS framework, though handling protocols must account for dust control measures aligned with occupational exposure limits of 10 mg/m³ TWA, reinforcing the need for compliant packaging, transport, and facility-level safety procedures.
Fused Magnesia Market
Trade policy and logistics have added further complexity. The United States imposed 25 percent Section 301 tariffs on Chinese-origin caustic calcined magnesia imports beginning in September 2024, altering relative cost competitiveness across transatlantic and transpacific supply routes. Concurrently, ocean freight rates for bulk magnesia shipments from Asia to Europe increased roughly 15 percent to a range of 45 to 55 USD per ton in early 2025, influenced by Red Sea disruptions and broader container availability constraints. Together, these variables highlight the necessity of evaluating landed-cost scenarios rather than base ex-works pricing when comparing sourcing options or assessing new market entry feasibility.
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The market structure reflects a moderately concentrated environment, with the top three producers accounting for approximately 38.45 percent of total revenue and the top five players representing roughly 52.6 percent. Such concentration suggests that while scale confers purchasing power and distribution leverage, there remains meaningful room for differentiated positioning based on grade purity, application expertise, certification portfolios, and regional supply proximity.
Among the leading participants, Martin Marietta Magnesia Specialties operates multiple U.S.-based facilities and is recognized for serving water treatment, chemical processing, and fertilizer end-markets with a broad caustic calcined magnesia portfolio. Premier Magnesia focuses on high-purity offerings for environmental, agricultural, and industrial uses, drawing on U.S. quarries and expanding its certified product range to support potable water applications. Grecian Magnesite leverages Greek magnesite resources to supply global markets with an emphasis on steel, refractories, and chemical sectors, while also introducing premium low-iron grades tailored for advanced wastewater treatment. RHI Magnesita contributes to the competitive landscape as a global magnesia supplier with a strong refractory orientation, complemented by chemical-grade offerings and ongoing formulation development showcased at international industry events.
In North America, Baymag produces from Canadian magnesite deposits and supplies animal feed, water treatment, and industrial applications, benefiting from geographic proximity to key North American demand centers. Across the Atlantic, Magnesita Refratários serves South American markets with product grades directed at fertilizers, flue gas desulfurization, and chemical processes, reinforcing the region's role as a localized production hub. On the Asia-Pacific side, Haicheng Houying Group and Qinghua Refractory represent large-scale Chinese manufacturing capacity, the former targeting export markets in steel, environmental, and rubber industries, and the latter supplying refractory and wastewater treatment grades globally. Industrias Penoles provides Mexican-origin caustic calcined magnesia for chemical and environmental applications, offering an alternative sourcing pathway for customers seeking to diversify away from single-country dependency. Meanwhile, Ube Material Industries distinguishes itself through high-reactivity grades designed for pharmaceuticals, electronics polishing, and specialty chemicals, illustrating how technical differentiation can command premium positioning even within a commoditized bulk material category.
Recent corporate activity further signals the competitive intensity of the segment. In October 2024, Martin Marietta Magnesia Specialties announced a capacity expansion at its Woodville facility to address rising demand in water treatment. Earlier in the year, Premier Magnesia achieved NSF/ANSI 60 certification for an expanded caustic calcined magnesia portfolio used in potable water treatment. Grecian Magnesite launched a premium low-iron grade for advanced wastewater applications, while RHI Magnesita showcased new caustic calcined magnesia formulations at the Ceramitec trade fair, reinforcing the broader trend toward application-specific product development and certification-led differentiation.
Regional and Application Dynamics: Where Demand Is Structurally Anchored
The market's geographic footprint and end-use composition reveal the structural anchors shaping long-term consumption. Asia Pacific represents the largest regional demand base, supported by broad agricultural activity, expanding industrial processing capacity, and sustained infrastructure investment. North America and Europe follow as significant consumption centers, each characterized by distinct regulatory drivers, technical grade requirements, and logistics considerations that influence sourcing behavior. Latin America and the Middle East and Africa contribute additional volume, often shaped by localized agricultural cycles, wastewater infrastructure programs, and industrial development initiatives.
At the application level, fertilizer and animal feed formulations account for the largest share of demand, reflecting the material's role in nutrient delivery and feed supplementation across large-scale agricultural operations. Chemical processing ranks as another substantial demand channel, where caustic calcined magnesia serves both as a neutralizing agent and a functional input in specialty chemical manufacturing. Magnesia cements represent a structurally important segment tied to construction and building materials innovation, while wastewater treatment continues to gain relevance as environmental standards tighten and municipal operators seek effective pH control and heavy metal precipitation solutions. Pulp and paper processing adds a further layer of demand, particularly in regions where effluent management and process chemistry requirements drive consistent consumption.
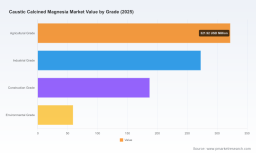
These demand drivers intersect with the grade segmentation that defines product positioning across the market. Agricultural-grade caustic calcined magnesia remains closely linked to feed and soil amendment requirements, industrial-grade offerings support chemical and processing workflows, construction-grade material aligns with cement and building applications, and environmental-grade products cater to water and wastewater treatment specifications. The balance among these grades varies by region and by production source, making grade-level market mapping an essential input for both investment planning and competitive benchmarking.
Strategic Implications for 2026 Decision-Making
For executives planning 2026 initiatives, the market's near-term outlook calls for a disciplined approach to sourcing strategy, product qualification, and capacity risk management. Companies dependent on imported caustic calcined magnesia should evaluate tariff exposure, freight volatility, and alternate origin diversification, particularly in light of evolving trade measures and disrupted shipping lanes. Producers and distributors should assess whether their grade mix aligns with the growing premium placed on purity, certification, and application-specific performance, especially in water treatment and chemical use cases where regulatory specifications are becoming more prescriptive.
Capacity investments should be evaluated against demand visibility and regional logistics advantages rather than headline market growth alone. The observed movements in raw material pricing and freight costs indicate that margin outcomes will increasingly depend on procurement timing, inventory strategy, and the ability to lock in favorable landed-cost positions. Meanwhile, competitive positioning is being reshaped by product specialization, certification milestones, and regional supply resilience, suggesting that long-term advantage will accrue to operators who combine scale with application expertise and compliance readiness.
Why This Report Is Essential for Strategic Planning
The Worldwide Caustic Calcined Magnesia Market research was developed for leaders who need more than a top-line forecast. It delivers a structured, multidimensional view of market size, growth directionality, competitive concentration, regional demand composition, grade-level positioning, and the operational variables that most frequently determine commercial success. By linking demand-side application trends with supply-side constraints, regulatory developments, and logistics realities, the report helps organizations translate macro-level growth signals into practical decision criteria.
Readers seeking a complete view of the segmentation splits, regional and grade-level breakdowns, application-channel distribution, and detailed competitive profiles will find the full dataset and scenario modeling available in the complete report. The publication is designed to support procurement strategy, market entry evaluation, competitor monitoring, and investment prioritization with the level of rigor required for serious 2026 planning. For organizations ready to move from overview to execution-level intelligence, the full Worldwide Caustic Calcined Magnesia Market study provides the comprehensive foundation needed to align strategy with the market's coming dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Caustic Calcined Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com