

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Acute Ischemic Stroke Market Set to Hit $18.2B by 2032, 7.82% CAGR

Charting the Course for Growth: Strategic Imperatives in the Worldwide Acute Ischemic Stroke Market (2026-2032)
Executive Overview
The landscape of acute ischemic stroke (AIS) intervention is undergoing a definitive transformation, driven by technological innovation, evolving clinical guidelines, and shifting demographic realities. As we move beyond 2026, stakeholders across the medical device and pharmaceutical ecosystems must navigate a market characterized by robust growth and intensifying competition. This article serves as a strategic primer based on our latest comprehensive research, offering a high-level view of the forces shaping the industry while underscoring the depth of intelligence available to informed decision-makers.
Our analysis tracks the market trajectory from a base year of 2025 through a forecast horizon extending to 2032. The data indicates a compelling expansion path, with the global market reaching approximately $10.75 billion in 2025 and projected to climb significantly thereafter. This growth is not merely linear; it reflects fundamental shifts in treatment protocols, reimbursement landscapes, and device adoption rates. For executives and investors, understanding the nuance behind these figures is critical for capital allocation, product portfolio strategy, and market entry decisions.
However, macro-level numbers only tell part of the story. True strategic advantage lies in dissecting the underlying drivers—from regional variance in adoption rates to the specific competitive moves of key incumbents. This overview highlights the critical dynamics at play, but the full intelligence required to operationalize these insights requires a deeper dive into our proprietary segmentation and forecasting models.
Worldwide Acute Ischemic Stroke Market
Market Trajectory and Growth Drivers
The recent historical performance of the AIS market demonstrates resilience and accelerating demand. Between 2020 and 2025, the sector expanded from roughly $7.42 billion to over $10.75 billion. This upward momentum is expected to continue, with the forecast period through 2032 suggesting a sustained compound annual growth rate that underscores the increasing reliance on interventional neurology solutions. The projected revenue figures for the late forecast period indicate a substantial increase in total addressable market size, driven by both volume growth and higher-value device utilization.
Key Catalysts for Expansion
Several structural factors are converging to support this growth trajectory:
- Demographic Shifts: The prevalence of stroke risk factors is rising globally. Industry projections suggest that AIS incidence could rise significantly by 2030, particularly in aging populations across the US and Europe, creating a larger patient pool for intervention.
- Guideline Evolution: Recent updates from major clinical bodies, such as the AHA/ASA 2024 guidelines, have expanded the eligibility window for thrombectomy procedures to 24 hours for select patients. This change effectively increases the number of treatable patients per capita, directly influencing device and drug utilization volumes.
- Technological Advancement: Innovation cycles are shortening. The introduction of next-generation devices, including flow diverters for complex aneurysms associated with AIS and enhanced aspiration systems, is driving adoption among clinicians seeking better outcomes and faster procedure times.
- Regulatory and Reimbursement Support: Favorable policy changes are reducing financial barriers. For instance, recent updates to CMS reimbursement rules for eligible thrombectomy devices in the inpatient prospective payment system have improved the economic viability of advanced interventions for hospitals.
While these drivers paint a positive picture, they also introduce complexity. The interplay between regulatory approvals, reimbursement rates, and clinical adoption varies significantly by geography and care setting. Our full report deconstructs these variables to provide actionable forecasts, but the headline message is clear: the demand curve is shifting upward, and organizations must position themselves to capture value in this expanding space.
Cerebrovascular Accident Drug Market
Competitive Landscape and Strategic Positioning
The AIS market is characterized by a moderately concentrated competitive environment where innovation and brand loyalty play pivotal roles. Market concentration metrics indicate that a significant portion of revenue is generated by a core group of established players. This concentration suggests high barriers to entry for new competitors, emphasizing the importance of strategic partnerships, robust clinical evidence, and comprehensive product portfolios for organizations looking to gain share.
Profiles of Key Incumbents
Leading companies are actively shaping the market through product launches, regulatory clearances, and clinical evidence generation. Our research tracks the strategic moves of pivotal organizations:
- Stryker Corporation: Continues to lead in mechanical thrombectomy with advanced retrievers and catheters. Recent moves include the launch of flow diverters aimed at stroke prevention in complex cases, signaling a strategy to address broader neurovascular needs beyond acute clot removal.
- Medtronic plc: Maintains a strong position with its revascularization devices and aspiration systems. Positive long-term study data presented recently reinforces the clinical value proposition of their core assets, strengthening their competitive moat.
- Johnson & Johnson (Cerenovus): Focuses on next-generation revascularization platforms. Recent FDA approvals for updated devices highlight their commitment to iterative innovation in large vessel occlusion treatments.
- Penumbra, Inc.: Specializes in aspiration thrombectomy technologies. Recent regulatory clearances for enhanced aspiration systems demonstrate their focus on improving procedural efficiency and speed, key metrics for stroke care workflows.
- Other Notable Players: Companies such as Balt USA, Terumo Corporation, MicroVention, and Rapid Medical are also active, offering specialized solutions ranging from guidewires and access devices to integrated aspiration systems. Regional expansions, such as securing CE Marks for European markets, indicate aggressive strategies to capture international share.
Strategic interaction among these players involves not just product competition but also competition for clinical mindshare and formulary positioning. Recent developments, including breakthrough device designations granted to multiple new systems in 2025, suggest that the pace of innovation will remain high. Understanding the specific pipeline status and launch timelines of competitors is essential for anticipating market shifts, details of which are exhaustively covered in our full analysis.
Market Dynamics: Reimbursement, Regulation, and Supply Chain
Beyond clinical factors, external dynamics heavily influence market accessibility and profitability. The interplay of policy and logistics creates both opportunities and risks that must be managed proactively.
Reimbursement and Economic Factors
Reimbursement policies are a primary determinant of procedure volume. Recent adjustments to Medicare reimbursement rates for specific thrombectomy devices have improved the financial outlook for hospitals performing these procedures. However, reimbursement landscapes are fragmented globally, and navigating regional payment models requires localized intelligence. Changes in coding and coverage can rapidly alter the adoption curve for new technologies, making real-time tracking of policy updates vital for commercial success.
Regulatory Environment
Regulatory pathways are evolving to encourage innovation. The granting of breakthrough device designations to multiple AIS thrombectomy systems in 2025 reflects a regulatory environment open to novel solutions that offer significant clinical advantages. However, compliance requirements remain stringent. Organizations must balance speed-to-market with rigorous clinical validation to maintain trust and market access.
Supply Chain Considerations
Geopolitical factors are beginning to impact supply chain stability. Recent tariff increases on certain neurovascular components sourced from specific regions add complexity to procurement and cost structures. Manufacturers and distributors must assess their supply chain resilience and consider localization or diversification strategies to mitigate cost pressures and ensure uninterrupted device availability.
Clinical Integration and Workflow
The expansion of treatment windows and the push for faster intervention times require seamless integration of devices into hospital workflows. Products that offer ease of use, compatibility with existing infrastructure, and improved procedural efficiency are gaining preference. This trend favors vendors that provide comprehensive training and support, further entrenching market leaders with established service networks.
Segmentation Overview: Treatment and End-User Focus
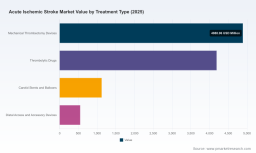
The market is segmented by treatment type and end-user setting, each with distinct growth characteristics. In the treatment category, mechanical thrombectomy devices and thrombolytic drugs represent the largest value pools. The choice between device-based intervention and pharmacological treatment often depends on patient presentation, hospital capability, and clinical guidelines. Device-based interventions, particularly mechanical thrombectomy, are seeing accelerated growth due to efficacy data and guideline support, whereas thrombolytic drugs remain a critical component of the standard of care, especially in settings where advanced imaging or intervention suites are not immediately available.
Accessory devices, including carotid stents, balloons, and distal access tools, constitute a significant portion of the ecosystem, enabling successful interventions. Their adoption is tied to the volume of primary interventional procedures, creating a symbiotic growth dynamic within the product portfolio.
From an end-user perspective, hospitals remain the dominant care setting for AIS interventions, reflecting the need for comprehensive emergency and critical care infrastructure. However, specialty clinics and ambulatory surgical centers are emerging as important venues, particularly for follow-up care and selected procedures. The growth of these alternative settings is influenced by healthcare system restructuring, cost containment pressures, and the push to decentralize care where clinically appropriate. Our report analyzes the specific volume contributions and growth rates across these segments, providing clarity on where value is concentrating.
Regional Perspectives
Geographically, the market exhibits diverse maturity levels and growth potentials. North America continues to represent a significant revenue contributor, supported by high adoption rates, favorable reimbursement environments, and the presence of key innovators. Europe follows as a major market, driven by strong clinical networks and increasing uptake of advanced devices. The Asia Pacific region is often highlighted for its growth potential, linked to expanding healthcare infrastructure and rising disease burden, though adoption dynamics vary widely between developed and developing nations within the region.
Latin America and the Middle East and Africa represent smaller but evolving markets, where access to advanced neurovascular care is improving gradually. Strategic expansion into these regions requires tailored approaches addressing local reimbursement, training, and device distribution challenges. Our research provides granular regional forecasts that help organizations prioritize investment based on risk-adjusted return profiles, though specific regional breakdowns are reserved for the full report to protect proprietary insights.
Conclusion: Strategic Imperatives for 2026 and Beyond
The Worldwide Acute Ischemic Stroke Market presents a landscape of substantial opportunity layered with complexity. The convergence of demographic trends, clinical guideline expansions, and technological innovation creates a favorable demand environment. However, realizing value in this market requires more than recognizing growth trends; it demands a nuanced understanding of competitive positioning, reimbursement dynamics, and regional variability.
Organizations must ask critical questions: How do our product pipelines align with expanding treatment windows? Are we prepared for supply chain disruptions and cost pressures? How can we leverage clinical data to differentiate in a competitive field? Answering these questions requires access to detailed, forward-looking intelligence that goes beyond surface-level statistics.
This overview has highlighted the macro dynamics and strategic themes defining the AIS market. Yet, the decisions you make in 2026 depend on precision. You need specific forecasts, competitive benchmarking, and segmentation analysis that can inform product launches, pricing strategies, and market entry plans. Our full market research report delivers this depth, offering the comprehensive intelligence necessary to navigate the upcoming years with confidence.
For stakeholders committed to capturing growth in the acute ischemic stroke sector, the next step is to engage with the detailed data. We invite you to access the complete study to unlock the full spectrum of insights, from granular market sizing to actionable competitive profiles, ensuring your strategy is built on the strongest possible foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com