

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
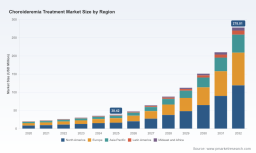
PW Consulting: Choroideremia Market Hits $38.42M in 2025, Projected to Reach $278.01M by 2032

Navigating the Therapeutic Frontier: Strategic Insights from the Worldwide Choroideremia Treatment Market 2026–2032
The global landscape for choroideremia treatment is undergoing a structural transformation. Once confined to supportive care and low-vision management, the market is now defined by a rapidly maturing pipeline of gene therapies, optogenetic approaches, and small-molecule vision-restoration candidates. For pharmaceutical executives, investors, and clinical strategy leaders, understanding this inflection point requires more than a snapshot of trial readouts. It demands a rigorous assessment of commercial viability, regulatory asymmetry, manufacturing bottlenecks, and the shifting economics of ultra-rare ocular indications. The Worldwide Choroideremia Treatment Market market research report has been designed specifically to meet that need, translating complex clinical and regulatory developments into actionable strategic intelligence for 2026 decision-making.
A Market in Accelerated Expansion
Historical tracking from 2020 through 2025 reveals a consistent upward trajectory in market revenue, reflecting growing clinical engagement, expanded trial activity, and heightened institutional interest in inherited retinal diseases. Building on that foundation, the forecast window from 2026 through 2032 points to a sustained compound annual growth rate of approximately 32.65 percent, measured in U.S. dollars and expressed in millions. This growth profile is not merely a function of patient volume; choroideremia affects roughly one in 50,000 males, placing it firmly within the ultra-rare disease category. Instead, the expansion is being driven by a combination of therapeutic innovation, orphan-drug incentives, and a recalibration of how developers and payers evaluate clinical endpoints for progressive retinal degeneration.
For strategy teams, the macroeconomic signal is clear: the addressable commercial horizon is widening, but the path to commercialization remains highly fragmented. Revenue trajectories are being shaped by trial design choices, delivery modality selection, regional regulatory tolerance, and the financial endurance of small and mid-cap biotechnology firms. The report structures this complexity into a coherent analytical framework, allowing stakeholders to stress-test assumptions about adoption curves, reimbursement readiness, and the timing of potential product launches across distinct therapeutic modalities.
Why 2026 Requires a Refreshed Strategic Lens
The year 2026 represents a pivotal calibration point. Several programs that dominated earlier development conversations have reached definitive inflection points, while others are entering new regulatory and clinical phases. The market research report situates these developments within a forward-looking commercial architecture, helping organizations answer the questions that matter most to capital allocation and portfolio planning: Which therapeutic approaches are most likely to navigate endpoint requirements? Where do regional regulatory frameworks create divergent approval pathways? How do manufacturing and vector-production constraints influence scalability and cost structures?
A central theme woven throughout the analysis is the regulatory asymmetry between major jurisdictions. Data reviewed in the report highlights that choroideremia gene therapy candidates have historically faced challenges in meeting primary endpoint thresholds that require substantial best-corrected visual acuity improvements. At the same time, alternative regulatory expectations in certain regions may accept more moderate gains as clinically meaningful, potentially enabling region-specific commercialization strategies. Understanding where those tolerances intersect with trial design, patient selection, and long-term follow-up data is essential for companies evaluating launch sequencing, partnership structures, and geographic prioritization.
What the Report Delivers: Content, Structure, and Operational Value
The Worldwide Choroideremia Treatment Market study is built for practitioners who need defensible inputs for pricing strategy, market-entry timing, pipeline benchmarking, and partnership evaluation. Rather than functioning as a passive data repository, the report integrates clinical context, regulatory mapping, and commercial modeling into a single decision-support instrument. Executive and analytical audiences will find structured coverage across the following operational dimensions:
- Historical baseline and forecast architecture: A detailed reconstruction of market revenue from 2020 through 2025, followed by forward-looking projections through 2032. This provides a grounded reference for scenario planning, sensitivity testing, and investment hurdle-rate calibration.
- Therapeutic modality segmentation: The analysis breaks down the treatment landscape by gene therapy, vitamin and nutritional supplementation, and low-vision aids. Each segment is examined through the lens of clinical rationale, development maturity, reimbursement potential, and commercial feasibility, giving readers a comparative view of where value creation is most concentrated.
- End-user and care-delivery mapping: Specialty hospitals, ophthalmic clinics, and ambulatory surgery centers are evaluated as distinct adoption environments. The report assesses how procedure setting, physician adoption patterns, and infrastructure requirements shape demand dynamics for advanced ocular therapies.
- Regional framework and market concentration: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are contextualized as separate strategic arenas, each with its own regulatory rhythm, reimbursement logic, and competitive intensity. The report also examines concentration dynamics among leading participants, highlighting how dominance is distributed across the pipeline and what that implies for new entrants.
- Regulatory, reimbursement, and manufacturing realities: Orphan-drug pathways, advanced therapy medicinal product frameworks, and endpoint expectations are mapped alongside the practical constraints of AAV vector production, GMP manufacturing consistency, and the financial exposures faced by developers targeting ultra-rare indications.
- Competitive benchmarking and recent catalysts: Company-level profiles are paired with recent developmental milestones, enabling readers to track how asset transfers, trial progress, and regulatory designations are reshaping the field in real time.
By integrating these layers, the report serves as a reference point for both near-term tactical decisions and multi-year strategic planning. It is particularly useful for teams evaluating co-development structures, licensing opportunities, investor narratives, or internal pipeline prioritization in ocular and rare-disease portfolios.
Competitive Field: Who Is Shaping the Next Wave
The competitive landscape is defined by a mix of biotech innovators, nonprofit research entities, and legacy programs that have been repositioned through asset transfers. The report provides structured profiles and activity tracking for the organizations that are most actively influencing development momentum and market expectations.
Kiora Pharmaceuticals, based in Encinitas, California, is advancing KIO-301, a small-molecule photoswitch intended to restore visual function in inherited retinal diseases. While its primary development focus has centered on retinitis pigmentosa, the report examines the explicit potential expansion pathway into choroideremia, alongside recent progress in functional vision endpoint validation and ongoing Phase 2 dosing activity. The analysis highlights why a non-gene-therapy modality could alter both the risk profile and the commercial architecture of the market.
Ray Therapeutics, headquartered in Berkeley, California, is developing RTx-015, an optogenetic channelrhodopsin-based gene therapy aimed at vision restoration. Its Phase 1 ENVISION trial is evaluating intravitreal delivery and includes choroideremia among the conditions under assessment. Recent regulatory recognition, including FDA RMAT designation, is treated within the report as a signal of momentum, but also as a catalyst that raises expectations for safety, delivery consistency, and longer-term efficacy readouts.
The Choroideremia Research Foundation, located in Springfield, Massachusetts, has emerged as a distinctive force in the field following its acquisition of Spark Therapeutics’ SPK-7001 gene therapy assets in 2025. The report details how the foundation is now analyzing long-term Phase I/II clinical trial data and natural history studies to identify patient-relevant endpoints that could support future development or regulatory use. This nonprofit-led asset stewardship model is examined not only as a clinical story, but also as a structural precedent for how discontinued or deprioritized programs can retain commercial and scientific relevance.
Spark Therapeutics’ SPK-7001 program, which used an AAV2-hCHM-101 subretinal gene therapy approach, previously demonstrated safety objectives with some self-reported stabilization. Following program discontinuation, the assets were transferred to the foundation, and the report uses this transition to illustrate how intellectual property, biological materials, orphan designations, and clinical data can retain value even when a commercial sponsor steps away.
The report also addresses programs that illustrate the inherent risk profile of the space. Biogen’s earlier work on timrepigene emparvovec, including the Phase 3 STAR trial, did not meet the primary endpoint threshold of a substantial visual acuity improvement, and active commercial pursuit of the program was discontinued. Similarly, 4D Molecular Therapeutics advanced an intravitreal AAV gene therapy into Phase 1 before terminating the program in early 2025 to prioritize other pipeline assets. These cases are analyzed as cautionary reference points for endpoint sensitivity, delivery modality selection, and the capital intensity of ocular gene therapy development.
Worldwide Choroideremia Treatment Market
Regulatory, Reimbursement, and Manufacturing Dynamics as Strategy Drivers
A defining feature of the current market is the tension between scientific ambition and commercial realism. The report treats regulation, reimbursement, and manufacturing not as background context, but as primary drivers of strategic choice. Gene therapy programs for choroideremia must navigate endpoint expectations that can vary by jurisdiction, and the analysis notes that differences in how primary endpoints are defined and interpreted may lead to region-specific approval pathways. This matters for companies deciding where to seek initial authorization, how to design confirmatory evidence packages, and which clinical signals to prioritize during trial execution.
Reimbursement dynamics add another layer of complexity. High development and manufacturing costs associated with AAV-based gene therapies create financial risk for smaller biotechnology firms, especially when targeting ultra-rare populations. The report explores how these cost structures influence pricing expectations, partnership requirements, and the sustainability of standalone commercialization strategies. It also examines how orphan-drug designations and advanced therapy frameworks can support development, while still leaving unresolved questions about long-term access, budget impact, and payer willingness to absorb premium pricing for narrowly indicated therapies.
On the operational side, AAV vector production and consistent GMP manufacturing are identified as key constraints affecting both cost and scalability. Whether delivery is subretinal or intravitreal, the ability to produce reliable, GMP-grade vector material at appropriate scale remains a critical determinant of development continuity and eventual commercial readiness. The report contextualizes these manufacturing realities alongside the broader pipeline, helping readers assess which programs are better positioned to manage supply-chain risk and which may face structural headwinds as they advance.
How Stakeholders Can Use the Report in 2026
For executive teams and strategy functions, the report is designed to support several high-value use cases. Portfolio planners can use the forecast architecture and modality segmentation to compare risk-adjusted opportunity across gene therapy, optogenetic, photoswitch, and supportive-care pathways. Business development teams can leverage company profiles and recent catalyst tracking to identify partnership targets, asset-acquisition opportunities, and trial-design benchmarks. Regulatory and market-access strategists can draw on the jurisdictional analysis to anticipate endpoint scrutiny, prepare for divergent approval expectations, and frame reimbursement narratives that reflect both clinical promise and economic constraint. Investors and financial analysts can use the market concentration discussion and historical baseline to interrogate growth assumptions, competitive exposure, and the durability of emerging leads.
Worldwide Refsum Disease Treatment Market
Just as importantly, the report is built to be revisited. The choroideremia treatment landscape is evolving quickly, and the strategic questions that matter today will continue to shift as trials report, assets change hands, and regulatory expectations mature. By grounding those dynamics in structured market data and competitive context, the study gives organizations a stable reference point for interpreting new developments as they emerge.
Conclusion: From Clinical Promise to Commercial Clarity
The worldwide choroideremia treatment market is no longer defined solely by the absence of approved disease-modifying options. It is increasingly shaped by a set of competing scientific approaches, uneven regulatory expectations, and a financial environment that rewards both innovation and disciplined execution. The Worldwide Choroideremia Treatment Market market research report translates that complexity into a structured, decision-ready format, giving stakeholders the analytical grounding needed to plan with confidence in 2026 and beyond. For teams seeking a deeper look at segmentation, regional dynamics, concentration metrics, and the full set of company-level findings, the complete report provides the granular intelligence necessary to convert market insight into strategic action.
For detailed analysis of this topic, please visit the official page: Worldwide Choroideremia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com