

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cold Formed Steel Frame Market Hits $39.86B in 2025, Projected 5.29% CAGR to 2032

Navigating the Next Chapter: Why the 2026 Cold-Formed Steel Frame Market Demands Strategic Foresight
The global construction landscape is undergoing a structural recalibration. As urbanization accelerates and sustainability mandates tighten, cold-formed steel (CFS) framing has moved from a niche alternative to a mainstream backbone of modern building systems. For executives, investors, and supply chain leaders, the question is no longer whether CFS will capture additional market share, but how to position portfolios, pricing strategies, and partnership networks ahead of the inflection points visible in the 2026–2032 forecast window. Our newly updated Worldwide Cold Formed Steel Frame Market research is designed precisely for that moment of decision. This briefing outlines the strategic contours of the study, the competitive forces reshaping the space, and the macro dynamics that will separate resilient operators from reactive followers.
A Market at the Intersection of Scale and Structural Shift
Over the past half-decade, the global CFS framing market has demonstrated a resilient upward trajectory, with aggregate revenue climbing from the mid-$31 billion range in 2020 to nearly $40 billion by the 2025 base year. That momentum is projected to carry the market past the $42 billion threshold in 2026, before a series of compounding growth phases push the top line toward the high-$50 billion territory by the end of the forecast period. The implied compound annual growth rate across the full horizon sits at 5.29 percent, a figure that signals durable expansion rather than speculative volatility.
Worldwide Cold Formed Steel Frame Market
What makes this trajectory strategically meaningful is not the headline number alone, but the velocity and consistency of the expansion. The 2020–2025 historical window captures a market absorbing pandemic-era supply disruptions, evolving code frameworks, and a gradual but decisive shift toward lighter, prefabricated building systems. From 2026 onward, the forecast model reflects a more mature demand profile: project pipelines that are less sensitive to single-cycle fluctuations, material substitutions that are increasingly evaluated on lifecycle cost rather than first cost, and regional development programs that favor speed-to-completion and labor efficiency. For strategy teams, that means CFS is no longer a defensive hedging play against wood or concrete constraints; it is an offensive platform for capturing value in mid-rise, high-rise, and modular construction segments where precision engineering and schedule certainty carry premium margins.
What This Research Delivers: An Executive-Ready Intelligence Architecture
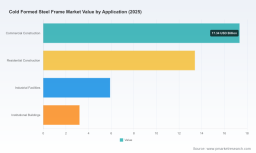
A market study earns its place on a strategy team’s desk only when it translates complexity into actionable architecture. Our analysis is structured to do exactly that. Rather than presenting a monolithic top-line projection, the report disaggregates the market into product-type, application, and regional dimensions, allowing leadership to isolate growth vectors that align with specific capabilities, procurement footprints, and risk tolerances. Decision-makers can examine how C-shaped sections, U-shaped track sections, Z-shaped sections, and hat channels and accessories each carve out distinct demand profiles across commercial, residential, industrial, and institutional end uses.
Beyond segmentation, the study embeds the operational realities that determine execution success. The forecast framework is paired with an assessment of supply chain dependencies, including the behavior of primary feedstock inputs that influence coil pricing and mill pass-through dynamics. It also maps the regulatory cadence that shapes specification behavior, from updated structural design specifications to the evolving code-compliance expectations that govern framing installation, load capacity, and span performance. Sustainability is treated not as a narrative sidebar but as a procurement filter: environmental product declarations, embodied carbon considerations, and lifecycle compliance pathways are evaluated for how they alter specification priority in bids where green building certification and low-carbon procurement clauses are becoming standard.
Perhaps most importantly, the report ties market sizing to the competitive behaviors that generate it. By examining how key manufacturers position themselves across geographies, product families, and application verticals, the study provides a lens for assessing where consolidation pressure is likely to intensify, where technology-driven differentiation—such as precision roll-forming and software-assisted framing design—creates defensible moats, and where distributor and fabricator relationships will determine speed of market penetration.
The Competitive Landscape: Scale, Specialization, and the Push for Code-Compliant Advantage
The CFS framing arena is populated by players whose strategic postures span the full spectrum from commodity-scale steel supply to highly specialized framing system engineering. At one end sit large integrated steel producers whose coil and material outputs form the foundational input stack for the framing ecosystem. These firms benefit from vertical integration, which can translate into better cost visibility and supply reliability when feedstock markets become volatile. Their global reach also means they are often the first to respond to demand signals in multiple regions, shaping the pricing environment that downstream formers and framing manufacturers must navigate.
At the other end of the spectrum are specialist roll-formers, prefabricated system providers, and technology-forward framing solution companies. Some have built reputations around precision-formed sections and accessories tailored for mid-rise and high-rise commercial projects, often in close alignment with industry associations that publish code-compliant guides and load/span references. Others have leaned into sustainability as a differentiator, publishing environmental product declarations and engineering low-embodied-carbon framing systems that meet emerging procurement requirements. A further cluster of players focuses on connectors, bridging, and accessory systems optimized for modular and rapid construction workflows, where the value proposition is less about metal volume and more about installation speed, structural integration, and labor productivity.
This diversity matters because the market is not consolidating into a single model of competition. Instead, it is stratifying. Vertically integrated material suppliers can compete on cost stability and volume availability. Specialized formers compete on specification inclusion, product consistency, and technical support. Software-linked framing solution providers compete on design-to-fabrication efficiency and the ability to accelerate project timelines. For executives evaluating partnership, acquisition, or capacity-expansion options, the relevant question is not which segment is largest, but which segment offers the best fit with a firm’s existing integration profile, geographic reach, and customer access. The research unpacks these positioning dynamics so that leadership can avoid the common mistake of assuming that share growth follows automatically from capacity growth.
Market Dynamics: Feedstock Volatility, Code Evolution, and the Sustainability Mandate
Three dynamic forces are shaping the strategic environment around CFS framing in 2026 and beyond. The first is the behavior of upstream material pricing. Hot-rolled coil, a primary feedstock input for many cold-formed products, has shown meaningful year-over-year movement, with recent spot indications reflecting construction and automotive demand pressures alongside broader mill economics. While framing manufacturers do not control coil pricing, they are deeply affected by its trajectory and by the timeliness of pass-through mechanisms, contract structures, and inventory strategies. In this environment, the firms that manage downside risk most effectively are those that combine supply diversification, forward visibility into specification pipelines, and pricing frameworks that preserve margins without forfeiting bid competitiveness.
The second force is regulatory and standards evolution. Updated technical guides and design specifications are tightening the link between product performance, installation practice, and code compliance. When associations release revised framing guides aligned with newer building codes and when design specifications are refreshed with updated load and span parameters, the immediate effect is not just technical; it is commercial. Specification behavior shifts, engineering teams recalibrate project assumptions, and fabricators must ensure that their product range and quality systems remain aligned with the newest reference points. Companies that anticipate these updates and embed them into product development and sales enablement gain an edge in bids where compliance certainty and engineering support influence spec-in decisions.
The third force is sustainability as a specification driver. Environmental product declarations and low-embodied-carbon framing systems are increasingly relevant in project evaluations, particularly where contracts incorporate carbon-reduction targets or where building certification frameworks reward transparent lifecycle data. This does not mean sustainability is replacing cost or structural performance as primary selection criteria. It does mean that sustainability is becoming a gatekeeping attribute in a growing subset of commercial and institutional projects. Manufacturers that can demonstrate cradle-to-gate transparency, documented impact data, and code-compliant performance simultaneously are better positioned to compete in specification processes where multiple technically acceptable solutions are evaluated on total project value.
Why 2026 Decision-Making Requires a Forward-Looking Intelligence Framework
The 2026–2032 window is not a plain extrapolation of recent trends. It is a period in which regional development programs, material cost cycles, code refresh cycles, and sustainability procurement practices will interact in ways that create uneven growth across segments. Some product categories will benefit disproportionately from project type shifts. Some applications will see faster adoption where labor constraints and schedule pressure are most acute. Some regions will experience stronger momentum due to infrastructure spending patterns, urban densification, and the maturation of local fabrication ecosystems. Without a granular view of these interactions, strategy teams risk planning against an average that does not exist in practice.
This research is built to reduce that blindness. It gives leadership a structured way to test assumptions about where demand is most durable, which product families are most exposed to substitution risk, and how competitive intensity is likely to evolve as manufacturers adjust capacity, broaden accessory portfolios, and invest in design-to-build efficiency. It also provides context for financial planning: margin trajectories depend not only on end-demand volume but on input cost management, specification win rates, and the ability to move up the value chain through engineered systems rather than commodity sections alone.
How to Use This Study for Immediate Strategic Action
The report can be deployed in several practical ways. For corporate development and M&A teams, it offers a landscape map of who competes where, what capabilities matter most, and where consolidation or partnership logic may be strongest. For commercial and sales leadership, it clarifies which application verticals and product types present the clearest near-term opportunity and which require longer-cycle specification cultivation. For procurement and supply chain executives, it frames the feedstock and pricing environment in a way that supports hedging, contracting, and inventory decisions with greater confidence. For sustainability and regulatory affairs teams, it links market growth to the compliance and documentation requirements that increasingly shape project eligibility.
Most critically, the study is designed to support prioritization. Not every growth opportunity is equally accessible, and not every competitive threat is equally material. By separating headline momentum from segment-level drivers, the research helps decision-makers allocate capital, talent, and commercial attention to the areas where the next cycle of value creation is most likely to concentrate.
Light Gauge Steel Market
The Window Is Open, but the Detail Determines the Advantage
The global cold-formed steel frame market is expanding with enough scale and structural momentum to reward proactive strategy, but the payoff will go to those who understand the shape of that growth rather than merely its size. The macro arc is clear: demand is rising, the forecast horizon supports sustained expansion, and the competitive field is evolving across scale, specialization, and sustainability. What remains beneath the surface—and what this study is built to reveal—is the granular architecture of that expansion: where share is migrating, which product and application combinations carry the strongest forward demand, and how the leading manufacturers are positioning themselves to capture it. For executives who need to turn 2026 uncertainty into a defensible growth plan, the full analysis provides the intelligence layer required to move from observation to action.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Formed Steel Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com