

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Glaucoma Diagnostics Market Hits $2.67B in 2025, Projected 5.01% CAGR to 2032

Navigating the Next Wave: Strategic Imperatives in the Global Glaucoma Diagnostics Market
Blindness caused by glaucoma remains a pressing global health challenge, yet the market designed to detect and monitor it is evolving at an unprecedented pace. According to the latest Worldwide Glaucoma Diagnostics Market research by PW Consulting, the industry stands at a critical inflection point. With a projected revenue trajectory accelerating from USD 2.67 billion in 2025 to USD 3.82 billion by 2032, the sector is poised to compound at a steady 5.01 percent CAGR. For healthcare strategists, medical device executives, and investment professionals, this growth narrative is not merely a statistical forecast—it is a blueprint for where capital, innovation, and clinical adoption will converge over the next seven years.
Why 2026 Is a Make-or-Break Year for Glaucoma Diagnostics Strategy
The forecast horizon of 2026 through 2032 reveals more than incremental expansion; it maps a structural realignment in how glaucoma is screened, diagnosed, and tracked. Our analysis traces the market's historical arc from 2020 to 2025, capturing the resilience of demand even as supply chain volatility and regulatory shifts tested manufacturer agility. By 2024, total sector revenue had already crossed the USD 2.5 billion threshold, and the momentum into 2026 suggests a decisive shift toward integrated diagnostic workflows. This is the year where early adopters of AI-enabled imaging, wireless tonometry, and home-monitoring platforms will either secure clinical loyalty or risk ceding ground to competitors who master the operational and reimbursement complexities of modern ophthalmic care. Our report is engineered to help decision-makers separate signal from noise before the 2026 planning cycle locks in.
What the Research Delivers: Actionable Intelligence Beyond the Headlines
PW Consulting's Worldwide Glaucoma Diagnostics Market study is built for practitioners who need to act, not just observe. The report dissects the competitive landscape, product segmentation, end-user adoption patterns, and regional demand drivers through a lens of commercial applicability. Rather than offering a static snapshot, we provide a dynamic framework that connects clinical innovation to procurement realities, reimbursement pathways, and regulatory timelines.
- Product-Type Forecasts and Technology Adoption Curves: We evaluate how optical coherence tomography, tonometry platforms, fundus imaging, visual field analyzers, and emerging diagnostic modalities are shaping procurement priorities across care settings.
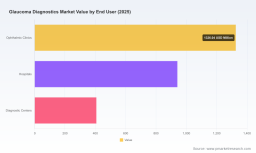
- End-User Demand Mapping: The research tracks investment and consumption patterns across ophthalmic clinics, hospital systems, and independent diagnostic centers, revealing where volume growth and margin opportunities are likely to concentrate.
- Regional Demand and Adoption Dynamics: Our geographic analysis contextualizes how mature markets and high-growth regions differ in procurement behavior, reimbursement maturity, and clinical workflow integration, helping leaders prioritize market-entry and expansion strategies.
- Regulatory and Reimbursement Intelligence: The report integrates evolving device classification requirements, coding structures, and reimbursement benchmarks that directly influence adoption velocity and purchasing decisions.
- Competitive Profiling and Strategic Posture Analysis: We examine how leading manufacturers are positioning their portfolios, accelerating product cycles, and leveraging clinical evidence to defend or expand share.
The Competitive Arena: How Incumbents and Challengers Are Shaping the Field
The glaucoma diagnostics ecosystem is defined by a concentrated yet highly contested competitive structure. Our analysis indicates that a relatively small group of established players commands a majority share of industry revenue, yet the margin for differentiation is expanding as technological innovation outpaces traditional procurement cycles. The leading ecosystem includes manufacturers from Germany, Japan, the United States, Switzerland, and Finland, each reinforcing distinct clinical value propositions.
German precision engineering continues to anchor a significant portion of the high-end imaging segment. Zeiss maintains a strong presence through its OCT systems and glaucoma-focused analytics, most recently underscored by the launch of the Cirrus 6000 OCT with enhanced glaucoma analytics software in October 2025. Nearby, Heidelberg Engineering has advanced its Spectralis platform with a dedicated glaucoma module for retinal nerve fiber layer analysis, and its November 2024 release of Spectralis 6.0 introduced AI-based glaucoma progression detection, reinforcing the shift toward algorithm-driven monitoring.
Japanese manufacturers are broadening the field with integrated imaging and functional testing portfolios. Topcon Healthcare's Triton swept-source OCT and Harmony perimeter platform have become central to glaucoma diagnostic workflows, and the company's June 2025 FDA 510(k) clearance for the Harmony2 AI-enabled visual field analyzer signals a decisive move toward intelligent perimetry. Nidek continues to reinforce the tonometry segment with instruments such as the TS-6100 tonometry system and Perceptra tonoplex, while Canon Medical Systems supports screening-oriented workflows through its RX2 non-contact tonometer and imageFIRST OCT. Kowa rounds out this cohort with its Prominence fundus camera and GC-1 pachymeter for comprehensive glaucoma evaluation.
On the other side of the Pacific, U.S.-based innovators are pushing the boundaries of corneal biomechanics and portable diagnostics. Reichert Technologies has strengthened its footprint with the Tono-Vera applanation tonometer and Ocular Response Analyzer, and its March 2025 introduction of wireless connectivity reflects a broader industry emphasis on data integration and remote workflow compatibility. Carelon Medical Technologies is pursuing a distinctly modern angle with the Phelcom Eyer portable fundus camera enhanced by AI for glaucoma detection, a configuration that aligns with decentralized screening and point-of-care trends.
European and transatlantic players continue to influence both clinical standards and home-monitoring adoption. Haag-Streit remains a reference point in visual field testing through its Octopus perimeters and AT 900 applanation tonometer, while Finland's iCare has carved a specialized niche in rebound tonometry with devices such as the iCare TA01i for clinic and home IOP monitoring. The clinical relevance of home-based monitoring was further validated in September 2024, when iCare presented HOME2 study results supporting self-monitoring use cases at a major ophthalmology conference.
What unites these players is not just product capability, but the race to embed diagnostics into longitudinal care pathways. As AI-enabled interpretation, connected devices, and patient-administered monitoring gain traction, competitive advantage will increasingly depend on how well manufacturers can align hardware performance with software intelligence, clinical evidence, and provider workflow integration.
Prostate Cancer Diagnostics Market
Market Dynamics: Regulation, Reimbursement, and the Adoption Equation
Growth in glaucoma diagnostics does not occur in a vacuum. The pace at which new devices reach the clinic, and the speed at which they are adopted, is heavily shaped by regulatory classification and reimbursement architecture. Our research situates these forces within the practical realities that procurement teams and clinical leaders navigate every day.
From a regulatory standpoint, device classification continues to influence time-to-market and development cost. In the United States, non-contact tonometers are classified as Class II devices subject to 510(k) premarket notification, a framework that directly affects product launch sequencing and competitive entry timing. At the same time, international performance standards such as ISO 8619:2019 continue to define expectations for Goldmann-type applanation tonometers, reinforcing the importance of compliance in procurement decisions.
Reimbursement realities are equally decisive. In the U.S., coding and coverage structures determine whether a diagnostic capability translates into sustainable clinical utilization. CPT code 92133, which covers confocal microscopy of the optic nerve for glaucoma, carried Medicare reimbursement averaging USD 35.62 in 2025, while visual field examination under CPT code 92081 is reimbursed at approximately USD 25 to USD 40 per eye under Medicare Part B. These reimbursement parameters influence not only which tests are prioritized in clinic, but also how providers evaluate the economic case for expanding diagnostic capacity.
Worldwide Glaucoma Diagnostics Market
Together, regulatory classification and reimbursement visibility create a layered adoption environment. Manufacturers that anticipate coding pathways, align device features with reimbursable indications, and provide robust clinical documentation will find a faster path to implementation. Conversely, promising technology that fails to fit cleanly into existing reimbursement and workflow structures can stall in pilot phases, regardless of its technical sophistication.
Why This Research Matters for 2026 Decision-Making
As organizations finalize their 2026 strategies, the glaucoma diagnostics market presents a rare combination of steady macro growth and rapid micro-level disruption. Total market expansion is being driven not only by demographic pressure and rising disease awareness, but also by the increasing sophistication of diagnostic tools that enable earlier detection and more consistent progression monitoring. Yet the real strategic question is not whether the market is growing, but where value will accrue within that growth.
This is precisely where PW Consulting's research adds differentiated value. Our study maps the interplay between technology adoption, competitive maneuvering, end-user procurement behavior, and the regulatory and reimbursement environment that conditions commercial success. It is designed to help leadership teams answer practical questions: Which diagnostic modalities are gaining clinical traction? Where are procurement budgets likely to shift over the forecast period? How are leading competitors using product launches, software updates, and clinical validation to reinforce their positions? And how should an organization position itself to capture share without overcommitting to immature segments?
The answers to these questions cannot be reduced to a single headline figure. They require a structured reading of market architecture, where segmentation, geographic variation, and end-user dynamics intersect with product innovation cycles. That is the depth our analysis provides, and why it serves as a strategic companion for planning, investment, and competitive positioning.
Access the Full Intelligence: The Report Your 2026 Strategy Needs
The Worldwide Glaucoma Diagnostics Market report is more than a forecast table. It is a comprehensive decision-support instrument built to inform product strategy, market prioritization, competitive benchmarking, and investment planning across the 2026 to 2032 horizon. Readers who engage with the full study gain access to the segmentation detail, regional context, end-user breakdown, and competitive profiling needed to translate market momentum into executable strategy.
To explore the complete analysis, including the detailed segmentation views, market concentration insights, company profiles, and the latest regulatory and reimbursement context, visit the PW Consulting source page for the full Worldwide Glaucoma Diagnostics Market research. The report is structured to give your team the clarity required to move from awareness to action, with the kind of granular intelligence that supports confident decisions in a market where precision matters.
For detailed analysis of this topic, please visit the official page: Worldwide Glaucoma Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com