

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Used Telehandlers Hit $3.19B in 2025, Set for 5.81% CAGR Through 2032

Strategic Intelligence for the 2026 Fleet Planner: Why the Used and Refurbished Telehandler Market Demands a Disciplined Playbook
The global market for used and refurbished telehandlers has evolved from a peripheral cost-saving alternative into a strategically managed segment that shapes fleet composition, total cost of ownership, and operational resilience across construction, agriculture, and industrial logistics. As procurement teams recalibrate capital allocation for 2026, the interaction between tightening equipment availability, evolving compliance expectations, and shifting material costs has turned second-hand and reconditioned telehandlers into a decisive lever for margin protection and service continuity. A focused, data-grounded assessment of this landscape is no longer optional; it is the foundation for credible fleet strategy, pricing discipline, and competitive positioning.
Drawing on PW Consulting’s newly released analysis, this intelligence briefing previews the scope of our worldwide market study and explains how decision-makers can translate forward-looking research into defensible 2026 operating plans. The objective is not to publish every figure in open view. Instead, we aim to demonstrate analytical rigor, clarify the mechanics behind value migration, and show precisely where deeper segmentation, benchmarking, and scenario planning will pay dividends for executives who need to act with precision.
Macro Trajectory and the Strategic Signal for 2026 Decision-Making
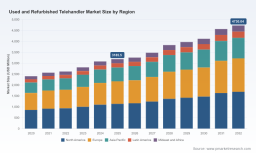
The measured trajectory of this segment over the past five years underscores a structural rebalancing rather than a cyclical rebound. Historical performance from 2020 through 2025 reveals a market that expanded from approximately $2,405.6 million to $3,185.5 million, reflecting sustained demand for cost-efficient material handling equipment alongside persistent pressure on new-unit affordability. This progression did more than lift volumes; it reshaped buyer behavior, dealer inventory strategy, and the economics of certified refurbishment programs across multiple regions and end-use verticals.
Looking ahead, the forecast horizon of 2026 to 2032 indicates continued expansion at a CAGR of 5.81%, with revenue projected to advance through the mid-$3,200 million range in 2026 and progressively toward the $4,730 million zone by the end of the outlook period. These directional signals carry immediate implications for 2026 planning. First, they suggest that demand is not merely returning to pre-disruption levels but is consolidating around more sophisticated procurement models, including certified pre-owned programs, structured maintenance warranties, and rental-integrated access strategies. Second, the pace of growth implies that pricing power, inventory positioning, and service quality will increasingly differentiate participants who can meet compliance and uptime expectations at scale.
For executives, the core strategic takeaway is that the used and refurbished telehandler category is becoming more professionalized and more closely tied to operational outcomes than in prior cycles. As capital expenditure constraints persist, contractors and agribusiness operators are looking for equipment that delivers predictable performance without locking balance sheets into long-lived asset commitments. That trend elevates the importance of accurate market sizing, demand decomposition, and region-specific dynamics—precisely the kinds of insights our full study is designed to provide.
Telehandlers Market
What the Study Covers Beyond Top-Line Figures
A credible strategy requires more than a headline growth rate. Our research is built to give operators, OEMs, dealers, and investors a practical map of where value is created and where risks concentrate. Rather than stopping at aggregate market size, the study unpacks the structural drivers, competitive behaviors, and operational variables that determine whether a 2026 plan is resilient or fragile.
The analysis is organized to support real-world decisions across multiple layers of the business:
- Demand composition across telehandler categories, with attention to how high-reach, compact, and heavy-lift configurations align with different job-site requirements, fleet mixes, and refurbishment economics.
- Application-level segmentation that connects equipment utilization patterns to construction, agriculture, and industrial/logistics workflows, helping readers understand where refurbished inventory flows and why certain verticals absorb supply faster.
- Regional evaluation that places market opportunity in the context of trade flows, dealer network maturity, regulatory environments, and localized procurement culture, without reducing the picture to simplistic rankings.
- Competitive positioning across established manufacturers with active certified-used and refurbished channels, including how OEM-backed programs influence residual value perception, warranty confidence, and customer switching behavior.
- Operational cost factors and supply-side pressures, particularly the interplay between steel input dynamics, component sourcing, and pricing behavior in the refurbished value chain.
- Regulatory and compliance considerations that affect operator certification, inspection standards, documentation requirements, and the commercial attractiveness of used equipment relative to new.
In addition to structural segmentation, the report incorporates scenario-ready context that reflects the external forces shaping 2026 execution. Material cost behavior is examined with attention to how structural inputs influence manufacturing economics and, by extension, the cost floor for both new and refurbished units. Trade-policy signals and tariff developments are assessed for their potential to alter import costs and dealer margin structures. Compliance shifts are mapped to practical operational consequences, especially where increased emphasis on operator certification and digital documentation can raise the attractiveness of well-documented used equipment. The study also addresses the strategic reorientation toward rental and access-based models, which has become a defining feature of how contractors maintain flexibility while managing balance-sheet exposure.
This breadth is intentional. Used and refurbished equipment cannot be understood through a single lens. A dealer may see strong demand in one vertical while facing inventory compression in another. A manufacturer may gain from certified program perception in one geography while confronting cost and compliance headwinds elsewhere. Our framework is designed to help readers interpret those tensions rather than force them into a single narrative.
Competitive Landscape and the Realities of OEM-Backed Refurbishment
The competitive architecture of the used and refurbished telehandler market is defined by the presence of major manufacturers whose new-equipment brands carry spillover advantages into the secondary market. Companies such as JCB, Caterpillar Inc., Manitou Group, JLG Industries, Merlo S.p.A., Dieci S.r.l., Terex Corporation through its Genie brand, Bobcat Company, Liebherr Group, CNH Industrial, Wacker Neuson SE, Haulotte Group, and Claas KGaA mbH each hold distinctive positions shaped by product range, dealer reach, application focus, and certification practices.
One recurring theme is the strategic value of OEM-recognized refurbishment. Caterpillar’s used telehandler programs, for instance, illustrate how inspected and reconditioned models can be channeled through authorized dealer networks with a heavy-duty orientation toward construction and material handling. Manitou’s dedicated used and refurbished inventory across MT and MLA series demonstrates a multi-vertical approach spanning construction, agriculture, and industrial applications. JLG’s used and refurbished options, supported by rental fleets and dealer networks, show how rotating and compact models can broaden access in North American and international markets. Merlo emphasizes rotating telehandler performance with refurbished programs aimed at high-performance construction and agriculture use, while Dieci addresses agriculture and construction demand with compact and heavy-lift options. Bobcat’s certified used programs reflect a compact construction and landscaping orientation, and Liebherr’s dealer-network-based refurbished offerings reinforce a premium heavy-equipment positioning across construction and mining applications.
Beyond manufacturer programs, the competitive environment is shaped by a broader ecosystem of brands with integrated agricultural and material-handling identities. CNH Industrial’s New Holland telehandlers support agriculture and construction through active used equipment sales, while Claas aligns telehandler offerings with broader agricultural equipment portfolios and provides used and refurbished options for farm and light construction use. Wacker Neuson emphasizes compact models for construction and municipal applications, Haulotte supports aerial and material handling needs in construction, and JCB extends its global dealer networks and certified programs into both construction and agriculture. Terex Corporation’s Genie GTH line adds construction and industrial material handling coverage through global sales channels.
What distinguishes the stronger participants is not merely the presence of a used channel, but the consistency with which certification, inspection rigor, warranty structure, and documentation reduce perceived risk for buyers. In a market where residual value confidence and uptime expectations matter as much as headline price, OEM-backed programs can shape purchasing decisions, resale dynamics, and dealer inventory strategy. At the same time, the presence of many capable competitors means that differentiation now depends on operational execution: refurbishment turnaround, parts availability, regional coverage, and the ability to match equipment condition to specific application demands.
Recent industry activity reinforces this competitive intensity. At ConExpo 2026 in January 2026, multiple manufacturers including JLG, Caterpillar, and Manitou showcased telehandler innovations centered on smarter controls, enhanced stability systems, and efficiency features. These product signals matter for the used and refurbished market because they establish the performance baseline that buyers compare against second-hand alternatives. As jobsite material handling technology advances, the relative appeal of refurbished units will increasingly depend on whether they can meet evolving control, safety, and productivity expectations without compromising affordability.
Demand Drivers, Regulatory Pressure, and the Cost Structure Debate
The strategic story of 2026 is incomplete without the operating context that surrounds equipment acquisition and deployment. Several external forces are converging to influence how buyers evaluate used and refurbished telehandlers and how suppliers structure offers.
A dominant trend is the continued expansion of rental and flexible access models for used and refurbished equipment. Contractors and project teams are seeking ways to reduce capital expenditure while maintaining flexibility in infrastructure and construction work. That posture increases the relevance of refurbished units that can be accessed through short-term or project-based arrangements, while also pushing manufacturers and dealers to think beyond outright sale toward service-integrated supply. In practical terms, this means that fleet planners must evaluate not only acquisition price but also availability, maintenance support, and the operational fit of equipment across intermittent deployment cycles.
On the regulatory side, OSHA updates for 2025 place greater emphasis on operator certification, digital documentation, and compliance for heavy equipment, including telehandlers classified as rough-terrain forklifts. The resulting focus on training and inspections can raise the operational value of used equipment that comes with clearer records, documented condition, and verified refurbishment standards. Conversely, equipment with incomplete documentation or uncertain maintenance history may face greater scrutiny, which can widen the perceived gap between certified and uncertified supply.
Trade and material dynamics add another layer of complexity. The increase in U.S. Section 232 steel tariffs to 50% effective June 2025, with certain exceptions, has contributed to higher costs for imported steel components used in construction equipment including telehandlers. That pressure interacts with the broader cost structure of steel manufacturing, where raw materials account for a substantial share of expenses and scrap metal serves as a primary input for electric arc furnace production used in heavy equipment components. At the same time, steel pricing in the U.S. Midwest has shown a pattern of stabilization in the low-to-mid $800s per short ton in mid-2025, with expectations of range-bound to modestly firmer pricing into early 2026 driven by construction demand.
These inputs matter because they influence the cost floor beneath both new and refurbished equipment. For buyers, the implication is that the price differential between new and used units may not behave linearly over time. For sellers and refurbishers, the implication is that component costs, parts availability, and regional sourcing strategies will shape margin sustainability. A market research approach that ignores these cost-side forces risks misreading competitive pricing behavior and inventory strategy.
Why This Study Matters for 2026 Strategy
The central challenge for 2026 is not simply whether the used and refurbished telehandler market is growing, but how growth is distributed across configurations, applications, and regions, and what that distribution means for pricing, inventory, and competitive positioning. Aggregate momentum is useful as a signal, but it is insufficient as a decision instrument. Executives need to know where demand concentrates, which segments show stronger resale resilience, how OEM refurbishment programs influence buyer trust, and where regulatory or cost pressures may alter the economics of acquisition and resale.
Worldwide Used and Refurbished Telehandler Market
The report we have prepared is designed to bridge that gap between directional awareness and execution-ready intelligence. It provides a structured reading of market size progression, forward outlook, segmentation logic, and competitive behavior, while preserving enough granularity for operational use. Critically, it also situates the numbers within the operating environment: rental-led demand models, certification and compliance expectations, steel and component cost pressures, tariff exposure, and product innovation that raises the performance bar for used equipment.
Firms that act on this intelligence can make better decisions about inventory mix, regional expansion, certified program investment, pricing strategy, and partnership selection with dealer and rental networks. Procurement teams can use the same evidence base to time acquisitions more effectively, assess total cost of ownership with greater confidence, and reduce exposure to undocumented or unreliable equipment. Investors and analysts can use the market structure and concentration context to evaluate where competitive advantage is being built and where consolidation risk may emerge.
Where Deeper Intelligence Will Pay Off
Our Worldwide Used and Refurbished Telehandler Market study is intended to serve as the reference point for precisely these decisions. It combines historical grounding, a 2026 to 2032 outlook, segmentation analysis, competitive profiling, and external market context in a single framework. By design, the public-facing preview conveys the strategic logic and the analytical discipline behind the work, while the full report delivers the segmented figures, benchmarking detail, and regional and application-level granularity needed to convert insight into action.
For organizations planning 2026 capital deployment, fleet composition, dealer strategy, or product program investment, the value of this research lies in its ability to turn a complex, fast-moving segment into a structured decision basis. The next step is to examine the full intelligence package, where segmentation, competitive detail, and scenario context are presented with the specificity required for confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com