

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Active Optical Cable Market Hits $4.5B in 2025, Projected 18% CAGR to 2032

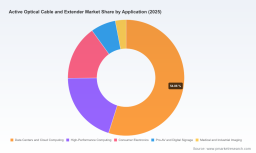
The Optical Backbone of the AI Era: Strategic Intelligence for the Active Optical Cable and Extender Market Through 2032
As enterprises architect the next generation of data infrastructure, the physical layer is no longer a commodity afterthought—it is a strategic bottleneck and a competitive lever. The Worldwide Active Optical Cable and Extender Market research from PW Consulting delivers a structured, forward-looking intelligence framework designed to help technology leaders, procurement directors, and corporate strategists navigate one of the most consequential connectivity shifts in recent memory. Drawing on historical tracking from 2020 through 2025 and a comprehensive forecast window extending to 2032, this study maps how active 광학 connectivity is evolving alongside AI workloads, hyperscale expansion, and tightening edge deployments.
Why 2026 Is a Defining Year for Optical Interconnects
The global market for active optical cables and optical extenders crossed the $4.5 billion threshold in 2025 and is projected to exceed $5.49 billion in 2026, continuing a trajectory that pushes the market well beyond $14.3 billion by 2032. This sustained expansion reflects a compound annual growth rate of roughly 18 percent, a pace that outstrips broader connectivity markets and signals a fundamental rewiring of infrastructure demand. The acceleration is not merely cyclical. It is structural, driven by the convergence of higher-speed interface requirements, longer rack-to-rack reach needs in high-density environments, and the ongoing migration of compute and storage architectures toward optics-based signaling.
For decision-makers planning capital allocation, vendor partnerships, and product roadmaps in 2026, this market profile matters because supplier capacity, pricing behavior, and technology transitions are reshaping the cost and performance assumptions that teams once relied on. The report translates that complexity into a decision-ready format, enabling leaders to benchmark their internal assumptions against a rigorously modeled market baseline and to identify where timing, positioning, and sourcing flexibility will create durable advantage.
What the Study Covers: From Macro Trajectory to Tactical Playbooks
This market research is built for practitioners who need more than headline numbers. It begins with a detailed sizing and forecast model, anchoring historical revenue from 2020 through 2025 and projecting market movement through 2032 in U.S. dollars. The model is structured so that leadership teams can assess momentum across different adoption drivers without losing sight of the market’s overall direction. Alongside the top-down expansion narrative, the report provides a granular breakdown of how demand is spreading across major geographic markets and how the product landscape is divided between active optical cables and optical extenders.
Worldwide Active Optical Cable and Extender Market
The segmentation analysis is paired with end-use mapping that highlights where connectivity demand is intensifying. Rather than treating applications as static categories, the study examines how each segment is being reshaped by hardware refresh cycles, performance ceilings on legacy copper-based solutions, and the push toward higher-density interconnects in mission-critical environments. This approach gives readers a practical way to evaluate where their own product portfolios, distribution channels, or procurement requirements intersect with the largest points of market pressure.
To support operational planning, the report also examines the cost structure and dynamics that influence purchasing and engineering decisions. One of the more consequential findings is the composition of the total bill of materials: transceiver chipsets account for approximately 65 percent of the total cost in active optical cables, while fiber cable itself represents less than 10 percent. That cost concentration has direct implications for pricing negotiations, design choices, and supply risk. The study further explores the ongoing annual price erosion seen in standard 100G active optical cable units, along with the substantial price difference that can exist between OEM-coded configurations and compatible white-box alternatives. These dynamics do not simply affect unit economics; they shape how organizations should structure vendor relationships, validation processes, and inventory strategies.
Competitive Landscape: Who Shapes the Market and How
The active optical cable and extender market is not a fragmented commodity space. It is a concentrated, technically demanding arena in which a relatively small group of manufacturers exerts meaningful influence over innovation cadence, availability, and pricing norms. The report profiles the companies most relevant to enterprise, data center, telecom, and industrial buyers, offering comparative insight into positioning, product emphasis, and strategic intent.
Among the leaders, Corning Incorporated continues to push active optical cable innovation beyond conventional interconnect thinking. Its recent showcase at OFC 2026 highlighted AI-focused developments, including multicore fiber solutions intended to support higher density, the Contour Flow micro cable for data center interconnects, and co-packaged optics systems. This direction signals how incumbent materials and fiber specialists are expanding into the architecture-level decisions that surround cable deployment, especially where space, thermal management, and density constraints are becoming critical.
Molex LLC remains a strong presence in active optical cable portfolios aimed at high-speed data centers, high-performance computing, and storage environments. Its value proposition centers on the practical advantages of optical cable assemblies over traditional modular approaches, with emphasis on cost efficiency, low power consumption, and installation simplicity. For system integrators and facility operators, such positioning matters because it ties product design directly to deployment realities rather than pure performance specifications.
Amphenol Communications Solutions contributes rugged, reliability-oriented active optical cable solutions suited for industrial, data center, and high-density settings, including applications that extend into military and aerospace as well as enterprise networking. Broadcom Inc. supports the market from the integrated connectivity side, supplying active optical cables and components that address hyperscale data centers, high-performance computing, and Ethernet and PCIe-based applications. Coherent Corp., with its heritage in advanced fiber optic transceivers and high-speed interconnects, continues to align its portfolio with the growing demand for 400G and 800G-rate connectivity across data centers, telecommunications, and fast interconnect applications.
TE Connectivity rounds out a major tier of global suppliers with active optical cable assemblies and connectivity solutions serving data centers, telecommunications, and industrial markets. Sumitomo Electric Industries Ltd. and Fujikura Ltd. extend the competitive field with high-speed, low-loss cable solutions designed for enterprise, data center, and telecom infrastructure, reinforcing the importance of fiber-quality and cable-performance engineering in long-term reliability. 3M Company and Siemon further broaden the supplier base, with active optical cable offerings that support enterprise networking and data center environments where standardized, dependable connectivity is essential.
On the Asia-based supply side, a distinct set of manufacturers has built momentum around cost-effective active optical cable production for data center and telecom applications. Shenzhen Gigalight Technology Co., Ltd. is noted for SFP+, QSFP, and higher-speed variants; EverPro Technology Co., Ltd. specializes in SFP+ and QSFP series for high-speed transmission; T&S Communication Co., Ltd. produces active optical cables and related fiber optic components for global markets; and Shenzhen Sopto Technology Co., Ltd. offers a range of active optical cables for networking and data transmission use. These companies are important to the market because they shape price competition, alternative sourcing paths, and the availability of compatible solutions in volume-driven segments.
Fiber Optic Cables Market
Recent developments underscore how quickly the technology frontier is moving. In March 2026, Corning Incorporated used its OFC presence to spotlight AI-oriented fiber and interconnect innovations, including multicore fiber for greater density and Contour Flow micro cable for data center interconnects, alongside co-packaged optics systems. Around the same time, MediaTek announced progress in microLED-based active optical cable technology and later described collaboration with Microsoft Research on miniaturized MicroLED light sources aimed at improving data center efficiency and AI infrastructure. This wave of innovation suggests that the market’s next performance leap may be as much about light-source design, packaging, and density as about cable geometry alone.
Market Dynamics and Structural Risks Decision-Makers Can’t Ignore
The 18 percent growth trajectory is compelling, but growth does not erase friction. One of the most important structural risks in the active optical cable market is component availability. Critical optoelectronic parts such as VCSEL lasers and photodetectors continue to face long lead times and limited manufacturing capacity. In practice, this means some active optical cable configurations can experience delivery timelines stretching to six or eight months. For organizations designing systems around tight build schedules or large-scale rollouts, this supply constraint can turn a seemingly straightforward interconnect choice into a project-level exposure.
Pricing pressure adds another layer of complexity. Standard 100G active optical cable units continue to experience annual price erosion in the range of 12 to 15 percent, a trend that rewards buyers who can plan volume, timing, and specification carefully but also compresses margins for suppliers who cannot differentiate on performance, integration, or support. The price delta between OEM-coded and compatible white-box options can be several times higher, which makes specification control, validation rigor, and supply-chain transparency essential for enterprises trying to balance cost against reliability.
Tariff and trade developments introduce further uncertainty. Increases in tariffs on imported construction and electronic materials can raise project costs and complicate procurement when active optical cable components are part of a broader supply chain. For multinational deployments or multi-tier sourcing strategies, the cost impact of trade policy can be as influential as technology selection itself. These dynamics are not peripheral footnotes. They affect sourcing footprints, inventory buffers, and the financial model behind large-scale infrastructure commitments.
What Strategic Buyers Gain From This Research
The study is designed to support several core decision contexts. For technology and infrastructure leaders, it provides a consolidated view of where the market is heading and which segments are likely to drive the most significant demand shifts. For procurement and supply-chain teams, it frames the trade-offs between performance, delivery risk, and cost in a way that supports more resilient sourcing strategies. For product and business developers, it offers a competitive map that highlights where incumbents, specialists, and Asia-based manufacturers are concentrating their efforts, and how recent technology announcements may reshape expectations over the next planning cycle.
Because the report integrates historical performance, forward forecasts, segmentation insight, and competitive context in one framework, it helps organizations align internal assumptions around a common intelligence baseline. That is particularly valuable in a market characterized by rapid speed-class transitions, uneven component availability, and strong differences in total cost of ownership depending on configuration and sourcing choices. Rather than forcing teams to reconcile fragmented signals, the study provides a focused reference point for evaluating opportunity, risk, and timing.
Looking Ahead: Where to Focus in 2026 and Beyond
The most important takeaway for 2026 is that active optical cables and optical extenders are becoming strategic enablers of compute density, AI infrastructure, and high-speed interconnect design, not just passive transmission media. Demand is being pulled by data centers and cloud computing, accelerated by high-performance computing, and extended by consumer electronics, pro-AV and digital signage, and medical and industrial imaging applications. At the same time, supply-side realities—chipset cost concentration, laser and detector availability, pricing erosion, and trade exposure—are shaping how that demand translates into real-world purchasing and deployment decisions.
For leaders who need to move from high-level awareness to actionable planning, the full report provides the detailed breakdown, scenario-ready segmentation, and company-specific intelligence necessary to support confident decisions. The complete market sizing, regional and application-level analysis, competitive profiles, and forward forecasts are available through the source page, where the full depth of the study can be reviewed in context. In a market expanding at this pace, the difference between reactive purchasing and strategically informed positioning often comes down to the quality of the intelligence underneath the decision. This research is built to provide exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Active Optical Cable and Extender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com