

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Fleet Maintenance Market to Hit $358.1B by 2032, 5.11% CAGR

Navigating the Future of Fleet Maintenance: Strategic Insights for 2026 and Beyond
The global fleet maintenance service market is undergoing a profound transformation, driven by the convergence of advanced telematics, artificial intelligence, and evolving regulatory frameworks. As organizations strive to optimize operational efficiency while managing escalating costs, understanding the trajectory of this sector is no longer optional—it is a strategic imperative. This analysis draws upon comprehensive market research to illuminate the current landscape and forecast the critical trends shaping decision-making through 2032.
Market Trajectory and Growth Dynamics
The worldwide fleet maintenance service market has demonstrated consistent expansion over the past half-decade, reflecting the essential nature of vehicle upkeep in commercial and institutional logistics. Historical data from 2020 through 2025 indicates a steady upward climb in revenue, culminating in a base market size of approximately 252,480 million USD in 2025. This growth trajectory is projected to accelerate moderately through the forecast period ending in 2032, with a Compound Annual Growth Rate (CAGR) of 5.11 percent.
By 2032, the market is expected to reach a valuation exceeding 358,000 million USD. This expansion is not merely a function of inflationary adjustments but represents a fundamental increase in demand for sophisticated maintenance solutions. The mid-2020s, specifically 2026, stand as a pivotal inflection point where the adoption of predictive technologies begins to meaningfully offset traditional reactive models. For enterprise strategists, this signals a shifting value proposition where uptime assurance and lifecycle cost management become the primary drivers of procurement decisions.
Segmentation Shifts and Operational Priorities
The composition of spending within the fleet maintenance ecosystem is diversifying. Revenue generation is distributed across various service types, vehicle categories, and geographic regions, each presenting unique opportunities and challenges for stakeholders. Preventive maintenance continues to command a significant share of the market, underscoring the industry's commitment to scheduled upkeep as a means of avoiding catastrophic failures. However, the rise of predictive maintenance services is gaining momentum, reflecting a broader industry shift toward data-driven decision-making capabilities.
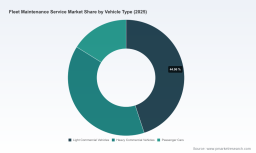
In terms of vehicle types, light commercial vehicles and heavy commercial vehicles represent the dominant segments, reflecting the critical role of logistics and supply chain operations in the global economy. Passenger cars also contribute substantially, particularly within corporate fleets and ride-sharing ecosystems. Geographically, the market is well-distributed, with significant activity across North America, Europe, and the Asia Pacific region. Each region presents distinct regulatory and operational environments that influence how maintenance services are procured and delivered.
It is important for decision-makers to recognize that these segments are not static. As vehicle technology evolves, particularly with the integration of electric powertrains and connected systems, the nature of required maintenance services is changing. Companies that align their service strategies with these segment-specific nuances will be better positioned to capture value in the coming years.
Technology Integration and AI Advancement
Technology is the primary catalyst for efficiency gains in the fleet maintenance sector. The integration of cloud-based platforms, telematics, and artificial intelligence is redefining how maintenance workflows are managed. Modern platforms now offer comprehensive tracking of work orders, inspections, and repair approvals, enabling fleet managers to maintain visibility over asset health without relying on manual processes.
AI-driven service advisors are emerging as a key differentiator, capable of accelerating high-volume repair approvals and simplifying complex maintenance decision-making. These tools analyze vast amounts of vehicle data to recommend actions, prioritize tasks, and control costs. Furthermore, the deployment of AI-powered dashcams and 360-degree visibility solutions is providing real-time safety insights that directly support maintenance decisions. By identifying potential issues before they lead to breakdowns, these technologies help reduce downtime and enhance overall fleet maintenance efficiency.
The move toward unified ecosystems is also notable. Recent developments have seen the launch of platforms that integrate vehicle claims, repairs, and fleet management data into a single interface. This consolidation allows for a more holistic view of fleet health and streamlines the interaction between maintenance providers and fleet operators. For organizations evaluating technology vendors, the ability of a solution to integrate seamlessly with existing infrastructure and provide actionable analytics is a critical selection criterion.
Competitive Landscape and Vendor Dynamics
The competitive environment in the fleet maintenance service market is characterized by a mix of specialized technology providers, large telematics firms, and full-service fleet management companies. The market remains relatively fragmented, with top competitors holding a combined share that suggests ample room for consolidation or niche specialization.
Leading technology firms are focusing on enhancing their software capabilities to offer deeper insights and automation. Companies such as Fleetio, Geotab, Verizon Connect, Samsara, and Trimble are at the forefront of providing cloud-based fleet management platforms, open-platform solutions, and transportation management systems. These vendors emphasize advanced analytics, predictive maintenance, diagnostics, and marketplace integrations to support fleet maintenance optimization and compliance.
Simultaneously, traditional fleet management and leasing companies continue to play a vital role, particularly for large organizations seeking end-to-end solutions. Entities like Ryder System Inc., Penske Truck Leasing, Element Fleet Management, ARI Fleet Management, and Wheels Inc. offer comprehensive vehicle upkeep services, often combining leasing with on-site repairs and dedicated maintenance programs. Their value proposition often centers on cost control, lifecycle management, and the ability to handle large-scale fleet operations.
Worldwide Fleet Maintenance Service Market
Service providers specializing in mobile and on-site maintenance, such as FleetNet America, Dickinson Fleet Services, and Wrench Inc., are also gaining traction by offering convenience and digital management tools. These companies address the need for flexible repair options that minimize vehicle downtime. The presence of diverse player types ensures that fleets of varying sizes and operational complexities can find solutions tailored to their specific needs.
Regulatory and Economic Pressures
External factors are exerting significant pressure on fleet maintenance strategies. Labor costs have become a critical concern, with skilled technician shortages and inflation driving up maintenance rates. Recent sector analysis suggests that repair costs have increased by up to 20 percent in recent periods, compelling fleets to implement higher pay scales and adopt technology tools to address turnover and sustain service levels. This labor dynamic necessitates a strategic focus on efficiency and automation to mitigate cost impacts.
Regulatory compliance is another major driver of change. New enforcement standards and inspection requirements are being introduced to enhance safety and environmental performance. For instance, updates to inspection protocols in California have adjusted requirements for vehicles under specific weight thresholds, aligning some standards with federal annual mandates while maintaining stricter oversight for heavier vehicles. Additionally, changes by the Federal Motor Carrier Safety Administration (FMCSA) include overhauls to compliance measurement systems, splitting vehicle maintenance violations into separate categories. These changes directly impact work order speed and completeness for pre-trip defects, requiring fleets to adapt their maintenance workflows to ensure compliance.
Environmental regulations are also influencing maintenance practices. Programs such as the Clean Truck Check in California impose annual fees and associated costs for emissions-related compliance. These mandates add to the total cost of ownership and require fleets to maintain rigorous records and performance standards to avoid penalties. Navigating this complex regulatory landscape requires robust management systems capable of tracking compliance status and scheduling necessary interventions.
Worldwide Heavy Equipment Maintenance Service Market
Strategic Recommendations for 2026 Decision-Makers
As organizations plan their strategies for 2026 and the subsequent forecast period, several key actions emerge as priorities. First, investing in predictive and preventive maintenance technologies should be a core component of operational planning. The ability to anticipate failures and schedule repairs proactively offers a clear return on investment through reduced downtime and extended asset life.
Second, managing labor constraints requires a dual approach. While competitive compensation is necessary to attract and retain skilled technicians, leveraging technology to streamline workflows and reduce manual effort can alleviate pressure on existing staff. Tools that automate scheduling, tracking, and reporting allow technicians to focus on high-value repair activities.
Third, compliance readiness must be integrated into maintenance planning. With evolving regulations regarding vehicle inspections and emissions, fleets need systems that can adapt quickly to new requirements. Ensuring that maintenance programs are aligned with regulatory standards will minimize risk and avoid costly penalties.
Finally, vendor selection should be guided by a clear understanding of long-term needs. The market offers a wide range of solutions, from specialized software platforms to full-service management contracts. Evaluating vendors based on their ability to integrate, scale, and provide actionable insights will ensure that partnerships contribute to sustained operational excellence.
Conclusion
The worldwide fleet maintenance service market is poised for continued growth, fueled by technological innovation and the enduring need for reliable vehicle operations. For leaders navigating this landscape, the insights provided in the detailed market research offer a roadmap for strategic action. By understanding the underlying dynamics of market size, segmentation, competition, and regulation, organizations can make informed decisions that drive efficiency and resilience. Access to the full intelligence suite will provide the granular data necessary to refine these strategies further, ensuring that fleets remain competitive in an increasingly complex environment.
For detailed analysis of this topic, please visit the official page: Worldwide Fleet Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com