

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Wearable Injectors Market to Hit $9.2B in 2025, 13.5% CAGR Through 2032

Strategic Intelligence in the Worldwide Wearable Injectors Market
The global healthcare landscape is undergoing a profound transformation driven by the shift toward patient-centric drug delivery. Among the most significant advancements in this domain is the rapid adoption of wearable injectors. These devices enable the subcutaneous delivery of large-volume biologics and specialized therapies, offering patients greater autonomy and reducing the burden on hospital infrastructures. As we move into the critical decision-making year of 2026, understanding the trajectory of this sector is not merely an academic exercise but a strategic imperative for stakeholders across the pharmaceutical and medical device value chains.
This report serves as a definitive guide to the Worldwide Wearable Injectors Market, offering a granular analysis of historical performance and future projections. Building on data spanning from 2020 through the base year of 2025, our forecast extends to 2032. The market has demonstrated robust resilience and growth, with revenue climbing from approximately 4.88 billion USD in 2020 to an estimated 9.2 billion USD in 2025. Looking forward, the momentum is expected to accelerate, with the market size projected to reach the 10 billion USD threshold in 2026 and continue its upward trajectory toward 22.3 billion USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 13.5 percent during the forecast period, signaling a high-growth environment that demands agile strategic planning.
The Evolution of Device Architecture and Therapy Integration
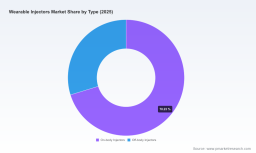
To navigate this market effectively, one must understand the technological bifurcation that defines the current landscape. The market is primarily segmented by device type, distinguishing between on-body and off-body injectors. On-body injectors, which attach directly to the patient's skin for extended delivery periods, currently command a significant share of the revenue mix. These devices are critical for therapies requiring sustained administration, such as certain immunology treatments and chronic disease management protocols. Off-body injectors, while representing a smaller portion of the current valuation, play an essential role in specific acute or shorter-duration therapy scenarios.
The application landscape further illustrates the versatility of wearable technology. Diabetes remains the dominant therapeutic area driving adoption, reflecting the long-standing need for improved insulin and GLP-1 delivery mechanisms. However, the oncology segment is rapidly catching up, fueled by the increasing volume of subcutaneous oncology biologics that require reliable, large-volume delivery systems outside of clinical settings. Cardiovascular applications and other therapeutic areas contribute to the diversified demand profile, ensuring that market risk is distributed across multiple high-value indications. It is important to note that while regional dynamics vary significantly, with North America historically holding a substantial revenue position, the growth vectors are becoming increasingly global, with Asia Pacific and European markets evolving their own distinct adoption curves based on local reimbursement and healthcare infrastructure.
Operational Framework and Alignment with Industry Standards
Our research methodology goes beyond surface-level market sizing. We provide a comprehensive operational framework that allows device manufacturers and pharmaceutical partners to align their development pipelines with prevailing industry standards. The wearable injector market is heavily regulated, and compliance is a non-negotiable barrier to entry. Devices must adhere to ISO 11608-01:2012 for needle-based injection systems and IEC 60601-1 for electrical safety in medical devices. Our report details how these standards impact design cycles, testing protocols, and time-to-market strategies for new entrants.
Furthermore, reimbursement pathways are a critical determinant of commercial success. In the United States, for instance, the Centers for Medicare & Medicaid Services (CMS) assigns specific HCPCS codes, such as A4224 for wearable injector supplies, which are reimbursable under Medicare Part B for subcutaneous drug delivery devices. Understanding the nuances of coding, coverage, and payment policies is essential for pricing strategies and market access planning. Our analysis delves into how these reimbursement structures vary across key territories and how they influence the total cost of care for payers and providers. Additionally, we examine supply chain dynamics, including the cost implications of raw materials. Medical-grade polymers, such as polycarbonate and cyclic olefin copolymer resins used in injector housings, are subject to price volatility, with bulk costs ranging between 8 and 12 USD per kilogram in recent sector analyses. Managing these input costs is vital for maintaining margin health in a competitive environment.
Competitive Landscape and Strategic Partnerships
The competitive field is characterized by a mix of specialized device manufacturers and large pharmaceutical service providers. Market concentration is notable, with the top three companies capturing a significant portion of the market revenue, and the top five entities commanding an even larger share. This concentration suggests that partnerships and ecosystem alignment are often more effective strategies than solo competition for new entrants.
Large Volume Wearable Injectors Market
Key players shaping the trajectory include Ypsomed, based in Switzerland, which is recognized as a leading provider of on-body wearable injectors like the SmartPilot for subcutaneous delivery of biologics up to 20mL. Their focus spans diabetes, oncology, and immunology. In the United States, West Pharmaceutical Services offers the SmartDose platform, featuring electronic control for precise large-volume drug delivery, and has established commercial supply agreements with major pharma partners. Enable Injections, also US-based, has made significant strides with their enFuse wearable injector, which is FDA-cleared and commercialized through partnerships with companies like Lilly for high-volume biologic self-administration.
Other notable contributors include Stevanda from India, which focuses on affordable solutions for biologics in emerging markets using wearable auto-injectors for large-volume subcutaneous injections. Medipim, based in Belgium, manufactures the MPen on-body injector system designed for multi-day delivery of up to 20mL, targeting chronic disease management. Nexus Pharmaceuticals in the USA commercializes wearable injectors through partnerships, including distribution of on-body devices for oncology and rare disease therapies. The strategic moves of these companies define the boundaries of the market.
Worldwide Wearable Injectors Market
Recent Developments and Innovation Cycles
Innovation in this sector is accelerating, driven by the need for connectivity, higher volumes, and regulatory approvals. In October 2025, Ypsomed launched a next-generation SmartPilot wearable injector with improved connectivity for real-time dose monitoring, reflecting a trend toward digital health integration. Earlier in June 2025, Enable Injections received FDA 510(k) clearance for an enFuse wearable injector variant supporting 10mL delivery for new biologic indications, expanding the addressable patient population. In March 2025, West Pharmaceutical Services announced a commercial supply agreement with a major pharma company for their SmartDose platform in subcutaneous biologic delivery, underscoring the importance of contract manufacturing and partnership models in scaling production.
These developments highlight the dynamic nature of the market. Regulatory milestones, such as FDA clearances, are frequent catalysts for valuation shifts and partnership announcements. Companies that can navigate the regulatory landscape efficiently while delivering enhanced user experiences through connectivity and ease of use are positioning themselves for leadership. The restriction of wearable injectors to prescription use only, as per FDA guidance on drug delivery devices, further emphasizes the need for robust clinical validation and physician engagement strategies.
Strategic Imperatives for 2026 and Beyond
As stakeholders prepare their strategies for 2026, several key imperatives emerge from our analysis. First, the integration of digital connectivity into device hardware is no longer optional. Real-time monitoring and data transmission capabilities are becoming standard expectations for both patients and healthcare providers. Second, the diversification of therapeutic applications beyond diabetes into oncology and immunology offers substantial growth opportunities, but requires tailored device configurations and regulatory strategies. Third, supply chain resilience remains a critical focus, particularly regarding the sourcing of medical-grade materials and the management of manufacturing capacity to meet fluctuating demand.
For pharmaceutical companies, the decision to adopt wearable injector platforms involves complex trade-offs regarding device selection, partnership structures, and patient support programs. For device manufacturers, the challenge lies in scaling production while maintaining quality and compliance standards in a concentrated market. Our report provides the detailed segmentation data, regional revenue breakdowns, and specific market share analysis required to make these decisions with confidence. While the macro trends point to a market surpassing 22 billion USD by 2032 with a steady 13.5 percent CAGR, the value lies in understanding the specific drivers within each segment and region.
Conclusion: Accessing Comprehensive Market Intelligence
The Worldwide Wearable Injectors Market represents a high-growth intersection of medical technology and pharmaceutical innovation. With a historical trajectory showing consistent expansion from 4.88 billion USD in 2020 to 9.2 billion USD in 2025, and a forecast projecting significant acceleration through 2032, the stakes for strategic positioning are high. The interplay of regulatory compliance, reimbursement policies, raw material costs, and competitive dynamics creates a complex environment where information asymmetry can lead to missed opportunities or strategic misalignment.
This report is designed to eliminate that asymmetry. By providing deep dives into segmentation splits, competitive profiling, and scenario-based forecasting, we equip leaders with the intelligence needed to navigate the next seven years of market evolution. The data reveals not just where the market is going, but how the underlying components—from regional revenue distributions to specific company developments—are reshaping the value chain. To fully leverage these insights and access the detailed segmentation percentages, specific regional valuations, and comprehensive company profiles that drive this analysis, stakeholders are encouraged to download the full report. The detailed intelligence contained within is essential for crafting a winning strategy in the wearable injectors landscape of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com