

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Smart Ticketing Market to Hit $41.24B by 2032, 12.35% CAGR

The Future of Fare Collection: Strategic Imperatives in the Global Smart Ticketing Ecosystem
The transition from legacy paper-based passes to intelligent, connected fare collection systems is no longer a peripheral upgrade—it is a foundational shift reshaping urban mobility, transit revenue integrity, and passenger experience worldwide. As municipal authorities, transport operators, and private mobility providers navigate shrinking hardware margins, rising cybersecurity expectations, and increasingly complex multimodal journeys, the ability to benchmark investments against verified market trajectories has become a competitive necessity. Our newly released Worldwide Smart Ticketing Market research study delivers precisely that benchmark, translating a decade of historical tracking and a seven-year forward outlook into actionable intelligence for executive decision-makers.
This analysis is designed as a strategic preview for leaders who must allocate capital, select technology partners, and design interoperability roadmaps through 2032. While we outline the structural forces, competitive architecture, and operational dimensions explored in full within the complete report, the nuanced segmentation breakdowns, proprietary scenario models, and granular regional revenue allocations remain embedded in the full study. The objective here is to establish the analytical framework, demonstrate the professional depth of our methodology, and clarify why this intelligence matters for 2026 planning cycles.
Market Trajectory and the 2026 Decision Window
Smart ticketing has moved past the early-adoption inflection point. Historical tracking from 2020 through 2025 reveals a sustained acceleration in system deployments, platform modernization, and payment-integrated fare collection across both mature and emerging networks. The market has expanded from a baseline just above ten billion dollars in 2020 to an estimated valuation approaching eighteen billion dollars by 2025, reflecting not only incremental hardware rollouts but a structural pivot toward software-defined fare management, cloud-native account-based architectures, and user-facing mobility applications.
Looking forward, our forecast period spanning 2026 through 2032 projects continued double-digit expansion, anchored by a compound annual growth rate of approximately 12.35 percent. By the close of the outlook window, total market revenue is positioned to exceed forty-one billion dollars. This trajectory is not linear extrapolation; it reflects compounding adoption across public transit modernization programs, the migration from closed-loop cards to open-payment ecosystems, and the commercial scaling of mobile-first ticketing platforms. For executives planning 2026 budgets, this growth curve signals that timing matters as much as technology selection. Infrastructure commitments made this year will determine cost structures, vendor leverage, and operational flexibility for the remainder of the decade.
Importantly, these headline figures underpin a broader strategic narrative. Growth is uneven across solution layers, and capital efficiency increasingly depends on understanding where value is created—whether through hardware supply chains, software licensing, managed services, or integrated payment processing. Our full analysis disentangles these layers without diluting the macro signal, ensuring that finance and operations leaders can map growth assumptions to realistic project pipelines rather than relying on blended averages.
Worldwide Smart Ticketing Market
Strategic Segmentation: Where Capital and Innovation Converge
A market of this scale cannot be managed through top-line generalizations. The commercial architecture of smart ticketing is defined by how revenue distributes across geographic regions, enabling technologies, and end-use applications. In the complete study, we provide detailed split analyses for each dimension, but even at a strategic level, the structural patterns are clear enough to inform prioritization.
Regionally, the market demonstrates a pronounced concentration of investment in established transit markets with extensive legacy modernization programs, while high-growth regions are driven by first-time system deployments and rapid urbanization. The leading regional blocs each present distinct procurement cycles, regulatory environments, and integration challenges. North American and European networks continue to anchor high-value contract pipelines, while Asia Pacific reflects both the scale of existing mass-transit adoption and aggressive expansion into integrated mobility platforms. Latin American and Middle Eastern/African markets, though smaller in absolute terms, represent increasingly strategic pathways for vendors seeking diversified deployment exposure and governmental modernization funding. The complete report quantifies these divergences with precision, allowing readers to align partnership strategies and go-to-market sequencing with actual revenue distribution rather than intuition.
By technology, the landscape is dominated by mature contactless smart card ecosystems that continue to underpin large-scale transit networks, but the growth momentum is visibly shifting toward software and mobile layers. Mobile application-based ticketing has gained substantial commercial weight as operators seek to reduce physical issuance costs and improve rider onboarding. NFC and QR code-based solutions occupy a critical bridging role, enabling low-friction access, temporary credentials, and multimodal gating across heterogeneous environments. A remaining category captures complementary technologies and specialized deployments. Understanding the relative commercial scale of each technology layer is essential for product leaders deciding whether to emphasize hardware reliability, software integration, or payment interoperability in their roadmaps.
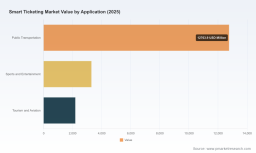
Application-wise, public transportation remains the central revenue engine, reflecting the breadth of bus, rail, metro, and municipal mobility networks that depend on dependable fare collection. Sports and entertainment venues, alongside tourism and aviation touchpoints, form the secondary commercial pillars. These segments carry different procurement drivers: transit priorities revolve around capacity, revenue leakage prevention, and interoperability, while venue and travel use cases emphasize throughput, guest experience, and temporary credential management. Our full segmentation breakdown reveals how each application domain contributes to overall market scale, helping operators and vendors avoid misaligned product positioning.
Competitive Architecture and the Battle for Interoperability
The commercial maturity of the smart ticketing market is mirrored in its competitive structure. Market concentration metrics indicate that the top three players command roughly 42.5 percent of total revenue, while the top five expand that share to approximately 58.2 percent. This concentration does not imply stagnation; rather, it reflects the operational reality that large-scale fare collection systems require proven reliability, regulatory alignment, and integration capacity that fewer vendors can consistently deliver at national or transnational scale.
Several enterprises define the current competitive contour. Masabi has built a recognizable footprint through its Justride mobile ticketing platform, supporting transit agencies with contactless smart ticketing capabilities and extending into direct consumer payment touchpoints. Moovit has positioned itself at the intersection of trip planning and integrated ticketing, offering mobility-as-a-service solutions deployed across thousands of cities, with recent expansion reinforcing account-based ticketing in European markets. HID Global contributes foundational credential and NFC technology, supporting transit environments where secure card-based identity and access remain essential. NXP Semiconductors anchors the hardware supply chain through contactless IC platforms that have become embedded in iconic transit systems globally, illustrating how component-level standards can shape long-term procurement dependencies.
Thales Group extends the competitive field into system-level platforms, including contactless EMV-integrated ticketing for rail and bus networks across multiple continents. Cubic Transportation Systems has advanced account-based mobility platforms that unify fare products across operators and modes, with recent product iterations strengthening QR and NFC multimodal capabilities. Scheidt & Bachmann and Vix Technology round out a competitive field anchored in operational robustness, supplying smart ticketing and fare collection infrastructure for complex public transport and airport environments.
Recent corporate activity underscores how quickly the battlefield is shifting from hardware-centric supply to platform and partnership-centric value creation. In late 2025, Masabi announced integration of its platform with Apple Wallet for express transit mode, enabling tap-to-ride functionality and reinforcing the convergence of transit fare products with consumer payment ecosystems. Earlier that year, Moovit expanded account-based ticketing into additional European cities through partnerships with local transit authorities, highlighting the momentum behind centralized fare accounting. Thales deployed an upgraded contactless EMV ticketing system for a major Asian metro network, demonstrating continued investment in bank-card-based open payment acceptance. Cubic, meanwhile, introduced a next-generation mobility platform with enhanced multimodal ticketing capabilities, reflecting the ongoing push toward unified, cross-operator user journeys.
For buyers and investors, the strategic implication is that vendor evaluation can no longer focus solely on hardware specifications or isolated software features. The decisive questions now involve interoperability commitments, data portability, security governance, and the ability to participate in open payment and open standards ecosystems without creating proprietary lock-in.
Regulatory Pressure and Technical Standards as Market Shapers
The smart ticketing market is being shaped as much by compliance and standardization as by commercial demand. Regulatory interventions and technical specifications increasingly determine what solutions can scale, how quickly they can be deployed, and which architectural choices remain viable over time.
Bus Validator Market
A critical development is the EU regulation mandating open standards for public transport ticketing interoperability across member states by 2026. This creates both pressure and opportunity: operators must align with interoperable frameworks, while vendors and platform providers that already support open architectures gain a structural advantage in multi-country deployments. Simultaneously, payment-integrated ticketing systems handling card data are subject to PCI DSS v4.0 compliance requirements, elevating the cost and complexity of secure transaction processing. These obligations are not peripheral legal details; they influence vendor selection, integration timelines, and total cost of ownership.
On the technical side, contactless smart card ecosystems continue to rely heavily on established communication standards that govern the majority of global transit ticketing implementations. This standardization benefits interoperability and procurement stability, but it also means that differentiation increasingly occurs at the platform, data, and user-experience layers rather than at the basic communication protocol level. In parallel, infrastructure economics remain a real constraint: NFC reader deployment for smart ticketing in urban transit installations typically ranges across several hundred dollars per unit, a factor that influences rollout pacing, phased migration strategies, and the financial justification for device refresh programs.
Together, these dynamics create a market environment where strategic planning must account for compliance roadmaps, standardization timelines, and deployment economics alongside demand growth. The complete report integrates these factors into scenario-based guidance, allowing readers to test investment assumptions against regulatory and technical constraints rather than treating them as background noise.
What the Full Study Delivers for 2026 Planning
Smart ticketing is no longer a niche infrastructure category; it is a strategic layer of urban mobility, revenue protection, and customer engagement. The Worldwide Smart Ticketing Market research study is structured to convert that reality into executable intelligence. Beyond the headline growth trajectory and concentration analysis previewed here, the full report develops a practical decision framework across multiple dimensions that executives can immediately apply.
The study provides:
- Detailed historical tracking and forward projections across the full forecast horizon, enabling baseline calibration for budgets, procurement pipelines, and investor communications.
- Granular segmentation analysis that isolates how revenue distributes by region, technology, and application, allowing leaders to identify where growth is concentrated and where margin dynamics differ.
- Competitive profiling of core participants, with attention to platform strategy, deployment footprint, and recent product or partnership moves that signal shifting advantage.
- Market dynamics assessment that weaves together regulatory mandates, security compliance expectations, standardization impact, and infrastructure cost considerations into a coherent operating context.
- Actionable implications for transit operators, technology vendors, payment partners, and investment stakeholders who must align 2026 initiatives with the longer 2032 outlook.
The strategic value of this research lies in its refusal to treat the market as a single number. Growth magnitude matters, but so does structure: which solution layers are expanding fastest, which geographies offer the most credible contract pipelines, which compliance obligations alter deployment economics, and which competitive moves indicate where interoperability and platform integration are becoming the real battleground. By keeping the macro trajectory grounded in detailed segmentation and operational context, the study helps organizations avoid overgeneralization and make decisions that hold up under scrutiny.
For teams preparing 2026 commitments—whether in platform selection, regional expansion, partnership strategy, or capital allocation—the full report provides the depth required to move from directional confidence to specific, defensible planning. The complete segmentation data, scenario insights, and competitive intelligence are available in the full Worldwide Smart Ticketing Market research release, where the analysis is built to support direct engagement with procurement, finance, and technology leadership teams.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Ticketing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com