

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rugged Servers Market to Reach $1,259.29M by 2032, Driven by 7.4% CAGR

The Worldwide Rugged Servers Market: Strategic Imperatives for the 2026 Landscape
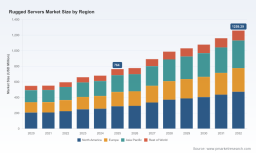
As global industries accelerate the deployment of edge computing, defense modernization, and resilient telecommunications infrastructure, the Worldwide Rugged Servers Market has entered a decisive growth phase. From a base year valuation of 764.00 million USD in 2025, the sector is projected to climb steadily to 1,259.29 million USD by 2032, driven by a consistent compound annual growth rate of approximately 7.4% across the 2026 through 2032 forecast horizon. This trajectory is not merely a function of hardware procurement cycles. It reflects a structural shift in how mission-critical computing is architected, deployed, and sustained in environments where standard commercial infrastructure fails.
Worldwide Rugged Servers Market
Rugged Tablet Market
For executives, procurement leaders, and technology strategists evaluating priorities in 2026, understanding the underlying mechanics of this expansion is no longer optional. Rugged servers now sit at the intersection of geopolitical readiness, industrial automation, energy resilience, and distributed data sovereignty. The PW Consulting Worldwide Rugged Servers Market study is engineered to convert raw market signals into actionable strategic intelligence, providing decision-makers with the clarity required to allocate capital, manage vendor relationships, and anticipate regulatory and environmental shifts before they reshape competitive advantage.
Market Trajectory and the Architecture of Resilience
The historical progression from 2020 to 2025 demonstrates a market that has steadily adapted to intensifying operational demands. Revenue expanded from 550.00 million USD in 2020 to 680.89 million USD in 2024, before crossing the 764.00 million USD threshold in 2025. Looking forward, the forecast window reveals a measured but unmistakable acceleration: valuations are expected to surpass 777.98 million USD in 2026, approach the 988.72 million USD mark by 2028, and continue upward through 2032. This sustained momentum underscores a market that has matured beyond cyclical procurement spikes and is now anchored by long-term program commitments, edge AI adoption, and the need for hardened compute in remote and adversarial settings.
Strategic stakeholders analyzing the 2026 outlook must recognize that growth in this category is fundamentally different from enterprise server dynamics. Rugged deployments face distinct constraints: extreme temperature ranges, shock and vibration exposure, electromagnetic interference, power instability, and stringent certification requirements. These constraints compress design windows, elevate engineering costs, and dictate supply chain discipline. The PW Consulting analysis dissects how these pressures reshape procurement timelines, prioritization frameworks, and total cost of ownership calculations, enabling organizations to map investment decisions against realistic deployment readiness rather than theoretical headline figures.
Structural Forces Redefining Demand Drivers
Several macro forces are converging to accelerate ruggedized compute requirements across defense, industrial, and connectivity sectors:
- Edge AI and High-Density Compute at the Tactical Edge – Deployments are shifting from centralized facilities to forward operating environments, where processing must occur locally under bandwidth constraints and intermittent connectivity.
- Industrial Automation and Harsh Environment Reliability – Manufacturing, mining, and critical infrastructure operators are replacing legacy control architectures with hardened computing platforms capable of surviving dust, moisture, voltage fluctuations, and extreme thermal cycles.
- Telecommunications and IT Modernization – 5G expansion, private network deployments, and distributed data infrastructure are demanding hardened server architectures that can operate outside climate-controlled facilities.
- Energy and Power Infrastructure Continuity – Remote substations, grid monitoring, and power generation sites increasingly rely on resilient compute to support automation, fault detection, and operational continuity.
Competitive Landscape: Differentiated Positioning in a Concentrated Market
Market structure provides critical context for sourcing and partnership strategy. With the top three players collectively representing 38.45% of total revenue and the top five accounting for 52.1%, the competitive environment features meaningful concentration without total consolidation. This creates a landscape where dominant incumbents hold scale advantages in certification pipelines, vertical integration, and defense program alignment, while specialized manufacturers compete through form factor innovation, rapid customization, and regional service footprints.
The PW Consulting study profiles the organizations actively shaping this competitive field, including Trenton Systems, Crystal Group, Systel, Mercury Systems, Advantech, Dell Technologies, Core Systems, Kontron, Curtiss-Wright, General Micro Systems (GMS), MilDef Group, 2CRSi (Tranquil IT), and Rugged Science. Rather than offering generic vendor summaries, the analysis examines how each participant aligns with end-user requirements across defense, industrial automation, telecommunications and IT, and energy and power contexts.
Strategic positioning is increasingly defined by how manufacturers respond to three overlapping pressures: processing density, environmental compliance, and supply chain sovereignty. Recent industry activity illustrates this evolution clearly. In August 2024, Trenton Systems introduced the BAM series rugged servers featuring dual Intel Xeon Scalable processors designed to operate at temperatures up to 70°C, with increased compute density oriented toward edge AI workloads. In October 2024, Systel unveiled the Gray Wolf 2 high-density rugged compute solution at the AUSA Annual Meeting, signaling intensified focus on deployable, mission-oriented processing capacity. December 2024 saw Advantech expand its industrial computing portfolio through new rugged servers and motherboards powered by AMD EPYC and Ryzen processors, reinforcing the broader push toward high-performance embedded architectures.
Activity has continued into 2025, further intensifying competitive differentiation. In January, Crystal Group released new rugged technology systems, including the RE1600M embedded computer and RE4000 data storage solution, strengthening its portfolio for defense and industrial applications in extreme conditions. By July 2025, Rugged Science launched the NOMAD Series, customizable 1U to 3U rugged rackmount servers assembled in the United States and targeted toward mission-critical defense and military applications. These moves reflect a market in which product cadence, certification readiness, and manufacturing location are becoming decisive variables in procurement decisions.
Competitive Dynamics Stakeholders Must Monitor
- Certification as a competitive moat – Compliance with MIL-STD-810 for environmental testing and MIL-STD-461 for electromagnetic compatibility has become table stakes in defense-related procurement, while additional qualifications such as MIL-S-901D for high-impact shock in shipboard environments can determine bid eligibility.
- Form factor strategy and deployment flexibility – The balance between compact, high-density designs and larger chassis architectures directly affects integration complexity, thermal management, and site readiness requirements.
- Regional design, assembly, and data governance – Data sovereignty considerations, including the reach of the U.S. CLOUD Act, are influencing how organizations evaluate vendor origin, data handling practices, and cross-border infrastructure placement for rugged server deployments.
Segmentation Intelligence: Where Value Is Being Captured
Segment-level analysis lies at the core of procurement strategy, yet the full allocation patterns behind each major category are deliberately detailed within the complete Worldwide Rugged Servers Market study. The report examines how demand distributes across regional deployment ecosystems, including North America, Europe, Asia Pacific, and the Rest of World, each characterized by distinct procurement cycles, sovereign requirements, and infrastructure maturity. It also breaks down form factor dynamics across 1U, 2U, and 3U and above rugged servers, analyzing how size constraints, thermal envelopes, and integration scenarios influence choice architecture across end-use scenarios.
Beyond regional and form factor lenses, the analysis maps end-user demand concentration across Military and Defense, Industrial Automation, Telecommunications and IT, and Energy and Power. These categories are not evaluated as static buckets; instead, the study connects each segment to the operating conditions, certification expectations, and deployment architectures that determine which solutions scale successfully in the field. Readers seeking the complete segmentation matrices, comparative sizing logic, and cross-tabulations between region, form factor, and end user are directed to the full report, where the underlying allocation structures and scenario-based sensitivity metrics are disclosed in operational detail.
Report Scope and Actionable Deliverables
The Worldwide Rugged Servers Market study is designed for practitioners who need more than aggregate market narratives. It contains a structured analytical toolkit intended to support sourcing strategy, risk assessment, and investment planning. Core deliverables include a detailed segmentation framework, competitive profiling, historical reconstruction, forecast modeling, and an integrated view of the regulatory and infrastructure conditions that shape deployment feasibility.
What the study delivers
- Segmentation across region, form factor, and end user – Structured breakdowns showing how demand, adoption patterns, and procurement priorities vary by deployment context without oversimplifying nuanced market behavior.
- Competitive profiling and product cadence tracking – Company-level assessments linked to product releases, platform directions, and positioning strategies, anchored by recent development events and product launch trajectories.
- Historical reconstruction and forward forecast – A multi-period view covering 2020 through 2025 history and a 2026 to 2032 outlook, enabling trend isolation, cyclical interpretation, and scenario stress-testing around the 7.4% CAGR baseline.
- Regulatory and operational context integration – Analysis of how environmental standards, electromagnetic compatibility requirements, shock qualification norms, and data governance frameworks influence procurement eligibility and deployment risk.
- Embedded infrastructure considerations – Context around energy consumption dynamics relevant to edge and rugged server deployments, supporting more realistic total-cost and sustainability evaluations when planning distributed compute architecture.
This combination of market sizing, competitive mapping, and operational context allows procurement teams to compare vendor proposals against realistic structural benchmarks, while strategy leaders can use the segmentation logic to evaluate market entry, expansion, or partnership opportunities with greater precision.
The 2026 Decision Environment and Why Full Intelligence Matters
Entering 2026, organizations face a procurement landscape in which delay carries tangible cost. Rugged servers are increasingly tied to multi-year defense modernization efforts, industrial automation capital plans, telecom infrastructure rollouts, and energy-sector resilience programs. In that environment, relying on partial market signals creates exposure to misaligned timelines, weak vendor qualification, and underestimated integration constraints. The full PW Consulting Worldwide Rugged Servers Market study is structured to close those gaps by delivering the segment-level breakdowns, competitive benchmarks, and scenario logic that leadership teams need before committing budget or negotiation leverage.
The differences between headline market size and operational deployment reality are exactly where strategic advantage is won or lost. Understanding how regional demand concentrates, how form factor selection interacts with environmental requirements, and how end-user priorities shift across defense, industrial, telecom, and energy use cases enables organizations to anticipate rather than react. Because the study intentionally preserves detailed segmentation data, competitive matrices, and scenario analysis for the complete version, stakeholders who access the full report gain a direct line of sight into the allocation logic and comparative dynamics that drive procurement outcomes.
For enterprises and public-sector programs planning 2026 initiatives, the strategic question is no longer whether ruggedized compute matters, but how to position procurement, partnership, and engineering decisions around a market that is expanding steadily, consolidating selectively, and demanding higher performance under harsher conditions. The complete PW Consulting Worldwide Rugged Servers Market study provides the structured intelligence required to navigate that environment with discipline, foresight, and competitive confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Rugged Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com