

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Lab Glass Container Market Hits $4.26B in 2025, Forecast 5.42% CAGR to 2032

Navigating the Laboratory Glass Container Landscape: Strategic Intelligence for 2026 and Beyond
The global laboratory glass container market has entered a defining inflection point. As scientific research, pharmaceutical development, and clinical diagnostics accelerate in complexity, the foundational consumables that safeguard experimental integrity are no longer peripheral procurement items. They are strategic assets. Our latest Worldwide Laboratory Glass Container Market report delivers a rigorous, forward-looking intelligence framework designed to equip executives, procurement leaders, and R&D strategists with the clarity required to navigate the 2026 operating environment and the decade ahead.
Worldwide Laboratory Glass Container Market
This analysis is structured around a disciplined forecasting window that begins in the current base year of 2025, incorporates a robust historical track record spanning 2020 through 2025, and projects market trajectories explicitly across the 2026 to 2032 horizon. Every strategic recommendation, competitive assessment, and demand forecast is calibrated to support concrete enterprise decision-making rather than abstract trend commentary.
Market Trajectory: From Recovery to Structural Expansion
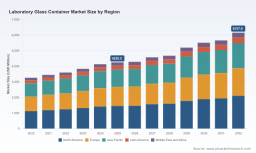
The historical data tells a story of resilient compounding. Between 2020 and 2025, the global market expanded from approximately 3,268.45 million to 4,255.5 million USD, reflecting a consistent upward arc across diverse economic cycles, supply chain recalibrations, and geopolitical disruptions. That acceleration is not decelerating. The forecast trajectory projects the market crossing 4,290.56 million USD in 2026, followed by a robust climb that places revenue at 4,577.41 million by 2027, 4,681.47 million by 2028, 5,201.86 million by 2029, and ultimately reaching 6,157.6 million by 2032.
This progression translates to a compound annual growth rate of 5.42 percent across the forecast window. For operators and investors, that rate signals more than linear expansion. It indicates structural demand shifts driven by sustained biopharma pipeline growth, accelerating diagnostic modernization, and a widening mandate for contamination-resistant, thermally stable containment solutions. The 2026 baseline serves as a critical planning anchor: organizations that calibrate capacity, inventory strategy, and pricing architecture around this inflection point will secure meaningful competitive advantage as the decade's volume escalates.
Strategic Architecture of the Report
The research framework is engineered for immediate operational deployment. Rather than delivering isolated statistics, the report embeds market intelligence within executable business contexts.
- Comprehensive segmentation mapping across product categories, end-user verticals, and geographic markets, enabling precise demand forecasting and resource allocation.
- Granular manufacturer and distributor profiling that clarifies capacity footprints, technological differentiators, and regional supply chain positioning.
- Raw material cost trajectory analysis, with specific attention to the borosilicate glass ecosystem and the pricing dynamics shaping production economics.
- Competitive intensity assessment that maps consolidation patterns, market concentration metrics, and strategic vulnerability zones.
- Scenario-driven planning models designed to stress-test procurement strategies against raw material volatility, regulatory shifts, and demand shocks.
Each section is built to answer operational questions. Which end-user segments will dictate procurement volume through 2032? Where are regional demand centers converging, and which distribution corridors require reinforcement? What cost pressures are embedded in the material supply base, and how should they influence contract structuring and inventory buffering? Executives who internalize these answers will be positioned to move decisively rather than reactively.
Competitive Dynamics and Strategic Positioning
The laboratory glass container sector is characterized by a blend of established industrial incumbents, specialized precision manufacturers, and emerging regional players expanding through portfolio diversification and targeted acquisitions. The market structure reflects this complexity, with concentration metrics indicating that the top three players command a combined share of 38.45 percent, while the top five extend collective control to 54.2 percent. This concentration level signals a moderately consolidated environment where scale, technological reputation, and supply reliability function as decisive competitive moats.
Corning Incorporated remains a defining force in the space, anchored by its PYREX lab glassware reputation for chemical stability, thermal resilience, and contaminant resistance across global scientific and chemistry applications. DWK Life Sciences operates as a consolidated powerhouse, leveraging its integrated formation from DURAN, Wheaton, and Kimble Chase to manufacture premium bottles, vials, and volumetric ware purpose-built for life sciences and research environments. Schott AG continues to lead as a borosilicate glass pioneer, supplying high-precision pharmaceutical containers and laboratory glassware engineered for superior thermal and chemical performance.
Regional manufacturing strength also shapes the competitive map. Borosil Scientific Limited in India has scaled into a major producer of beakers, flasks, bottles, and scientific products, while simultaneously expanding its strategic footprint through acquisitions that extend its portfolio beyond traditional glassware into analytical vials, filtration products, instruments, and pharmaceutical primary packaging. Glassco Laboratory Equipments Pvt. Ltd. and Goel Scientific Glass Works Limited reinforce India's position as a broad-based manufacturing hub spanning educational, research, and analytical markets. In North America, Bellco Glass stands apart as a family-owned manufacturer with long-standing expertise in engineered laboratory glassware and cell culture systems, while Ace Glass Incorporated continues to differentiate through custom laboratory apparatus and scientific glassware innovation. BRAND GmbH + Co KG and Witeg Labortechnik GmbH maintain strong German engineering footprints in volumetric glassware, liquid handling instrumentation, and high-velocity consumable delivery, and Adrian Sistem SRL contributes additional European manufacturing depth for analytical and research-grade applications.
Recent Market Movements and Their Strategic Implications
Industry momentum during 2025 has already begun to reshape competitive trajectories. Borosil Scientific Limited executed a notable business transformation in July 2025, expanding its portfolio beyond traditional glassware into analytical vials, filtration products, instruments, and pharma primary packaging. This shift was reinforced through strategic acquisitions, including Klasspack and Goel Scientific Glass Works, signaling a deliberate move toward higher-value containment solutions and broader pharmaceutical packaging integration.
In parallel, distribution channel expansion is accelerating. Harvard Bioscience extended its distribution agreement with Fisher Scientific in September 2025, broadening access to life science equipment and laboratory consumables across the US market. This move underscores how channel partnerships and consolidation within life science distribution networks are becoming critical levers for market reach, inventory velocity, and end-user accessibility. For manufacturers and procurement organizations alike, these developments highlight the growing importance of supply chain agility, channel alignment, and portfolio breadth as differentiators.
Raw Material Realities: The Borosilicate Cost Equation
No strategic assessment of the laboratory glass container market is complete without confronting the material foundation beneath it. Borosilicate glass remains the dominant formulation for laboratory containers, produced from boron compounds combined with silicate sand, soda ash, and ground lime. Its performance advantages in thermal shock resistance and chemical stability make it the material of choice for demanding scientific and pharmaceutical environments. Its market prominence is substantial, holding an estimated share of approximately 41.3 percent of the laboratory glassware market in 2026.
That dominance, however, comes with increasing cost exposure. Boron availability and pricing dynamics are exerting upward pressure on production expenses, pushing borosilicate manufacturing costs above those of soda-lime alternatives. As raw material cost trends evolve, manufacturers and downstream buyers face a dual challenge: preserving material performance standards while managing margin compression and procurement volatility. The report addresses these pressures through cost structure analysis and procurement strategy guidance, enabling organizations to anticipate pricing shifts, negotiate with informed benchmarks, and evaluate when durability and compliance justify premium material selection versus when alternative specifications may serve specific cost-sensitive applications.
Laboratory Glassware Market
Why This Intelligence Matters for 2026 Decision-Making
The 2026 landscape demands decisions grounded in more than anecdotal demand signals. Procurement leaders must anticipate volume shifts across pharmaceutical and biotech development, academic and research funding cycles, clinical diagnostic throughput, and food and beverage quality testing mandates. Manufacturing and supply chain executives must interpret concentration dynamics, regional demand contours, and material cost trajectories when planning capacity, sourcing diversification, and price architecture. Executives evaluating market entry, acquisitions, or portfolio expansion require a clear picture of where competitive intensity is intensifying and where whitespace opportunity remains underserved.
This report is built to serve those decisions. It integrates historical performance evidence, forecast-calibrated demand trajectories, competitor positioning intelligence, and material cost context into a single decision-support framework. By translating macro market movement into segment-level and actor-level insight, the research equips organizations to align capital deployment, supplier strategy, pricing posture, and risk management with the realities of the 2026-to-2032 growth cycle.
Access the Full Strategic Intelligence
The overview presented here captures the strategic contour of the market and the analytical depth embedded in the full study. Yet the complete intelligence set—the detailed segmentation analysis, comprehensive competitive profiling, regional demand architecture, raw material cost mapping, and scenario-based strategic guidance—extends far beyond a high-level synthesis. Organizations seeking to operationalize these insights, benchmark their positioning, and prepare for the next phase of market expansion will find the full report an essential reference.
To secure the complete Worldwide Laboratory Glass Container Market research and access the full data architecture, segmentation detail, and executive decision frameworks, please visit the source report page. The intelligence inside is designed to convert market complexity into actionable strategy for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com