

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Chinese Domestic Databases Market Hits $3.8B in 2025, Projected 18.5% CAGR Through 2032

Navigating Sovereignty and Scale: Strategic Intelligence for the Worldwide Chinese Domestic Databases Market in 2026
Executive Summary: Why This Research Matters Now
The Chinese domestic database landscape has entered a decisive phase where procurement mechanics, regulatory architecture, and competitive positioning converge to define operational viability for the next seven years. PW Consulting’s Worldwide Chinese Domestic Databases Market research maps this inflection point with a historical baseline spanning 2020 through 2025 and a forward view extending to 2032. The study is engineered not merely to describe where the market has been, but to equip enterprise strategists, technology architects, and regional expansion teams with decision-grade intelligence for 2026 roadmap planning. As multinational platforms recalibrate their Chinese footprint and domestic vendors accelerate product maturity, understanding the structural drivers behind database adoption has moved from IT procurement housekeeping to core business strategy.
This report is designed as a strategic compass rather than a static market snapshot. It breaks down the market along deployment modes, database models, and industry verticals, then layers in competitive profiling, regulatory timeline analysis, and infrastructure cost dynamics that will shape total cost of ownership, vendor selection, and compliance posture. The sections below preview the analytical architecture of the full study, illustrating how each dimension connects to real-world decision-making in 2026.
Market Trajectory and Structural Growth Arithmetic
Revenue history reveals a market that has compounded decisively since 2020, accelerating through a period of cloud migration, distributed architecture adoption, and policy-driven localization requirements. The study tracks revenue progression across the full historical window and projects forward through 2032, with the forecast anchored by a compound annual growth rate of 18.5 percent measured in USD millions. This trajectory is not a straight extrapolation; it reflects the interaction of several reinforcing forces, including the maturation of self-developed database engines, rising enterprise appetite for hybrid transactional and analytical processing, and the fiscal and regulatory environment that increasingly favors domestic infrastructure components.
By establishing a rigorous baseline and forward path, the research enables planners to test budget scenarios, procurement cycles, and capacity investments against a consistent growth frame. The dataset allows decision-makers to align internal forecasting with externally validated market cadence, reducing the uncertainty that typically surrounds database capex and opex planning in highly regulated sectors. Throughout the report, the macro growth curve is contextualized against segmentation behavior and competitive momentum, so that planners can distinguish between headline expansion and the specific demand pools that are likely to drive both volume and pricing pressure.
Segmentation Blueprint: Deployment, Database Models, and Vertical Demand
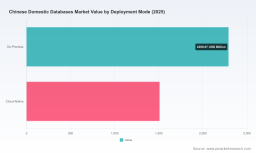
The study divides the market into three analytical dimensions that collectively explain how demand is being formed and where competitive pressure is concentrating. Deployment mode analysis separates on-premise installations from cloud-native deployments, illuminating the migration patterns that are reshaping enterprise procurement and refresh cycles. The database model segmentation distinguishes relational databases from distributed and NewSQL architectures, and further isolates NoSQL and specialized platforms. This breakdown is critical for organizations evaluating modernization paths, because it ties technical architecture choices to workload characteristics, scalability expectations, and vertical compliance requirements.
The industry vertical view maps demand intensity across public sector and government environments, financial services, and telecommunications and energy, with additional scope for enterprise and gaming workloads where relevant. Each vertical carries distinct procurement rhythms, security expectations, and performance thresholds, which means that a single market aggregate can conceal materially different buying behaviors. The research evaluates how these vertical profiles interact with deployment preferences and database model selection, helping strategists anticipate which segments are likely to lead adoption, which require longer validation cycles, and which may create the most durable revenue streams over the forecast window.
Competitive Landscape: Incumbents, Innovators, and Ecosystem Positioning
The competitive field is composed of hyperscale cloud providers, purpose-built domestic database vendors, open-source enterprise platforms, and hardware and systems players that enable large-scale deployments. Alibaba Cloud has advanced its portfolio through self-developed native distributed database technology and cloud-native offerings that emphasize performance leadership and cross-industry financial adoption. Huawei Cloud contributes a distributed database line engineered for high-end applications in banking, telecommunications, finance, energy, and government, reinforcing its position in mission-critical environments. Tencent Cloud extends cloud database services that are tuned for high-transaction workloads and enterprise deployments, with strong in-market presence.
Beyond the cloud hyperscalers, PingCAP has established a leading open-source and enterprise NewSQL distributed database with broad enterprise adoption and hybrid processing capabilities. SequoiaDB has built a specialized financial-grade distributed database footprint across a substantial number of financial institutions, concentrating on secure large-scale transaction data storage. In the broader domestic ecosystem, Wuhan Dameng Database, Beijing Renda Jincang Information Technology, GBase, KingbaseES, and Inspur contribute additional domestic database solutions and infrastructure capabilities that support localization, application innovation, and secure data management in regulated environments. Baidu Cloud rounds out the field with cloud database services integrated into broader AI and big data platforms.
Rather than listing vendors as a rankless catalog, the full report profiles these companies against criteria that matter for 2026 procurement: architectural differentiation, benchmark performance, operational maturity, international expansion moves, and product release cadence. Recent developments included in the research illustrate how quickly product postures can shift. For example, the study tracks product and benchmark milestones that signal performance leadership, broader international availability, and AI-native database experimentation. These events are contextualized within the competitive landscape so that strategists can interpret product news as signals of positioning intent rather than isolated technical updates.
Regulatory and Policy Architecture: Compliance as a Demand Multiplier
Regulatory evolution has become one of the most powerful forces shaping procurement priorities, vendor qualification, and data placement decisions. The study devotes substantial attention to the legal and policy environment that influences both domestic adoption and cross-border data operations. Amendments strengthening data sovereignty, cross-border transfer controls, and penalties for non-compliance have tightened the operational perimeter for organizations handling core and important data. Accompanying requirements enforce strict data localization for sensitive information and mandate security assessments for cross-border transfers, creating a compliance layer that directly influences database architecture and residency choices.
The xinchuang initiative further shapes procurement by driving replacement of foreign database infrastructure in government agencies, state-owned enterprises, and critical industries. This policy framework channels a significant portion of procurement behavior toward domestic alternatives within specific institutional buyers, making localization a strategic sourcing consideration rather than a purely technical one. The full research integrates these policy drivers into the market dynamics discussion so that planners can gauge how regulation alters demand timing, vendor eligibility, and the cost calculus of migration projects.
Infrastructure Economics and Deployment Realities
Database strategy cannot be separated from the physical and cost environment in which it runs. The research incorporates infrastructure context that directly affects deployment economics and vendor selection. Data center capacity has expanded substantially, supporting workload migration under the national East Data, West Computing orientation and enabling broader distribution of database workloads across regions. At the same time, local government electricity subsidies for large data centers using domestic chips help offset energy cost differences, which can improve the competitiveness of domestic infrastructure stacks and influence total operating cost.
These infrastructure dynamics are treated as practical variables in the segmentation and market dynamics sections. For strategists, this means the report does not simply describe policy; it connects policy and infrastructure economics to procurement timing, location decisions, and the relative attractiveness of cloud-native versus on-premise deployment in different operating contexts. Where relevant, the study also notes the importance of reimbursement, subsidy, and energy cost considerations for large-scale deployments, without reducing those effects to a single deterministic conclusion.
Operational Intelligence: What the Report Measures for Planning Teams
Beyond macro trajectory and competitive selection, the study is built around the kinds of practical questions that technology and procurement leaders face when making 2026 commitments. The full report includes vendor profiles with headquarters, product positioning, deployment footprints, and recent product or benchmark events that illustrate strategic momentum. It also provides analytical structure for evaluating deployment mode trade-offs, database model fit by workload, and vertical procurement behaviors, enabling planners to build scenario models rather than rely on generic category assumptions.
Readers will find decision-support coverage that connects market data to real planning tasks: how to prioritize database modernization where regulatory expectations and performance requirements are both rising; where cloud-native migration is likely to accelerate; where on-premise persistence may remain strong due to security, sovereignty, or legacy integration constraints; and how competitive moves should be interpreted as signals of product roadmaps, international reach, and ecosystem partnerships. The research is structured to support both strategic positioning and operational planning, helping teams move from market awareness to procurement-relevant conclusions.
Strategic Takeaways for 2026 Decision-Making
Several decision themes emerge clearly from the study’s architecture. First, database selection in this market is increasingly a balance of technical performance, compliance assurance, and domestic sourcing expectations, and the weight of each factor varies by vertical and deployment model. Second, competitive differentiation is being shaped by both benchmark leadership and product evolution, including distributed architecture maturity, AI-native experimentation, and international expansion moves. Third, the regulatory and infrastructure environment is not peripheral; it is a core driver of procurement patterns, workload placement, and cost structures that must be incorporated into forecasts and sourcing strategies.
Worldwide Chinese Domestic Databases Market
For organizations operating in or adjacent to this market, the most valuable use of the research is to ground 2026 planning in a validated market frame and then test internal assumptions against that frame. The study supports that process by mapping demand along multiple dimensions and by providing competitive and regulatory context that prevents oversimplified conclusions. Because the complete dataset, detailed segmentation analysis, and full vendor profiles contain the precise figures, region-specific dynamics, and nuanced scenario inputs required for execution, the report is designed to be read in full where confidential or granular intelligence is needed.
From Insight to Action: Accessing the Complete Research
The Worldwide Chinese Domestic Databases Market research is intended for teams that need more than high-level context. It is structured to support market sizing validation, competitive scanning, procurement scenario building, and policy-aware roadmap planning across the 2026 to 2032 horizon. This preview has laid out the strategic framework, the analytical dimensions, and the competitive and regulatory context that make the study relevant to 2026 decision-making.
Worldwide Database Testing Tool Market
To obtain the full market size projections, segmentation analysis, concentration structure, vendor profiles, and region-specific dynamics, readers should access the complete PW Consulting report on the source webpage. The full document provides the detailed figures, scenario-ready segmentation splits, and supporting evidence necessary to translate this strategic overview into concrete procurement, investment, and technology decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com