

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Elemental Fluorine Hits $928.5M in 2025, 6.18% CAGR to 2032

Strategic Intelligence for the 2026 Decision-Maker: Navigating the Worldwide Elemental Fluorine Market
In the landscape of specialized industrial chemicals, few commodities command as much strategic attention as elemental fluorine. As we transition from the historical baseline of 2025 into the forecast period spanning 2026 to 2032, organizations involved in the supply chain must recognize that this is not merely a commodity market but a critical enabler of advanced technologies. Our latest comprehensive study, the Worldwide Elemental Fluorine Market research, is designed to equip executive leadership with the foresight required to navigate this complex environment.
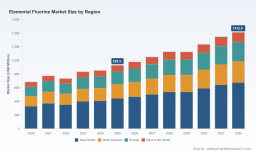
The market has demonstrated resilience and steady expansion over the past half-decade. Historical data from 2020 through 2025 indicates a compound annual growth trajectory that underscores the inelastic demand for high-purity fluorination agents. The overall market size, measured in millions of USD, has climbed from approximately 685.4 million in 2020 to an estimated 928.5 million in the base year of 2025. Looking forward, the forecast period projects a continuation of this momentum, with a CAGR of 6.18 percent. This growth is not linear; it is punctuated by supply chain constraints and regulatory shifts that require nuanced understanding. Our report deconstructs these trends to provide actionable intelligence rather than simple extrapolations.
Market Overview and Growth Trajectories
Understanding the macroeconomic flow of elemental fluorine is essential for capacity planning and investment strategy. The revenue stream has shown sensitivity to raw material costs, yet the demand side remains robust due to enduring requirements in semiconductor manufacturing and energy security sectors. The projected valuation for the market is expected to reach upwards of 1.4 billion USD by 2032. This expansion suggests that while volumetric growth is steady, the value capture opportunities differ significantly across application verticals and grade specifications.
Fluorine Gas (F2) Market
Strategic planners must note that growth rates vary when adjusting for inflation and feedstock volatility. The forecast period highlights 2026 as a pivotal year where pricing dynamics stabilize post-recent disruptions, only to face new pressures from upstream raw material constraints. The research details the correlation between anhydrous hydrogen fluoride costs and elemental fluorine pricing, providing a model for cost forecasting that accounts for fluorspar market fluctuations.
Segmentation Dynamics: Applications and Grades
The demand for elemental fluorine is bifurcated primarily by grade and application. Our analysis distinguishes between Industrial Grade and Electronic Grade specifications, each serving distinct value chains with different margin profiles. Electronic Grade fluorine, essential for high-precision semiconductor etching and cleaning, commands a premium due to stringent purity requirements. In contrast, Industrial Grade supplies broader chemical synthesis and nuclear fuel processing needs.
Application-wise, the market is driven by several key sectors. Uranium enrichment remains a cornerstone of demand, tied closely to national energy security policies and geopolitical stability. Simultaneously, the semiconductor manufacturing sector represents a high-growth vector, driven by the continuous shrinking of node sizes and the need for advanced fluorination processes in chip fabrication. Other significant applications include sulfur hexafluoride production for electrical insulation and the synthesis of fluorinated organic chemicals used in pharmaceuticals and agrochemicals.
The interplay between these segments creates opportunities for diversification. Companies that can bridge the gap between industrial bulk supply and high-purity electronic specifications often capture greater market share. Our report provides a detailed breakdown of volume splits and revenue contributions across these categories, allowing stakeholders to identify which verticals offer the highest return on investment relative to regulatory burdens.
Regional Geographic Insights
Geographically, the market is concentrated in specific hubs that align with both manufacturing capabilities and raw material availability. The Asia Pacific region stands as the largest consumption zone, reflecting the density of semiconductor fabs and chemical processing facilities in countries like Japan and broader East Asian markets. North America follows as a significant region, driven by domestic energy needs and a robust pharmaceutical sector. Europe maintains a steady presence, heavily influenced by regulatory frameworks such as REACH.
The Rest of the World segment includes key production sites in Africa and other mining-rich regions that feed the upstream supply chain. Our geographic analysis goes beyond simple consumption maps; it evaluates logistics corridors, trade barriers, and regional pricing differentials. For instance, the disparity in fluorspar production concentration between China and other regions creates arbitrage opportunities and supply risks that are meticulously mapped in the study. Understanding these regional inefficiencies is key to optimizing procurement strategies.
Competitive Landscape and Key Players
The market structure is characterized by high concentration, with the top three competitors holding a significant share of the global supply. The top five players command an even larger portion of the market, indicating a barrier to entry that protects established incumbents. This oligopolistic structure means that supply disruptions from a single major player can ripple through the global supply chain.
Key participants include Air Products and Chemicals, Inc., headquartered in Lehigh Valley, Pennsylvania. As a leading global supplier of ultra-high purity elemental fluorine gas, their focus on semiconductor etching and pharmaceutical synthesis positions them as a critical partner for high-tech industries. Solvay SA, based in Brussels, Belgium, produces elemental fluorine through electrolysis at facilities including the US. Their portfolio serves fluorochemical intermediates and nuclear fuel processing, though they have faced operational challenges such as force majeure declarations on hydrogen fluoride production following facility incidents.
Pelchem SOC Ltd, located in Pelindaba, South Africa, is recognized as the world's largest dedicated producer of elemental fluorine gas. They supply high-purity F2 for uranium enrichment and agrochemicals, making them a linestock for energy and agricultural security. In Asia, Kanto Denka Kogyo Co., Ltd. in Tokyo specializes in high-purity gas for electronics and solar cell manufacturing, while Stella Chemifa Corporation in Osaka manufactures fluorine compounds for semiconductor cleaning and lithium battery materials.
Recent developments highlight the volatility inherent in this competitive landscape. In 2022, Solvay declared force majeure on hydrogen fluoride production following a fire at their Green River, Wyoming facility, impacting downstream elemental fluorine supply. Conversely, in 2021, Pelchem SOC Ltd restarted full elemental fluorine production capacity after a scheduled maintenance shutdown. These events illustrate the fragility of the supply chain and the importance of monitoring operational status updates for key suppliers.
Supply Chain and Regulatory Risk Factors
Operationalizing elemental fluorine involves navigating a maze of regulatory and logistical hurdles. Elemental fluorine is classified as UN 1045, Poison Gas 2.3. This classification requires specialized UN-approved cylinders and strict adherence to DOT and EU ADR transport restrictions. Compliance is not optional; it is a fundamental constraint on logistics speed and cost. Furthermore, EU REACH authorization has been required for fluorine under Annex XIV since 2020, with ongoing reviews for industrial uses due to high reactivity and toxicity. These regulatory layers add time and cost to market entry and expansion plans.
Worldwide Elemental Fluorine Market
Raw material volatility presents another layer of risk. Acid-grade fluorspar prices averaged 289 per metric ton in 2023, up from 258 in 2022. This upward pressure directly impacts the cost of anhydrous hydrogen fluoride feedstock, which is the precursor for elemental fluorine production. In North America, anhydrous hydrogen fluoride spot prices rose to 2,800 per metric ton in the third quarter of 2023 amid fluorspar shortages. Additionally, China accounted for 64 percent of global fluorspar production in 2023, with export quotas tightened under Ministry of Commerce policies affecting HF and F2 supply chains. These factors create a volatile cost environment that must be hedged through strategic procurement.
Strategic Value of This Research
This report is not merely a collection of data points; it is a strategic tool designed for 2026 decision-making. It enables procurement directors to model cost scenarios based on fluorspar price volatility. It allows strategy officers to assess the risk exposure of relying on concentrated supply chains in specific regions. For R&D leaders, the segmentation analysis clarifies where purity demands are evolving, particularly in the electronics sector.
The inclusion of historical performance data from 2020 to 2025 provides a baseline for stress-testing current business models against past disruptions. The forecast period extends this utility, offering a window into future capacity requirements. By understanding the concentration ratios and the specific profiles of key competitors like Air Products and Pelchem, companies can better negotiate contracts and plan for contingencies.
Conclusion: Acquiring the Full Intelligence Picture
The Worldwide Elemental Fluorine Market is at a juncture where demand growth intersects with significant supply side constraints and regulatory complexity. The 6.18 percent CAGR projects a robust future, but realizing value in this market requires granular insight into who is producing what, where, and under what regulatory conditions.
The overview provided here scratches the surface of the available intelligence. To fully equip your organization for the challenges and opportunities of the 2026 to 2032 period, a detailed examination of the segmentation splits, regional revenue distributions, and specific competitive moves is necessary. We invite you to visit the source webpage to access the complete market research report. There, you will find the full dataset, including detailed regional and application segmentation breakdowns, comprehensive company profiles, and the proprietary models used to derive these strategic forecasts. Do not rely on approximations for such a critical input material; secure the detailed intelligence required to lead in the elemental fluorine market.
For detailed analysis of this topic, please visit the official page: Worldwide Elemental Fluorine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com