

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 9.5% CAGR for Global Medium Entropy Alloys Market in 2026-2032

Strategic Radar: Navigating the Medium Entropy Alloys Market in 2026 and Beyond
Executive Overview
The materials science landscape is undergoing a profound transformation, driven by the demand for components that can withstand extreme environments while maintaining structural integrity. At the forefront of this shift is the Worldwide Medium Entropy Alloys Market. As industrial sectors push the boundaries of performance, medium entropy alloys have emerged as a critical solution, offering a balanced approach between the complexity of high entropy systems and the familiarity of traditional alloying methods. For strategic leaders operating in aerospace, defense, energy, and advanced manufacturing, understanding the trajectory of this market is no longer optional—it is a imperative for supply chain resilience and product innovation.
This analysis serves as an introduction to our latest comprehensive research publication. It highlights the macroeconomic signals, competitive tensions, and operational imperatives defining the sector. The goal is to equip decision-makers with the context needed to anticipate shifts in cost structures, technology adoption, and regional supply dynamics through the forecast period ending in 2032.
Market Trajectory and Growth Dynamics
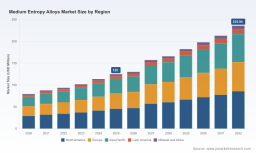
The economic footprint of medium entropy alloys has expanded steadily over the last half-decade, reflecting a transition from niche research applications to broader industrial implementation. Historical data indicates a consistent upward trend in market revenue, signaling robust adoption rates across key verticals. Starting from a baseline in the early 2020s, the market has demonstrated resilience despite broader economic fluctuations. By the base year of 2025, the sector achieved a significant revenue milestone, setting the stage for accelerated expansion in the coming years.
The forecast period projects a compelling growth CAGR, underscoring the increasing reliance on advanced material compositions for high-performance applications. This growth is not merely a function of volume but reflects a deepening integration of these alloys into critical infrastructure and next-generation technology platforms. Companies that recognize the timing of this expansion are better positioned to secure long-term supply agreements and invest in compatible manufacturing capabilities. The revenue trajectory suggests that the market will more than double in size by the early 2030s, representing a substantial value creation opportunity for stakeholders who can navigate the technical and logistical complexities involved.
Worldwide Medium Entropy Alloys Market
Segmentation and Demand Drivers
Understanding where demand originates is crucial for resource allocation. The market is naturally stratified by composition type, application sector, and geographic presence. While public high-level summaries provide a directional view, the detailed breakdown of these segments reveals specific pockets of intensity that drive overall market health.
- Alloy Composition Types: The landscape includes Cr-Co-Ni-based formulations, Fe-Cr-Ni-based systems, and other elemental compositions. Each type offers distinct mechanical properties and corrosion resistance profiles, catering to specific engineering requirements. The dominance of certain compositions often correlates with the maturity of processing technologies and the availability of upstream feedstocks.
- Application Verticals: Demand is heavily influenced by sectors requiring materials that perform under stress and heat. Aerospace and defense remain primary drivers, leveraging these alloys for structural components and engine parts. Automotive and transportation sectors are increasingly exploring these materials for lightweighting and durability. Energy and power generation applications utilize them for turbine blades and heat exchangers, while other industries adopt them for specialized tooling and medical devices.
- Regional Distribution: Consumption patterns vary significantly by region, influenced by local industrial bases, defense spending, and manufacturing capabilities. North America and Europe have historically held significant shares due to established aerospace and specialty metals industries. Meanwhile, Asia Pacific represents a dynamic growth zone, driven by manufacturing expansion and infrastructure development. Latin America and the Middle East and Africa contribute to the global mix, often tied to specific energy extraction and processing projects.
It is important to note that while these categories define the market structure, the specific revenue contributions and growth rates within each segment are subject to rapid change based on technological breakthroughs and supply chain constraints. Detailed segmentation data is contained within the full research report to ensure strategic accuracy.
Competitive Landscape and Key Players
The market is characterized by a mix of established specialty materials giants and agile innovators focused on computational design and additive manufacturing. The concentration of market share among top players indicates a competitive environment where differentiation is key.
Major Incumbents: Several large corporations hold significant positions in the supply chain. Carpenter Technology Corporation and ATI Inc. are prominent in the USA, offering advanced high-performance alloys for aerospace and energy sectors. Haynes International, Inc. specializes in nickel- and cobalt-based alloys, extending capabilities into medium entropy formulations for demanding environments. Sandvik AB, based in Sweden, develops advanced materials for aerospace and automotive sectors. VDM Metals GmbH in Germany manufactures nickel alloys and specialty materials applicable to these technologies.
Innovation and Supply Chain Enablers: Beyond traditional manufacturers, a layer of companies focuses on specific enabling technologies. QuesTek Innovations LLC emphasizes computational alloy design, accelerating development cycles. Hitachi Metals (Proterial Ltd.) in Japan produces specialty alloys for electronics and automotive uses. Additionally, suppliers like Matexcel, MSE Supplies, and Stanford Advanced Materials (SAM) play critical roles in providing alloy powders and machined products tailored for additive manufacturing and 3D printing, supporting the research and prototyping phases that precede mass production.
The competitive dynamic is not just about volume but about technical capability, intellectual property, and the ability to secure raw materials. Market concentration metrics suggest that a handful of players control a significant portion of the revenue, creating barriers to entry for new competitors while fostering partnerships between established firms and specialized innovators.
Strategic Risks and Industry Dynamics
While the growth outlook is positive, several structural factors introduce volatility and compliance costs that must be managed. Strategic planning requires a clear view of these external pressures.
- Raw Material Volatility: Production relies on upstream feedstocks such as nickel, cobalt, chromium, and titanium. Price volatility in these elements directly impacts alloy manufacturing costs. Fluctuations in commodity markets can erode margins or delay project timelines if hedging strategies are not in place.
- Geopolitical Supply Chain Risks: Sourcing of alloying elements like cobalt and nickel faces supply chain risks due to concentrated production in specific geographic regions. Geopolitical factors can disrupt flow, creating urgency for diversification of sourcing strategies and inventory buffering.
- Regulatory and Compliance Costs: Environmental regulations and material safety standards increase compliance costs for manufacturers. Processing and sourcing of critical elements are subject to stricter scrutiny, requiring investments in safer processing technologies and documentation.
- Sustainability Initiatives: There is a growing emphasis on reducing the carbon footprint of material production. The use of recycled stainless steel scrap and nickel alloy scrap reduces CO2 emissions compared to primary production in multicomponent alloy manufacturing. Companies integrating recycled feedstocks may gain competitive advantages in markets with strict sustainability mandates.
Operational Imperatives for 2026
As the market moves into the 2026 forecast period, several operational priorities emerge for industry participants.
1. Supply Chain Diversification: Given the geopolitical risks associated with critical elements, companies are advised to map their supply chains extensively. Relying on single-source suppliers for cobalt or nickel increases vulnerability. Strategic partnerships with multiple suppliers across different regions can mitigate disruption risks.
2. Investment in Additive Manufacturing: The availability of high-quality alloy powders from suppliers like Matexcel and MSE Supplies indicates a shift towards additive manufacturing. Industries should evaluate how medium entropy alloy powders can be integrated into 3D printing workflows to reduce waste and enable complex geometries that traditional machining cannot achieve.
3. Technology Adoption and R&D: Computational alloy design, as pioneered by firms like QuesTek, offers a pathway to faster development. Investing in digital tools that predict material properties can reduce the time-to-market for new alloy formulations. Collaboration between material scientists and computational experts is becoming a standard best practice.
4. Sustainability as a Competitive Edge: With compliance costs rising, leveraging recycled feedstocks where feasible can lower both environmental impact and potentially material costs. Demonstrating a commitment to sustainable practices can also enhance brand value among downstream customers in the automotive and aerospace sectors who have their own net-zero targets.
Conclusion: The Value of Deep Intelligence
The Worldwide Medium Entropy Alloys Market presents a landscape of significant opportunity tempered by complex operational challenges. The growth trajectory is strong, driven by essential demand from aerospace, defense, and energy sectors. However, realizing the potential of this market requires more than just observing top-line revenue figures. It demands a granular understanding of segmentation, competitive positioning, raw material dynamics, and regulatory shifts.
High-level data points, while useful for initial orientation, cannot capture the nuances required for precise strategic planning. Decisions regarding capacity expansion, M&A targets, or R&D focus require detailed segmentation data, region-specific forecasts, and deep dives into competitor strategies. The interplay between alloy compositions, application needs, and regional supply chains creates a matrix of variables that must be analyzed holistically.
Our full market research report provides this necessary depth. It moves beyond the macro overview to deliver actionable intelligence on market sizes, growth rates by segment, competitive share analysis, and strategic recommendations tailored to specific business objectives. For leaders preparing for the 2026-2032 horizon, accessing this granular intelligence is the critical next step in converting market potential into sustainable competitive advantage.
Shape Memory Alloys Market
For detailed analysis of this topic, please visit the official page: Worldwide Medium Entropy Alloys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com