

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Umbilical Cable Market Hits $4.19B in 2025, Projected 7.1% CAGR to 2032

Global Umbilical Cable Market 2026: Strategic Intelligence for Navigating Deepwater Expansion and Energy Transition
The subsea umbilical cable sector stands at a critical inflection point in 2026, driven by aggressive deepwater exploration, evolving flow assurance requirements, and parallel investments in offshore renewable infrastructure. As operators push development boundaries into ultra-deepwater frontiers and marginal fields require increasingly complex intervention systems, the umbilical value chain has transitioned from a commoditized supply segment to a highly engineered, performance-critical enabler of hydrocarbon and energy transition projects. PW Consulting newly released Worldwide Umbilical Cable Market research provides decision-makers with a structured, forward-looking intelligence framework designed specifically to support capital allocation, procurement strategy, and competitive positioning across the 2026 to 2032 horizon.
Worldwide Umbilical Cable Market
Subsea Umbilical Service Market
This strategic overview synthesizes historical performance, macroeconomic tailwinds, and the operational realities shaping global supply while deliberately reserving sector-specific quantification, regional breakdowns, and granular application analyses for the complete intelligence package. Enterprise leaders seeking to calibrate bidding strategies, evaluate supplier partnerships, and anticipate capacity constraints will find the full study structured to convert raw market signals into executable commercial roadmaps.
From Recovery to Sustained Growth: Mapping the Trajectory Through 2032
Historical data from 2020 through 2025 reveals a market that absorbed significant cyclical volatility before consolidating into a robust expansion phase. After navigating pandemic-era project deferrals, supply chain bottlenecks, and fluctuating crude price environments, the global umbilical cable market demonstrated notable resilience and rebounded with accelerated contract awards, renewed operator capex commitments, and expanded manufacturing throughput. By the base year of 2025, market revenue had firmly reestablished its growth trajectory, reflecting both the completion of previously delayed subsea projects and the early-stage awarding of next-generation deepwater and tie-back developments.
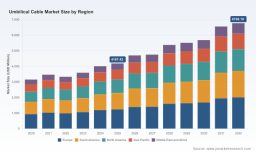
Forecasts extending through 2032 indicate that this momentum will not merely continue but structurally compound. The research models a compound annual growth rate of 7.1 percent across the entire global umbilical cable market, a trajectory that reflects sustained operator demand for high-specification umbilical systems capable of supporting longer tie-backs, higher pressure and temperature environments, and integrated power-communication-hydraulic architectures. Market size progression across the forecast window underscores an expanding addressable base as project complexity outpaces simple volume growth. Decision-makers evaluating this growth must recognize that it is not uniformly distributed across product categories, depth regimes, or geographies; rather, it is heavily concentrated in segments demanding advanced material science, rigorous testing protocols, and specialized installation expertise.
At the macroeconomic level, the market's absolute revenue scale signals a mature yet dynamically evolving industry where incremental innovation and strategic capacity investments directly influence competitive outcomes. The research dissects these growth vectors by isolating the underlying demand generators — from basin-level exploration patterns to utility-scale offshore energy deployments — without oversimplifying the nuanced factors that will determine which suppliers capture disproportionate value over the next seven years.
Segmentation Dynamics: Where Complexity Drives Commercial Differentiation
Umbilical cable markets do not move as monoliths. Performance requirements, regulatory environments, and operator preferences fracture demand across material architectures, operational depth classifications, and end-use applications, each carrying distinct engineering tolerances and commercial implications. The steel tube umbilical segment continues to anchor a substantial portion of market value, driven by its unmatched mechanical integrity, corrosion resistance, and suitability for high-pressure injection, chemical delivery, and long-life production systems in harsh subsea conditions. Complementary architectures, including thermoplastic hose umbilicals and specialized power umbilicals, serve distinct operational niches where flexibility, weight optimization, and electrical transmission requirements dictate design choices.
Depth classification further stratifies demand. Shallow water deployments, deepwater developments, and ultra-deepwater frontiers each impose fundamentally different stress profiles, installation methodologies, and lifecycle maintenance considerations. As operators increasingly target extended-reach tie-backs and frontier basins where flow assurance, thermal regulation, and reliable communication become non-negotiable, the commercial premium shifts toward suppliers capable of engineering integrated systems that address wax and hydrate mitigation, high-voltage power delivery, and fiber-optic telemetry within a single deployment architecture.
Application-side dynamics reveal parallel growth engines beyond traditional oil and gas production. Subsea intervention, ROV support, diving operations, seismic monitoring, defense applications, and expanding renewable energy arrays all require customized umbilical solutions tailored to dynamic loading, environmental exposure, and mission-critical reliability standards. The research maps these application intersections to identify which operational profiles are expanding fastest, where dual-use technologies are bridging subsea oil and gas with offshore wind and green hydrogen infrastructure, and how suppliers can repurpose engineering capabilities across adjacent markets without compromising specification integrity.
Competitive Architecture: Incumbents, Specialists, and Emerging Capacity Centers
The global umbilical cable competitive landscape reflects a hybrid structure: established multinational operators with integrated design, manufacturing, and subsea service capabilities coexist alongside specialized manufacturers and regional capacity hubs that concentrate on high-specification components, bespoke system integration, or localized project execution. Industry concentration metrics underscore the strategic importance of scale, certification depth, and proven project track records. The research details how leading suppliers leverage proprietary designs, dedicated manufacturing plants, and in-house testing infrastructure to maintain performance leadership, while mid-tier and regional players pursue differentiation through niche engineering expertise, rapid customization, and full-lifecycle support models.
Profiles of core market participants illustrate the breadth of strategic postures shaping 2026 competition:
- Global technology-driven subsea solution providers anchor the upper tier through integrated steel tube, thermoplastic hose, and hybrid umbilical engineering, supported by multi-continent manufacturing footprints and deep project delivery experience across oil and gas basins.
- Specialized subsea contractors and cable system manufacturers emphasize complete umbilical architectures for deepwater and harsh environments, combining power, control, and communication distribution with extensive installation support capabilities and expanding portfolios that address renewable energy array and export cable requirements.
- Integrated subsea technology units within larger industrial portfolios focus on robust umbilical systems for ultra-deep water, pairing patented mechanical and electrical designs with integrated production control, chemical injection, and flow assurance functionality tailored to extreme depth and pressure conditions.
- Long-tenured subsea cable specialists with decades of offshore project experience concentrate on high-pressure, high-temperature, long tie-back applications, frequently aligning with national oil company agendas and major operator specifications where proven reliability and regional project familiarity drive contract selection.
- Global suppliers of subsea control umbilicals, power cables, and hybrid systems provide end-to-end design, manufacture, testing, and offshore installation services, with recent project activity spanning Middle East gas infrastructure, offshore platform cable testing, and deployment monitoring support.
- Bespoke static and dynamic umbilical specialists deliver customized cable, hose, and termination solutions for demanding subsea environments, maintaining in-house design, testing, and project management capabilities that emphasize mission-specific performance under dynamic loading and corrosive conditions.
- Complex custom cable and specialty umbilical manufacturers serve subsea oil and gas, diving, ROV, seismic, defense, and renewable applications, emphasizing engineered flexibility for dynamic harsh environments and integrated system delivery.
- Global manufacturers meeting stringent industrial and subsea design criteria contribute specialized umbilical cable production capacity, reinforcing supply diversification for complex specification requirements.
- Composite subsea umbilical cable producers operating across UK and Brazilian manufacturing partnerships deliver electro-hydraulic, injection, optical, and power umbilicals engineered for offshore oil and gas deployments to significant depths, reflecting the strategic importance of regional production synergies.
- Asian cable manufacturers expand marine oil and gas exploration cable portfolios, including umbilical, optical, electrical, and composite cable solutions, positioning themselves along the supply chain for growing subsea project volumes.
- Submarine cable enterprises engaged in R and D, design, and production for marine resource development increasingly intersect with umbilical cable manufacturing as offshore energy and resource extraction projects expand their subsea interface requirements.
- Specialty stainless steel tube suppliers occupy a critical upstream position in the steel tube umbilical value chain, delivering seamless tubing that directly influences tensile strength, corrosion resistance, and deepwater performance for high-specification umbilical assemblies.
Recent operational developments reinforce how individual supplier activities translate into broader market signals. Tubacex's early 2026 securing of three new umbilical tube contracts aggregating to a combined €26 million across the Gulf of Mexico, Brazil, Mediterranean, Australia, and Africa illustrates sustained demand for specialized stainless steel tubing and record offshore segment order books. JDR Cable Systems' 2025 contract award to test 14 umbilical cables for offshore platforms in the Middle East, encompassing pre-deployment testing, lay operation monitoring, and integration support, highlights the growing commercial weight of quality assurance, lifecycle testing, and integration services alongside physical manufacturing. Meanwhile, the 2025 Umbilicals Conference convened by the Umbilical Manufacturers' Federation and Global Underwater Hub brought manufacturers, designers, installers, and operators together to align on subsea umbilical advancements, signaling continued industry-wide focus on standardization, technological progression, and cross-value-chain collaboration.
Technology, Materials, and Regulatory Forces Reshaping Procurement Decisions
Subsea umbilical systems perform indispensable functions that extend far beyond simple fluid or power transport. Modern architectures integrate hydraulic and chemical injection capabilities, electrical power delivery, fiber-optic communication pathways, and active flow assurance mechanisms including heating solutions that prevent wax and hydrate formation in ultra-deepwater developments. As fields extend in distance, depth, and operating temperature, umbilical design assumptions must accommodate longer deployment lengths, higher pressure containment thresholds, greater dynamic movement exposure, and increased reliability expectations over extended production lifecycles.
Raw material engineering directly shapes competitive differentiation. Stainless steel and super duplex tubes remain foundational components for steel tube umbilicals, providing the high tensile strength and corrosion resistance required for deepwater and high-pressure applications. Supplier capability in seamless tube production, metallurgical quality control, and precision manufacturing determines whether system designers can meet increasingly aggressive performance specifications without compromising manufacturability or cost structures. The sustained demand for these specialized materials, as evidenced by recent contract awards and elevated order book levels, confirms that material-grade capabilities are becoming decisive competitive differentiators rather than routine commodity inputs.
Regulatory and quality assurance expectations further intensify as installation and long-term operation in harsh subsea environments demand strict compliance with offshore safety, performance, and certification standards. Procurement teams increasingly evaluate not only initial unit economics but also testing rigor, deployment monitoring support, warranty structures, and the supplier's demonstrated capacity to sustain performance across the full project lifecycle. Industry investments in R and D facilities and expanded manufacturing capacity for longer, higher-specification umbilicals indicate that competitive positioning will increasingly hinge on engineering depth, testing infrastructure, and the ability to deliver integrated solutions that satisfy both operator technical requirements and regulatory compliance mandates.
Strategic Utility: Translating Market Intelligence into 2026 Decision Advantage
For corporate strategy teams, procurement leaders, and investment analysts, the Worldwide Umbilical Cable Market research delivers an operational intelligence architecture designed to convert market complexity into structured decision support. The study integrates historical performance analysis, forward-looking growth modeling, segmentation mapping, competitive profiling, and material and technology trend assessment into a unified analytical framework that directly informs bidding strategy, supplier selection, partnership evaluation, and capacity planning.
Rather than presenting static market snapshots, the research prioritizes actionable segmentation logic and comparative supplier positioning so that readers can identify where value is concentrating, which technical capabilities are becoming table stakes, and how regional manufacturing footprints intersect with project geography and operator preference. By aligning macroeconomic growth indicators with granular supply-side dynamics, the report equips enterprises to anticipate shifts in bidding intensity, assess where specialized testing and integration services add negotiating leverage, and evaluate which competitors are most likely to secure advantage in high-specification deepwater and ultra-deepwater assignments.
The analysis is deliberately designed to support scenario-based planning. Readers can use the segmentation structures to stress-test exposure across product categories and depth regimes, evaluate supplier concentration risk against procurement requirements, and align internal engineering roadmaps with the market's accelerating demand for integrated power, control, chemical injection, and flow assurance solutions. For organizations assessing market entry, capacity expansion, or partnership opportunities, the report provides the contextual scaffolding necessary to evaluate fit without overcommitting to unsubstantiated assumptions about regional or application-specific value distribution.
A complete review of the 2026 to 2032 forecast architecture, segmentation splits, competitive positioning matrices, and detailed regional and application-level intelligence is available through the full publication. The research has been structured to ensure that each section translates directly into decision-ready insight, enabling executive teams, sales leadership, and strategic planning functions to move from observation to execution with confidence. For those responsible for navigating subsea capital programs, supplier negotiations, and long-term portfolio strategy, the complete Worldwide Umbilical Cable Market study offers the structured intelligence needed to act decisively in a market where performance, reliability, and engineering differentiation increasingly define commercial winners.
For detailed analysis of this topic, please visit the official page: Worldwide Umbilical Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com