

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Narrow Body Aircraft MRO Market to Hit $55.24B in 2025, CAGR 5.6% Through 2032

Navigating the Narrow-Body MRO Landscape: Strategic Intelligence for 2026 and Beyond
The global maintenance, repair, and overhaul (MRO) sector for narrow-body aircraft is entering a decisive phase. As airlines accelerate fleet renewals and optimize legacy operations, the narrow-body segment has emerged as the primary engine of MRO revenue growth. PW Consulting is pleased to introduce our Worldwide Narrow Body Aircraft MRO Market report, a comprehensive strategic resource designed to equip executives, investors, and MRO operators with the forward-looking intelligence required to navigate the 2026–2032 forecast period. This publication moves beyond headline figures to deliver an operational blueprint for capacity planning, competitive positioning, and risk mitigation in one of aviation’s most dynamic segments.
The market has demonstrated remarkable resilience and expansion over the past half-decade. Valued at approximately 32,450 million USD in the base year of 2020, the sector climbed steadily through the post-pandemic recovery, reaching an estimated 55,241 million USD by 2025. The trajectory forward underscores sustained momentum, with the market projected to expand at a compound annual growth rate of 5.6 percent. By 2032, the narrow-body MRO market is expected to surpass 80,893 million USD. These figures reflect deeper structural shifts: the replacement of aging fleets with fuel-efficient narrow-body platforms, the compounding effect of recurring maintenance cycles, and the increasing complexity of engine and component overhauls. Our report translates these macro-level indicators into actionable scenarios, enabling decision-makers to align capital allocation, facility investments, and service portfolio strategies with measurable market realities.
Decoding the Competitive Architecture
The narrow-body MRO landscape is characterized by a mix of integrated airline-affiliated shops, globally scaled independent providers, and highly specialized regional players. Our analysis maps the strategic positioning of leading enterprises that are actively shaping capacity, certification pathways, and service breadth across key operating theaters. Lufthansa Technik continues to leverage its multi-facility network across Europe, delivering base and line maintenance alongside engine overhaul capabilities for both CFM56 and LEAP powerplants across the Airbus A320 family and Boeing 737 series. ST Engineering Aerospace maintains its status as the world’s largest independent airframe MRO provider by man-hours, offering nose-to-tail services with a particularly strong footprint in the Asia-Pacific region and expanding capabilities in the United States and Europe. AAR Corp. reinforces its leadership in North America through dedicated narrow-body facilities and recent capacity expansions in Oklahoma City and Miami, focusing on airframe, component repair, and landing gear overhaul for 737 and A320 platforms.
Worldwide Narrow Body Aircraft MRO Market
Airline-affiliated models remain highly influential. Delta TechOps has established a differentiated position in North America by securing full licensed overhaul capability for both CFM LEAP-1A and LEAP-1B engines, complemented by extensive hangar capacity tailored to narrow-body fleets. SR Technics concentrates on engine heavy shop visits and component MRO, supported by long-term maintenance agreements that underscore the enduring demand for CFM56-7B services among Boeing 737NG operators. In Asia, HAECO delivers integrated airframe, line, and component support for narrow-body platforms, including dedicated operations for the A321neo and regional joint ventures optimized for short-haul networks. Turkish Technic has scaled its throughput significantly through large multi-hangar facilities capable of servicing up to 26 narrow-body aircraft simultaneously, while Iberia Maintenance and TAP Maintenance & Engineering anchor European capacity with specialized engine overhaul programs covering V2500 and GTF architectures alongside component and airframe services.
Recent operational milestones from these organizations illustrate how strategic execution is translating into market advantage. In early 2026, SR Technics formalized a multi-year agreement with a major North American carrier for CFM56-7B heavy shop visit maintenance, reinforcing the persistent demand for legacy engine support. During the same period, Delta TechOps achieved full licensed overhaul qualification for both LEAP-1A and LEAP-1B engines, positioning the provider as the sole North American airline-affiliated MRO with this dual-certification capability. The broader ecosystem has also seen substantial commitments: a memorandum of understanding between Ryanair and CFM International outlines long-term material services covering roughly 2,000 CFM56 and LEAP engines across the carrier’s Boeing 737 fleet. Meanwhile, facility expansions continue to reshape regional capacity. ST Engineering opened a new engine MRO facility in Singapore designed to double throughput for CFM56 and LEAP maintenance, targeting more than 300 annual shop visits by 2027. HAECO commenced line maintenance support for Cathay Pacific’s A321neo operations at Hong Kong International Airport, establishing the carrier as its largest narrow-body customer by flight volume. These developments are not isolated events; they signal a coordinated push toward higher certification coverage, geographic diversification, and specialized engine service readiness.
Core Structural Dynamics Shaping Service Delivery
Several interlocking forces are redefining how narrow-body MRO services are priced, scheduled, and delivered. Fleet composition remains the foundational driver. Narrow-body aircraft dominate global civil MRO demand because of their extensive deployment on short-haul and high-frequency routes, generating predictable but intensifying maintenance cycles across the Airbus A320 and Boeing 737 families. As operators pursue fuel efficiency and range improvements, next-generation platforms are entering service while mature and regional narrow-body fleets continue to require ongoing support. This dual pressure expands the service envelope and complicates shop scheduling, particularly when heavy maintenance intervals converge with engine performance restoration requirements.
Regulatory and certification requirements add a further layer of complexity. The CFM International LEAP engine family, which powers both the A320neo and 737 MAX, relies on specialized Premier MRO licensing and structured performance restoration shop visits. Providers are actively expanding certified capabilities to match fleet growth, and the competitive advantage increasingly belongs to organizations that can demonstrate full-scope authorization, disciplined quality management, and rapid turnaround on high-demand powerplants. Simultaneously, supply chain bottlenecks persist. Parts availability constraints and production delays for both aircraft and engines have extended MRO turnaround times and elevated costs across the industry. These disruptions are not merely operational inconveniences; they influence slot utilization, revenue forecasting, and the economics of outsourcing versus in-sourcing maintenance activities.
Cost dynamics remain a central concern for operators and MRO providers alike. The sector continues to face persistent shortages of certified mechanics, which have contributed to wage inflation of approximately 6.6 percent in 2024 with projections near 5.7 percent for 2025. These labor pressures directly affect turnaround times and the cost base of narrow-body maintenance programs. Material costs have followed a similar trajectory, rising by an average of 7.7 percent in 2024, exceeding earlier expectations of 6.5 percent, with 2025 projections estimated around 6.3 percent. The combination of skilled labor scarcity and elevated input prices is reshaping margin structures and compelling providers to invest in productivity improvements, digital scheduling tools, and more resilient supplier networks. Our report isolates these pressures, analyzes their differential impact across MRO activity lines, and identifies operational levers that can protect margins without compromising service quality.
What the Report Delivers: A Practical Intelligence Framework
This study is structured to support immediate and medium-term decision-making across multiple functional domains. Rather than offering a static snapshot, the report provides a layered analytical environment that integrates historical performance trends, forward-looking demand drivers, and competitive benchmarking into a coherent framework. Readers will gain access to detailed assessments of MRO activity segmentation, aircraft generation mix, and regional service distribution, all contextualized within the broader operational realities of fleet turnover, regulatory certification, and supply chain resilience.
- Comprehensive market sizing and growth trajectory analysis spanning historical baseline data and a multi-year forecast, enabling scenario planning for capacity expansion, pricing strategy, and service portfolio optimization.
- Granular segmentation analysis across MRO activity categories—including engine maintenance, airframe maintenance, component maintenance, and line maintenance—showing how revenue concentration shifts as maintenance cycles, engine shop visit frequencies, and component replacement patterns evolve.
- Aircraft generation segmentation that distinguishes between current-generation platforms, next-generation narrow-body introductions, and mature or regional narrow-body fleets, helping operators anticipate differing maintenance intensities and lifecycle service requirements.
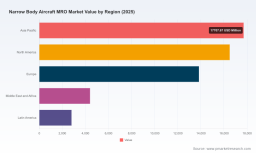
- Regional distribution insights that map where maintenance demand is concentrated, how provider networks are scaling to capture share, and which geographic markets present the most favorable operational economics for base, line, and component services.
- Competitive landscape profiling that combines company headquarters, service scope, facility footprints, and recent capability expansions into a comparative view of market positioning and strategic direction.
- Structural dynamics assessment covering labor cost inflation, material cost trends, certification requirements, and supply chain pressures, with implications for turnaround times, margin management, and long-term sourcing strategies.
- Recent developments tracking that integrates contract awards, facility openings, capability certifications, and long-term service agreements to highlight the pace and direction of market activity.
The report also examines market concentration characteristics to clarify how competitive share is distributed among leading providers and what this implies for pricing power, partnership opportunities, and barriers to entry. By connecting these structural insights with real-world developments—such as dual LEAP engine certification achievements, multi-year heavy shop visit agreements, and targeted capacity expansions—the study helps readers distinguish temporary disruptions from durable market shifts. Each section is designed to be referenced independently or read as a continuous narrative, depending on whether the priority is market entry evaluation, outsourcing strategy refinement, capacity planning, or investment due diligence.
Strategic Imperatives for 2026 Decision-Makers
For executives operating in or adjacent to the narrow-body MRO ecosystem, the 2026 outlook demands a disciplined balance between growth ambition and operational realism. The projected mid-single-digit compound annual growth rate signals sustained demand, but the underlying composition of that demand is shifting. Engine maintenance remains the largest activity category, reflecting the durability requirements of modern narrow-body powerplants and the extended service life of in-service fleets. Airframe and component maintenance continue to represent substantial revenue streams, while line maintenance supports the high-frequency operational tempo that defines short-haul networks. Providers that align facility throughput, certification coverage, and spare parts logistics with these activity-specific demand patterns will be better positioned to capture share without overextending capital.
Geographic diversification is equally important. The regional distribution of narrow-body MRO demand highlights where operator networks are densest, where fleet renewal activity is most active, and where provider competition is intensifying. Airlines and independent MRO organizations alike must evaluate whether existing footprints can absorb incoming maintenance volume, whether partnership or joint-venture structures can accelerate market access, and whether localized sourcing strategies can mitigate the cost and delay implications of extended supply chains. The concentration of competitive activity among a core group of established providers suggests that differentiation will increasingly depend on certification breadth, turnaround reliability, and the ability to manage labor and material cost pressures without eroding service standards.
Operational resilience will separate sustainable performers from those that merely capture short-term volume. Skilled labor availability, wage trends, and the cost of components and raw materials are not isolated line items; they are systemic variables that influence scheduling confidence, contract profitability, and customer retention. Organizations that invest in workforce development, digital maintenance planning, and supplier diversification can convert these challenges into competitive advantages. Similarly, providers that anticipate the next wave of engine shop visit demand—especially for LEAP platforms and high-utilization CFM56 fleets—can secure long-term service agreements and optimize hangar utilization ahead of tighter capacity windows.
Aircraft Engine MRO Market
The strategic questions facing the market are clear. Which regional markets offer the most favorable balance of demand growth and operational cost? How should organizations sequence facility investments to match forecast maintenance cycles without creating idle capacity? What certification pathways are becoming essential as engine architectures and regulatory expectations evolve? How can operators and providers structure partnerships that balance risk, share capability, and improve responsiveness to supply chain volatility? The Worldwide Narrow Body Aircraft MRO Market report is built to answer these questions with precision, drawing on rigorous market sizing, segmentation analysis, competitive profiling, and forward-looking scenario modeling.
Accessing the Full Intelligence Package
This article provides a strategic preview of the market environment and the analytical depth contained within our latest study. The complete report expands on every dimension introduced here, delivering the detailed segmentation data, regional breakdowns, activity-level revenue distributions, aircraft-generation analyses, and competitive benchmarking required for confident decision-making. We invite airline executives, MRO operators, investors, and aerospace supply chain leaders to access the full publication for comprehensive market intelligence, scenario-based forecasts, and operational recommendations tailored to the narrow-body segment. As the 2026–2032 cycle unfolds, those who align strategy with granular, validated market insight will be best equipped to capture durable value in a market defined by both opportunity and complexity.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com