

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bitterness Suppressor Market Hits $650M in 2025, 5.8% CAGR to 2032

Navigating the Next Wave of Taste Engineering: Strategic Insights into the Worldwide Bitterness Suppressor and Flavor Carrier Market
The global taste modulation landscape is undergoing a structural transformation. As formulators confront increasingly complex consumer expectations around clean labels, functional benefits, and sensory precision, bitterness suppressors and flavor carriers have evolved from niche ingredients into mission-critical enablers of modern product architecture. PW Consulting’s newly released Worldwide Bitterness Suppressor and Flavor Carrier Market research delivers a comprehensive, decision-ready intelligence framework designed to help technology leaders, procurement directors, and R&D strategists navigate the 2026–2032 horizon with precision. This overview outlines the strategic architecture of the study, the competitive forces shaping the sector, and the regulatory and supply chain currents that will dictate margin trajectories and innovation roadmaps in the coming years.
For enterprises operating at the intersection of food science, pharmaceuticals, and nutraceuticals, the ability to mask undesirable off-notes while delivering consistent flavor release has become a non-negotiable competitive differentiator. Plant-based proteins, functional botanicals, and next-generation oral care formulations all share a common developmental bottleneck: bitterness. The market’s underlying economics reflect this reality. Between 2020 and 2025, the global sector expanded from approximately 485.45 million USD to 650.0 million USD, demonstrating consistent year-over-year compounding even as raw material volatility and regulatory scrutiny tested supply chain resilience. Looking ahead, the forecast period from 2026 through 2032 positions the market to reach roughly 964.54 million USD, anchored by a projected compound annual growth rate of 5.8 percent. These headline figures represent more than aggregate demand; they encapsulate a fundamental shift in how ingredient suppliers, brand owners, and contract manufacturers allocate R&D budgets, structure formulation partnerships, and prioritize clean-label compatibility.
What separates a superficial market scan from an actionable strategic asset is the granularity with which a study maps technology adoption cycles, regional procurement behaviors, and application-specific formulation constraints. The PW Consulting analysis goes beyond top-line valuation to map the operational realities driving procurement and product development decisions. The research dissects the competitive ecosystem across multiple strategic dimensions, providing a structured lens through which to evaluate supplier capabilities, partnership viability, and white-space innovation opportunities. Readers will find a detailed mapping of the prevailing concentration dynamics, where a tightly clustered group of multinational flavor and ingredient specialists commands a disproportionate share of advanced encapsulation and bitterness-masking IP. The report evaluates how these leaders are leveraging proprietary delivery systems, emulsification platforms, and molecular masking technologies to maintain pricing power while responding to regulatory and consumer pressure for natural, label-friendly solutions.
Worldwide Bitterness Suppressor and Flavor Carrier Market
Competitive Architecture and Innovation Cadence
The bitterness suppressor and flavor carrier ecosystem is defined by a small number of well-capitalized players that have invested heavily in encapsulation science, sensory modulation, and application engineering. Givaudan has continuously expanded its portfolio with technologies such as Simplesse and Encapsia, positioning itself as a preferred partner for food and beverage brands seeking clean-label compatibility and consistent sensory performance. International Flavors & Fragrances has reinforced its standing through systems like Wittamine and advanced flavor encapsulation architectures, addressing off-note challenges across beverage matrices and oral care applications. DSM-Firmenich has leaned into encapsulation-driven flavor carriers and bitterness-reduction platforms tailored for dairy, beverage, and nutraceutical use cases, while Kerry Group supplies Taste-Tune masking solutions alongside emulsion-based carriers designed for both savory and sweet application environments. Sensient Technologies and Symrise round out the competitive core, with Sensient focusing on encapsulated flavors and bitterness inhibitors for beverages, confectionery, and pharmaceutical formats, and Symrise deploying SymGlobe encapsulation and SymMask suppressor technologies within functional food pipelines.
Recent commercial activity underscores the pace of innovation and the strategic stakes involved. In October 2024, DSM-Firmenich introduced HumiSeal flavor carrier technology, engineered to enhance bitterness masking specifically within plant-based beverage formulations. By June 2024, IFF had secured Clean Label Project certification for its next-generation bitterness suppressors in natural flavors, signaling a deliberate push toward recognized clean-label credibility. Earlier in the year, Givaudan launched Naturemuls flavor carrier emulsions aligned with EU clean-label regulations, demonstrating how regulatory foresight is being baked directly into product development cycles. These milestones are not isolated product launches; they represent coordinated moves to capture formulation share in segments where sensory performance, regulatory compliance, and label transparency must coexist.
Food Flavor Enhancer Market
Formulation, Regulatory, and Supply Chain Dynamics
Any forward-looking market strategy must account for the intersecting forces that shape ingredient availability, formulation feasibility, and compliance risk. The 2025–2032 forecast environment is heavily influenced by raw material economics, evolving regulatory thresholds, and trade policy shifts. Cyclodextrin pricing experienced a 12 percent increase during the fourth quarter of 2024, driven by corn starch supply constraints in North America. This single input movement illustrates how agricultural feedstock volatility can cascade directly into encapsulation cost structures and formulation economics. On the regulatory front, EU Regulation 2024/1270 has introduced explicit restrictions on synthetic bitterness suppressors in infant formula, mandating a transition toward natural alternatives and forcing reformulation timelines across a highly sensitive application segment. Simultaneously, the US International Trade Commission imposed a 25 percent tariff on imported flavor encapsulation agents from China under Section 301, effective September 2024, altering cost assumptions for manufacturers reliant on cross-border sourcing of encapsulation inputs. In parallel, California Proposition 65 continues to require warning labels for products containing certain synthetic flavor carriers above 0.1 ppm, a compliance consideration that has become embedded in product marketing, packaging, and risk-assessment workflows.
These dynamics do not operate in isolation. They interact to create a complex decision environment where procurement strategies, supplier diversification, and formulation architecture must be aligned with both near-term margin protection and long-term regulatory trajectory. The PW Consulting study maps these interactions explicitly, enabling teams to anticipate cost pressure points, evaluate the strategic value of regional sourcing flexibility, and prioritize ingredient development partnerships that reduce exposure to single-point supply failures or compliance bottlenecks.
Strategic Utility for the 2026 Decision Cycle
The real value of this market research lies in its capacity to convert market information into executable strategy. For R&D leadership, the report provides a structured framework to evaluate which masking and carrier technologies align with target application constraints, clean-label mandates, and shelf-stability requirements. For commercial and procurement teams, it offers a comparative view of supplier positioning, recent innovation milestones, and concentration dynamics that inform sourcing strategy, negotiation leverage, and partnership evaluation. For corporate strategy and investment functions, the analysis highlights where formulation demand is likely to intensify, which regulatory shifts will reshape competitive barriers, and how regional procurement patterns may evolve as trade policy and raw material volatility continue to reshape cost structures.
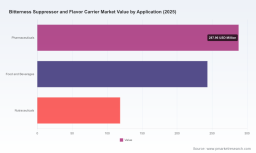
The segmentation logic embedded in the study enables decision-makers to isolate performance drivers by type, application, and region without relying on blunt aggregate assumptions. Modified starches, cyclodextrins, maltodextrins, and other carrier categories each carry distinct sensory profiles, compatibility constraints, regulatory footprints, and cost curves. Similarly, the distribution of demand across pharmaceuticals, food and beverages, and nutraceuticals reflects different formulation priorities, approval pathways, and consumer-facing expectations. Regional procurement environments further complicate the picture, as trade policy, supplier density, and regulatory regimes interact to produce divergent cost and compliance landscapes. The report’s architecture is designed to help teams navigate these layers with discipline, identifying where to concentrate formulation investment, how to structure supplier relationships, and which innovation timelines warrant accelerated development resources.
What the Full Study Delivers
- A complete 2020–2032 market sizing trajectory with explicit base-year anchoring, historical validation, and forecast mechanics designed for board-level planning and internal budgeting cycles
- A detailed segmentation analysis across type, application, and regional dimensions, structured to support product portfolio planning, go-to-market prioritization, and supply chain scenario modeling without oversimplifying cross-segment dependencies
- A competitive landscape evaluation that examines market concentration, core company capabilities, technology positioning, and recent strategic developments to inform supplier selection, partnership strategy, and white-space identification
- An integrated dynamics assessment covering raw material economics, regulatory interventions, tariff implications, and environmental labeling requirements, with direct relevance to formulation risk management and procurement diversification
- Strategic recommendations and scenario pathways that translate market signals into actionable guidance for innovation roadmaps, cost structure optimization, and market-entry or market-expansion planning
The Worldwide Bitterness Suppressor and Flavor Carrier Market report is built for leaders who need more than directional signals. It is designed to support concrete decisions in a market where sensory performance, regulatory compliance, and supply chain resilience now determine competitive outcomes. As formulation complexity rises and clean-label expectations tighten, the organizations that succeed will be those that pair sensory science with disciplined market intelligence. PW Consulting’s full study provides the depth, structure, and forward-looking clarity required to make those decisions with confidence.
To access the complete segmentation detail, competitive profiling, and scenario-based strategic recommendations, explore the full Worldwide Bitterness Suppressor and Flavor Carrier Market research on the PW Consulting platform. The complete intelligence suite is available now for teams preparing 2026 formulation, sourcing, and growth strategies.
For detailed analysis of this topic, please visit the official page: Worldwide Bitterness Suppressor and Flavor Carrier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com